banking
(112)
Kris Williams and the distance between a bank and a front door
A geography professor’s daughter became an accountant, then a bank chief. Across her career, Kris Williams kept returning to a practical question: how does money reach the places that need it?
Riyad Bank finances the big picture. And the small stuff.
A child’s payment bracelet and a multibillion-riyal resort loan belong to the same business. Riyad Bank’s bet is that Saudi Arabia needs a bank fluent in both.
Lynn Harton and the art of staying put
After ten moves in his first 25 years in banking, Lynn Harton chose Greenville. His work at United Community asks a larger question: how much can a bank grow while keeping its decisions close to home?
Kyle McElvaney and the long way around the block
He joined Local Oklahoma Bank in 2002. Twenty-two years later, Kyle McElvaney took charge of IBC Bank’s Oklahoma charter - a career that kept widening its reach while staying close to home.
Mechanics Bank got bigger. The bet is staying close.
A Richmond bank built around working people became a four-state franchise. Its next test is making that larger footprint feel personal.
John Asbury and the business of coming home
He returned to Virginia to help an $8 billion community bank grow up. A decade of acquisitions later, John Asbury is working on the harder question: what should a regional bank keep as it gets bigger?
Mizrahi-Tefahot keeps a banker in the picture
Israel’s mortgage specialist built its pitch around a person you can reach. Its digital tools make that promise more interesting - and its history makes it worth examining.
Rodger Levenson and the value of taking the long way
Before he ran WSFS, Rodger Levenson carried hotel bags, trained in Philadelphia banking and learned the business from four different executive desks. His career asks a practical question: how big can a hometown bank grow while keeping its sense of place?
How big can a community bank feel?
United Community grew from a Georgia hometown bank into a Southeast franchise. Its latest move puts a price on a deceptively simple ambition: getting bigger while keeping the banker within reach.
Denis Sheahan and the bank that grew closer to home
An accounting graduate from Cork spent decades learning how Massachusetts banks work. At Eastern, Denis Sheahan is testing how much a local bank can grow while keeping its relationships intact.
Stacy Kymes and the value of starting over
He spent decades learning BOK Financial from the inside. The revealing moments came when the next job made him feel like a beginner.
Jeremy Ford and the long road home
He returned to Dallas to work alongside his father. Sixteen years into leading Hilltop Holdings, Jeremy Ford faces the business of succession, the demands of three financial franchises and a new argument over who should hold the reins.
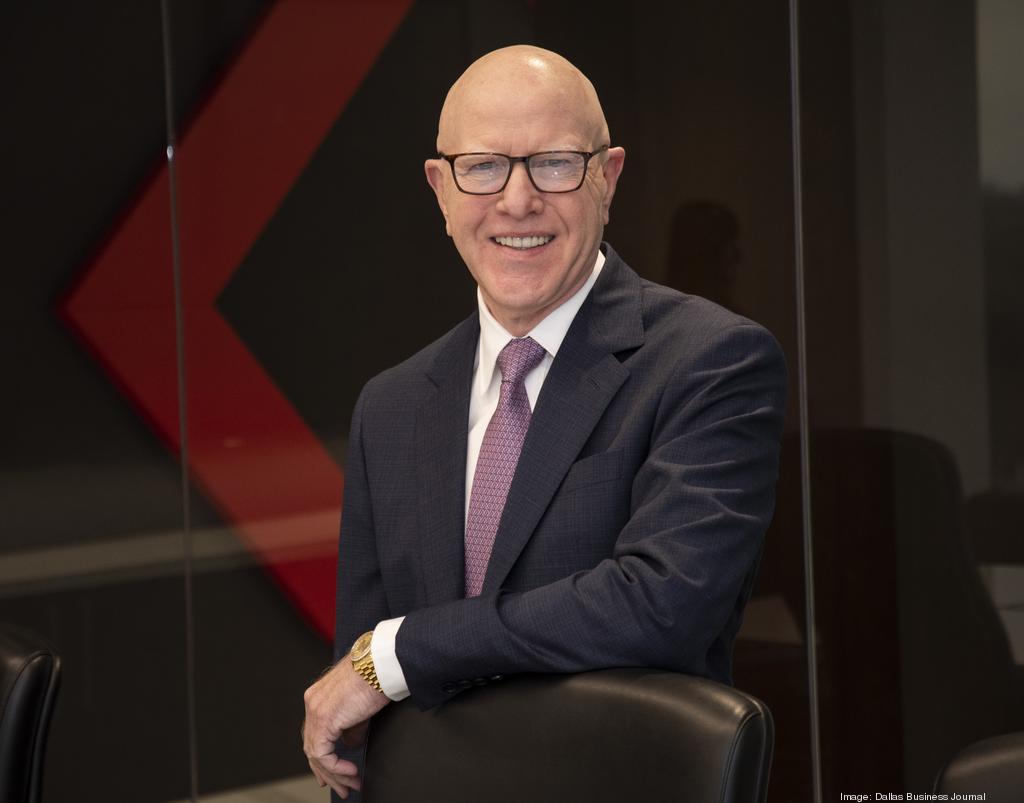
George Gleason and the price of thinking bigger
At 25, George Gleason borrowed $3.6 million to buy control of a small Arkansas bank. Nearly half a century later, the Bank OZK chief is working out how to make the institution less dependent on the business that helped it grow.
John Corbett and the business of staying small
John Corbett helped start CenterState in Winter Haven, then led SouthState into a wider banking map. His enduring question is how much a bank can grow while keeping decisions close to the people it serves.
Chip Kahn and the trouble between things
Alfred “Chip” Kahn IV built businesses around payments and digital networks. At OvationCXM, he is tackling the awkward handoffs that stand between buying a product and getting it to work.
Rob Holmes and the business of coming home
After 31 years at JPMorgan Chase, Rob Holmes took on a Dallas bank in need of a rebuild. His plan joined Wall Street experience to a very Texas belief: the important decisions should be made close to home.
Eastern Bank grew up. Can it stay close?
A bank born with a $100 deposit became a publicly traded regional lender. Its most interesting bet is that getting bigger can help it stay useful to the people next door.
A bank built around the borrower.
Live Oak started with veterinarians and a simple wager: knowing a business could matter more than having a branch nearby. Its national lending machine now shows both the power and the price of that idea.
Andy Harmening and the value of a good question
Before Andy Harmening set a new direction for Associated Bank, he spent 100 days listening. His career offers a close look at how a regional banker turns conversations into decisions - and how much harder that becomes as the bank grows.
Phil Green and the Compound Interest of Staying Put
He joined Frost in 1980 and became its CEO 36 years later. Phil Green’s Texas story runs through bank branches, a stack of employee comments and a guitar shared with his daughter.
John Kemper and the art of staying for the answer
He joined Commerce after a consulting assignment and became its chief executive eleven years later. John Kemper’s career turns on a practical question: what happens after the advice is given?
Richard Fairbank and the trouble with 19.8 percent
A consultant questioned why so many credit cards carried the same rate. Four decades later, Richard D. Fairbank is still rebuilding the machinery around that question.
Kevin Blair and the arithmetic of staying close
After three decades in banking, Kevin Blair is leading the combined Pinnacle and Synovus. His wager: a larger bank can still feel like a local relationship - if the people inside it know what comes next.
Duane Dewey and the art of changing a bank from the inside
He spent seventeen years at Trustmark before becoming CEO. Now Duane Dewey is testing how much a familiar institution can change while keeping its customers along for the ride.
Jule Kreyling and the business of starting over
A Harvard-trained lawyer found his way into sales, then into building equipment-finance businesses. At Atlantic Union, Jule Kreyling put that experience to work one team, one process and one transaction at a time.
Richard Carrión’s other currency
He helped put cash machines across Puerto Rico and Olympic broadcasts into American living rooms. The thread running through Richard Carrión’s career is what happens when people can take part.
Columbia Bank's big bet on small details
A $2 billion deal bought Columbia Bank a bigger piece of the West. Its everyday pitch comes down to something less grand: helping money get where it needs to go.
Nadir Al-Koraya and the long apprenticeship in tomorrow
Before he became Riyad Bank’s CEO, Nadir Al-Koraya spent decades in treasury and investment. Now his work connects the patient arithmetic of banking with Saudi Arabia’s plans for what comes next.
First Citizens Bank and the art of buying time
A bank built for North Carolina farmers became the buyer of Silicon Valley Bank’s lending business. The surprise is how much of its old method survived the trip.
Bank of America and the power of boring
A bank built by mergers is betting billions that the small stuff will keep customers close. Its AI assistant, branch network and fee history reveal what happens when everyday banking runs at enormous scale.