embedded-insurance
(45)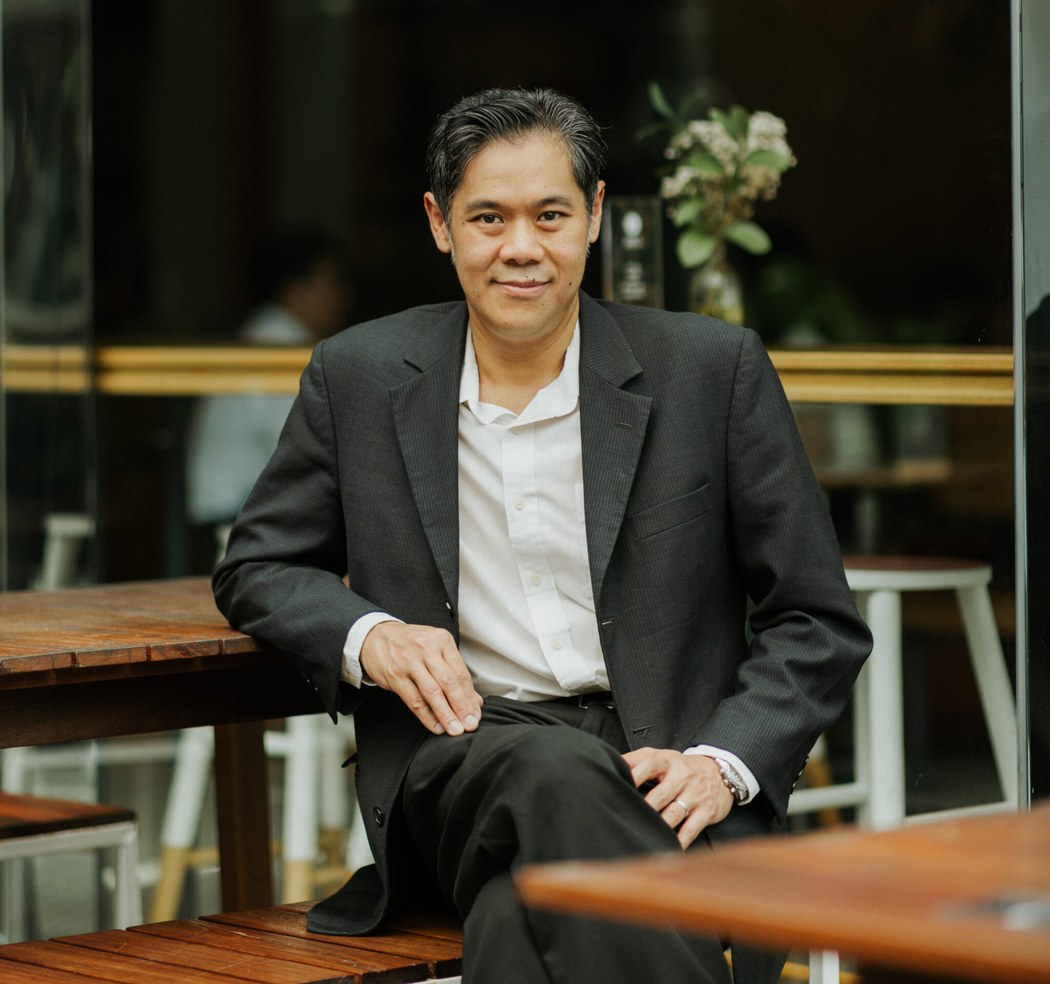
Yen Ming Lee and the trouble with a comfortable job
A banking director took the long way into entrepreneurship. At PolicyStreet, Yen Ming Lee has spent the years since learning how to put insurance where people already are.
Bill Song and the cost of changing your mind
A chemical engineer found his way into insurance, then built Peak3 around the frustrations he met there. Now Bill Song is applying AI to an old ambition: making change less expensive.
Akad Seguros puts the broker in the fast lane
The Brazilian insurer bought a running business, then set about removing the waiting. Its bet: better tools can make the insurance broker more useful.
Chien Ta and the insurance office in your pocket
From aviation risks to an insurance option inside a telecom app, Chien Ta’s career traces a change in how Vietnam buys protection. The GiNET co-founder helped bring an established brokerage into bolttech’s digital distribution network.
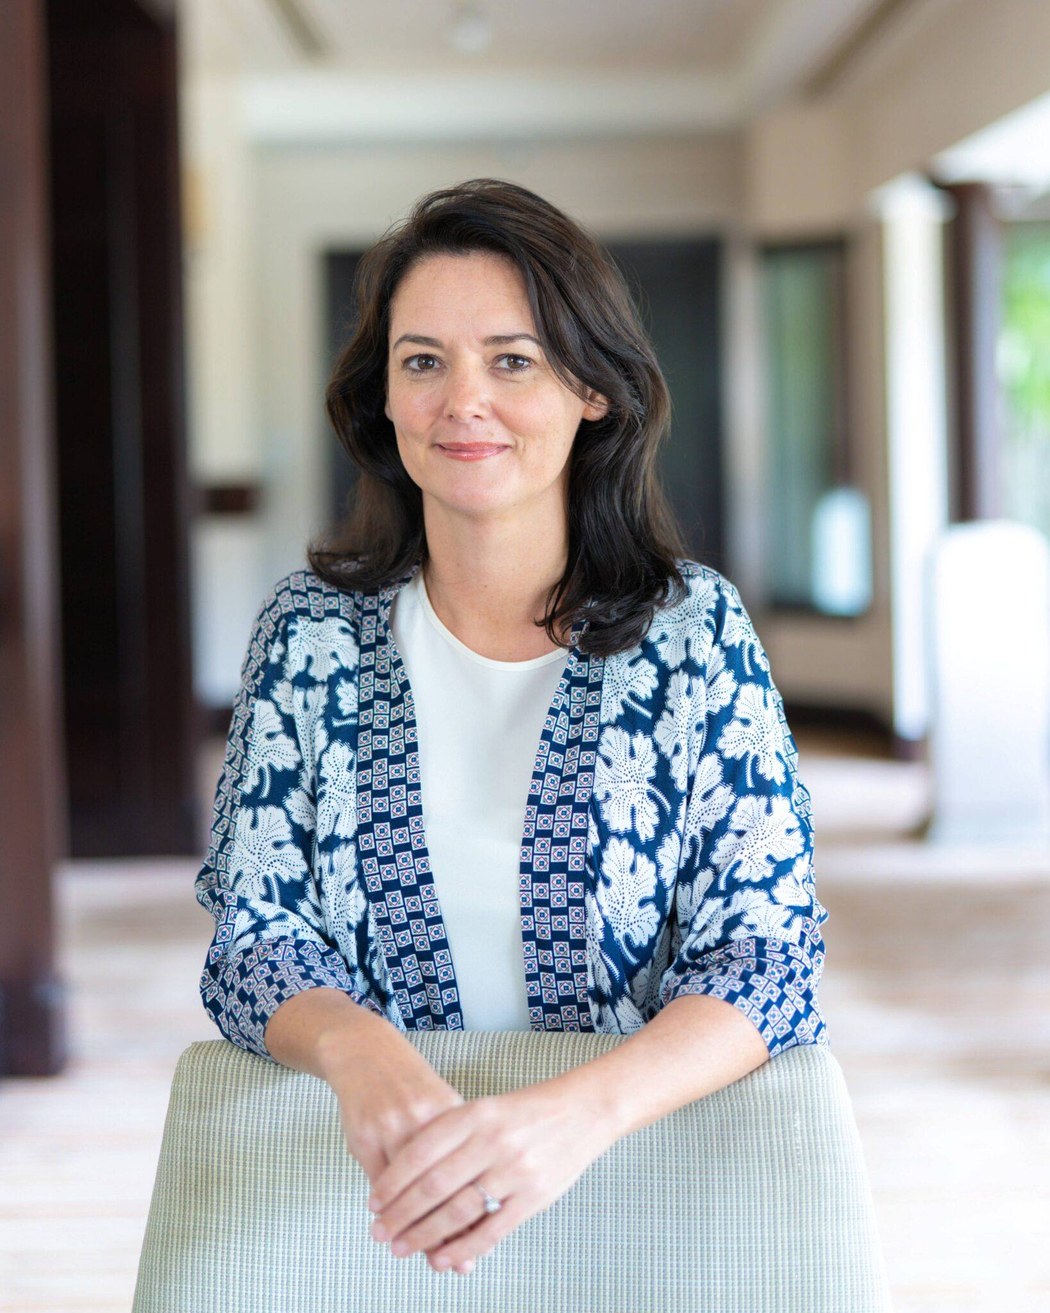
Emma Butler and the business of keeping a promise
After a decade inside the business, Emma Butler has become bolttech’s CEO for Asia-Pacific. Her route to the role runs through the shops, repair services and partnerships that make device protection work.
Steadily puts landlord insurance where the landlords already are
A miserable insurance purchase gave Darren Nix an idea. Steadily has since built a business around the places rental property owners already work, from listing platforms to property management software.
Domecile and the $500 reason to stop printing
Two jammed printers helped inspire BoardPackager. Now called Domecile, the company puts New York’s board applications, building documents and a growing collection of home services into one digital workflow.
Sure found its business behind the app
The insurance app was the opening act. The machinery behind it became a business that lets familiar brands sell protection without building an insurance platform from scratch.
Coverdash puts insurance where the work happens
A business rarely wakes up wanting insurance. Coverdash places it inside the tools owners already use, turning an inconvenient errand into part of getting the job done.
Mulberri wants the paperwork out of underwriting
The insurance software company began by helping small businesses buy cover. Now it is tackling the inbox, the spreadsheet and the quiet administrative chores that keep underwriters from underwriting.
Roadzen and the strangely expensive dent
A camera can spot a damaged bumper. Roadzen is betting that the harder, more valuable job is getting the insurer, the driver and the repair shop to agree on what happens next.
The Smart Lock That Became an Insurance Company
Jared Brier and Eric Schneider set out to build a smart lock. The warranty research sent them somewhere stranger: a business that lets a cracked phone, a school laptop and a carrier checkout share the same machinery.
The Insurance Company Hiding in the Checkout
Tint turns a platform’s awkward coverage gap into insurance offered at the precise moment a customer needs it. Its founders learned the problem at Turo; now they sell the machinery, and sometimes the program, to everyone else.
Jeff Merkel and the Art of Making the Complicated Feel Obvious
Before he helped turn life insurance into an online purchase, Jeff Merkel spent a career carrying difficult technology across the last mile to the customer. His useful obsession is not invention alone, but making invention usable.
bolttech wants to be inside your next purchase
From a Samsung phone to a BYD car, bolttech puts protection into purchases people already make. Its $2.1 billion valuation rests on making that connection work long after checkout.
Openforce Built the Back Office for the 1099 Economy - Now It Has to Make the Mess Feel Invisible
The Scottsdale company moves $5 billion a year through the unglamorous machinery behind independent work. Its bet: the winner in contractor software is the one that turns paperwork, insurance and payments into one clean trail of proof.
Henry Mascot Is Teaching Insurance to Move at Software Speed
A student app, a million-naira prize and one well-timed pivot led Henry Mascot to the unglamorous machinery beneath insurance. Now he is asking how much of a company can run at software speed.
David Embry Bet Small Businesses Deserved Better Insurance - Then Built the Machine to Prove It
Mylo began with a stubborn question: could software make small insurance accounts worth serving well? A decade later, David Embry's answer is a business built around better recommendations, patient iteration and the enduring value of a human conversation.
Mark Scafaro Found the Insurance Shortcut: Keep the Agent, Delete the Waiting
Life insurance spent years trying to automate away the people who sell it. Mark Scafaro built Afficiency around a more practical idea: preserve the human conversation, then make everything around it move in one sitting.
Afficiency Found the $10 Billion Insurance Shortcut: Help the Agent, Skip the Exam
Life insurance’s first digital bet was to remove the agent. Afficiency took the more useful route - remove the paperwork, keep the human, and turn a process measured in weeks into one sitting.
The Insurance Broker That Turned Itself Into an API
Born inside the world's largest independent broker, Mylo spent a decade turning insurance advice into software other companies can plug in. Here is how a Kansas City team quietly became the insurance layer behind small-business platforms.
The Quiet Subscription Empire Behind the Broken Washing Machine
Domestic & General built a billion-pound business around the moment a fridge stops humming. Its real product is not a warranty - it is the network, data and recurring relationship that make an ordinary household crisis fixable.
TruStage
Born to make a borrower's debt die with the borrower, TruStage now spans life insurance, annuities, embedded loan protection and a credit-union stablecoin. Its real product is the bridge between old financial trust and new financial plumbing.
MetLife
The 158-year-old insurer is becoming a three-engine financial platform: workplace benefits, retirement-risk transfer and global asset management - all hidden behind one familiar blue-and-green M.
The Baldwin Group
The Tampa firm grew from a Florida brokerage into a $1.5 billion national platform. Its next act is less about selling policies than connecting advice, underwriting, embedded distribution and AI into one insurance operating system.
Chubb
Chubb can insure a Vermeer, a vineyard, a ransomware attack and the cargo crossing an ocean. Its real product is disciplined judgment - sold through brokers, agents and digital partners across 54 countries and territories.
bolttech
A Singapore insurtech quietly turned the checkout button into an insurance counter. Now 230 insurers and 700 partners run through its pipes.
Curacel
Curacel is an AI-powered insurance infrastructure company building the rails for insurance in emerging markets. Its cloud APIs let insurers automate claims processing and catch fraud, waste and abuse, while its Grow product lets banks, fintechs and e-commerce platforms embed insurance into their own apps. A Y Combinator Winter 2022 company founded in Nigeria, Curacel works with insurers such as AXA Mansard, Old Mutual and Jubilee across roughly ten African markets.
Democrance
Democrance is a Dubai-based B2B insurtech that sells insurers a lightweight, cloud-based core platform - Democrance Pulse - which sits on top of legacy systems rather than replacing them. Founded in 2015 by Michele Grosso, Alberto Perez and Dr. Damian Dimmich, the company began by trying to sell low-cost microinsurance to people in emerging markets who had never held a policy, then discovered that the real bottleneck was the insurers' own technology. Today its no-code product configurator, distribution portals, underwriting engine and API library let carriers including AXA, MetLife, AIG, Manulife, Zurich, Tokio Marine and Sukoon launch and administer life, health and P&C products in days rather than months, across 15-plus markets in the Middle East, Africa, Asia and Latin America. The mainstream book cross-subsidises the microinsurance one, which is how a financial-inclusion mission survives contact with a P&L.
Inclusivity Solutions
Inclusivity Solutions is a Cape Town-based inclusive insurtech that designs and delivers embedded, affordable digital insurance for emerging consumers across Africa. Through its open-API platform ASPin, it partners with banks, telcos, insurers and fintechs to build, sell and administer low-cost products - life, accident, hospital cash, device and crop cover - distributed via mobile channels people already use. The company operates in roughly ten African markets and has served over two million customers.