expense-management
(63)
Airbase and the Cost of Asking Too Late
A company can approve a purchase in minutes and spend weeks explaining it. Airbase built a business around closing that gap - and gave Paylocity a route from payroll into the rest of the company’s spending.
Finally Wanted to Finish the Books. The Books Outlasted Finally.
Finally put bookkeeping, corporate cards and back-office chores under one roof. Its September 2026 wind-down leaves a sharper question: what, exactly, should survive the company you hire to handle your money?
The Sneaker Bank That Outgrew Sneakers
A banking startup found its first customers in sneaker raffles. When that market fell apart, Slash used the lesson - build around the customer's actual money movements - to pursue a much bigger business.
Karim Atiyeh and the Art of the Invisible Task
The Ramp co-founder built a career by noticing the tiny chores everyone else accepts. Now, as co-CEO, he is trying to make finance software do the work before anyone has to ask.
The Fine Print Behind PayEm's $247 Million Headline
PayEm set out to turn every company purchase into a controlled, traceable decision. Its journey from expense-report frustration to a $500,000 acquisition is also a lesson in reading fintech's biggest numbers carefully.
Serko’s big business is behind your business trip
The Auckland software company put its technology inside Booking.com for Business and bought a bigger seat in corporate travel. Now it must make growing booking volumes pay - while teaching AI to handle the itinerary.
Dext built a business on the receipts nobody wants to type
Receipt Bank grew by tackling the drudgery before the ledger. Now part of IRIS, Dext is expanding into data checks, AI assistance and payments - with a business case that still comes down to minutes saved.
Webexpenses Wants the Receipt to Disappear Before Finance Has to Chase It
The Witney software company has spent 25 years turning the office's least-loved ritual into a controlled flow of data. Its bet is simple: catch the receipt, policy breach and coding error while the purchase is still fresh - not during month-end archaeology.
ANNA Money Put the Accountant Inside the Business Account - Then Made the Card Miaow
Britain did not need another coral-coloured card. ANNA bet that small firms needed the invoices chased, receipts matched and tax calculated around it - all through a chat that knows when to call a human.
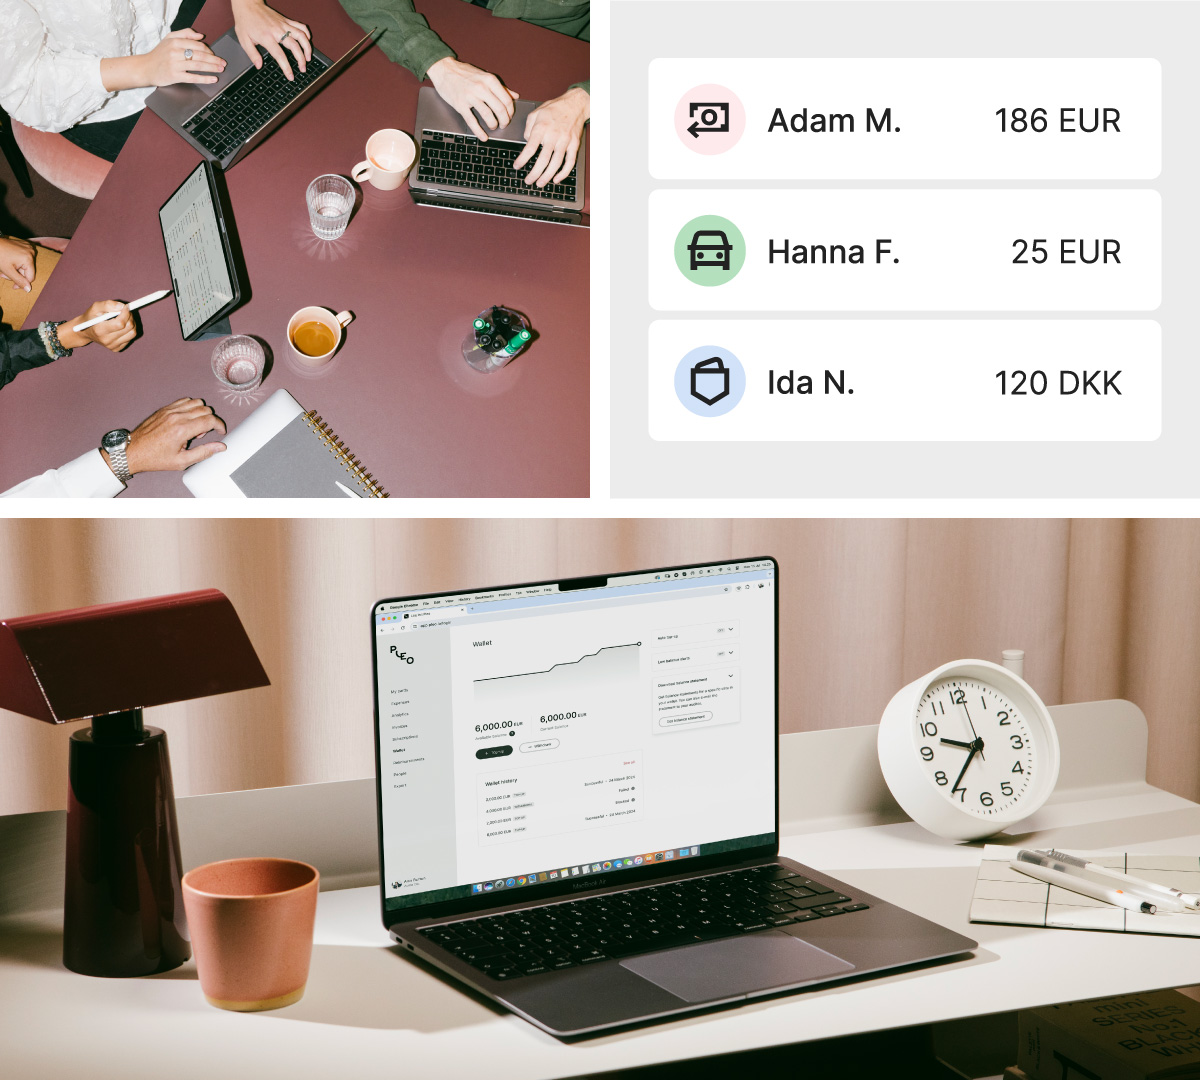
Pleo Makes Expense Reports Feel Like a Fax Machine
Give people a card, ask for the receipt while it still exists, and let finance watch the books assemble themselves. Pleo turns a monthly scavenger hunt into a daily habit - with a few fees and fine-print decisions worth making before you tap.
Brex Put the Expense Report on a Short Leash
The startup card grew into a control room for company money. Its best trick is catching bad spend before finance has to chase it, but the grown-up platform deserves a grown-up buying process.
Spendesk Puts a Bouncer at the Company Wallet
Employees get a faster route to the company card. Finance gets to decide the route, the limit and who waves it through.
Mesh Wants Your Expense Report to Disappear
Mesh is trying to make travel and expenses vanish from the employee’s to-do list without making control vanish from finance. The idea is sharp; the buying decision still comes down to integrations, geography and whether the mobile experience can keep up.
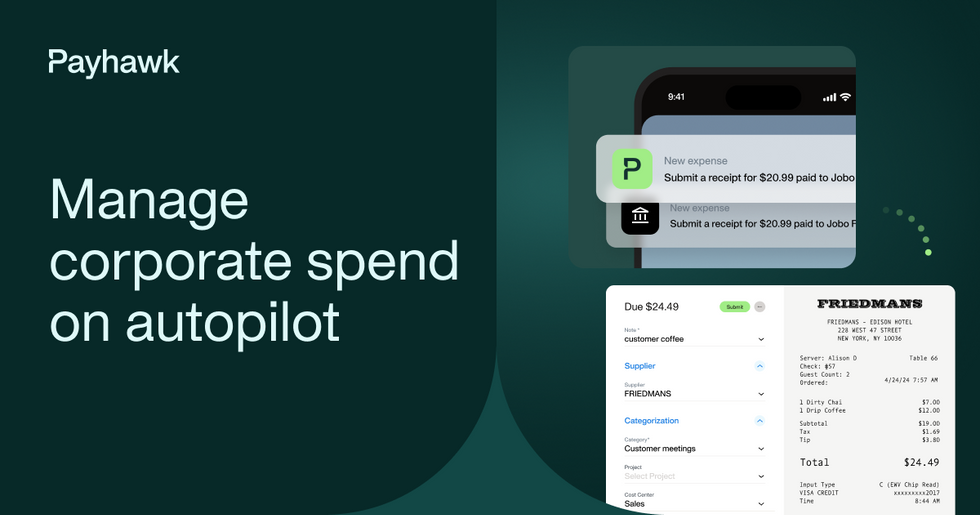
Payhawk Wants Your Company Card to Do the Paperwork
Payhawk bolts policy, receipts, approvals and accounting data to the moment money moves. For finance teams juggling countries and entities, that can turn the company card from a plastic problem into a useful control surface.
TravelPerk Grew Up. Your Expense Report Came Along.
The booking tool once known as TravelPerk now wants the whole awkward trip - approval, receipt, invoice and all. Here is where Perk earns its keep, where the fees bite, and who should put it on the shortlist.
BILL Put the Back Office on Autopilot - Then Turned It Into a $371 Billion Money Highway
Small businesses came for fewer checks and cleaner approvals. BILL stayed to build the payment rails - a network moving more than 1 percent of U.S. GDP while quietly turning accounting chores into transaction revenue.
The Expense Report That Refused to Die: How Concur Turned an $8 Million Near-Miss Into SAP’s $8.3 Billion Cloud Bet
Concur began with floppy disks and a universal workplace nuisance. Three pivots, one near-death cloud bet and a record SAP acquisition later, it is trying to make the expense report disappear altogether.
Oded Zehavi Wants Expense Reports to Vanish
After three decades in payments, the Mesh co-founder is chasing an oddly radical outcome: business spending that explains itself before finance has to ask.
Procurify Wants to Catch Every Bad Purchase Before the Money Moves
The Vancouver company found a valuable gap between spreadsheets and enterprise procurement suites. Now it is betting that a decade of customer spend context can turn AI from a chatty assistant into a careful operator.
Torpago Quit Chasing Ramp - and Turned the Banks Into Customers
Brent Jackson built a credible corporate-card challenger, then decided he was fighting in the wrong arena. Torpago's sharper bet is to give community banks the software, controls and operational muscle to run modern card programs under their own names.
The Card Network Ate Center. Emburse Ate Everyone Else.
Two expense-software empires took opposite roads to the same prize. Emburse spent years stitching together aging brands like Certify and Chrome River; Center simply handed the keys to American Express - and finance teams are the ones who have to live with the difference.
Mayank Kukreja Took the Expense Report Personally
After nearly 200 days a year on the road, the former engineer, consultant and Myntra operator turned a familiar office annoyance into ITILITE - then learned to rebuild a travel company while nobody was traveling.
Brex and Rippling Want Your Spend for Different Reasons
Brex built a finance stack and learned to choose its customers. Rippling built a workforce system and turned spend into one more reason to stay.
Ramp and BILL Are Fighting to Own Every Company Dollar
BILL bought Divvy to move beyond paying invoices. Now its fight with Ramp is a contest over who gets to control business spending before, during, and after the swipe.
Ramp and BILL Are Selling Two Different Kinds of Control
The expense tools look increasingly alike. The choice comes down to whether finance wants a standalone command center or spend management inside a broader back-office suite.
The $99-a-Month On-Ramp to Enterprise Software
Jcurve built a business around the awkward moment when accounting software stops being enough. Its answer is an ERP ladder - start small, connect the moving parts, and keep climbing without ripping everything out again.
NetSuite Already Has The Controls So Why Bolt On Ramp
NetSuite bakes spend controls and approval workflows straight into its general ledger. So the finance team's real decision is not which tool wins, but whether to run the module they already own or bolt Ramp's card platform on top of it.
Flex
Flex is an AI-native private banking platform for high-net-worth, middle-market business owners. It bundles credit, business and personal banking, payments, AP automation, expense management, and ERP-style tooling into a single super app aimed at owner-operators of $3M-$100M revenue companies.
Stop Comparing Finance Tools Feature by Feature
Brex, Rho, Rippling Spend, Wise Business, and Arc overlap on paper. The useful choice begins with the workflow your company cannot afford to get wrong.
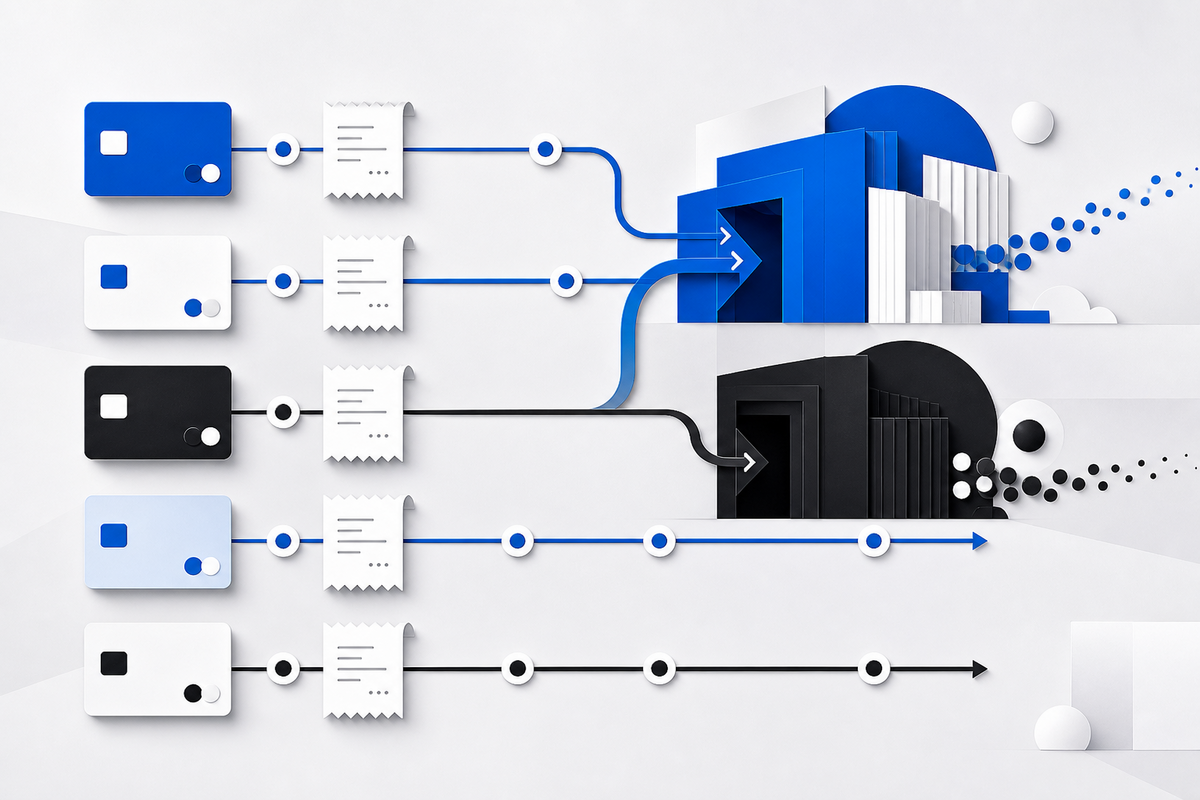
The Spend Stack Is Shrinking Before Your Eyes
Ramp, BILL and Emburse still compete for the finance desk. Airbase and Center now live inside larger companies, changing what buyers are really choosing.