The first thing BILL sold was relief. No more stack of invoices migrating across a desk. No more executive trapped beside a checkbook. No more month-end archaeology expedition through emails, receipts and a spreadsheet named FINAL_v7. A small business could send a bill to an inbox, route it to the right approver, pay by ACH, card, wire or check, and send the result back into its accounting system.
That sounds like sensible software. The bigger idea was hiding underneath: every approval eventually becomes a payment. BILL did not merely organize the paperwork around money. It put itself in the path of the money.
By June 2026, 479,300 businesses used one or more BILL solutions. Its network counted 9.2 million members that had sent or received an electronic payment. Revenue for the year reached $1.653 billion, up 13 percent. The old SaaS story says you rent software by the seat. BILL still does that, but its fiscal 2026 transaction fees were $1.211 billion. Subscription fees were $293.5 million. The workflow is the front door; payments are the building.
Born three hours after the books closed
Founder and CEO René Lacerte has an origin story suspiciously well suited to a fintech biography. His parents and grandparents ran a data-processing business that took accounting ledgers from small companies and turned them into printed financial records. The night he was born, his parents finished a general-ledger, payroll and accounts-payable job around 12:30 a.m. He arrived at 3.
Lacerte later worked at Intuit, where he managed bill-payment products and helped launch connected payroll. His first entrepreneurial idea was not BILL. It was an employee-leasing concept for household workers, an awkward wedge into benefits and payroll that did not become the company he imagined. The useful instinct survived the bad packaging: small employers had expensive financial chores and lousy tools.
That instinct became PayCycle, an online payroll company eventually bought by Intuit. Then, in 2006, Lacerte started CashView. Two years later it became Bill.com. The company linked with the accounting profession early, added accounting-system sync, automated checks and ACH, and let accountants manage many client entities from one console. This was distribution disguised as product design: accountants did not merely recommend the tool; they could run their work on it.
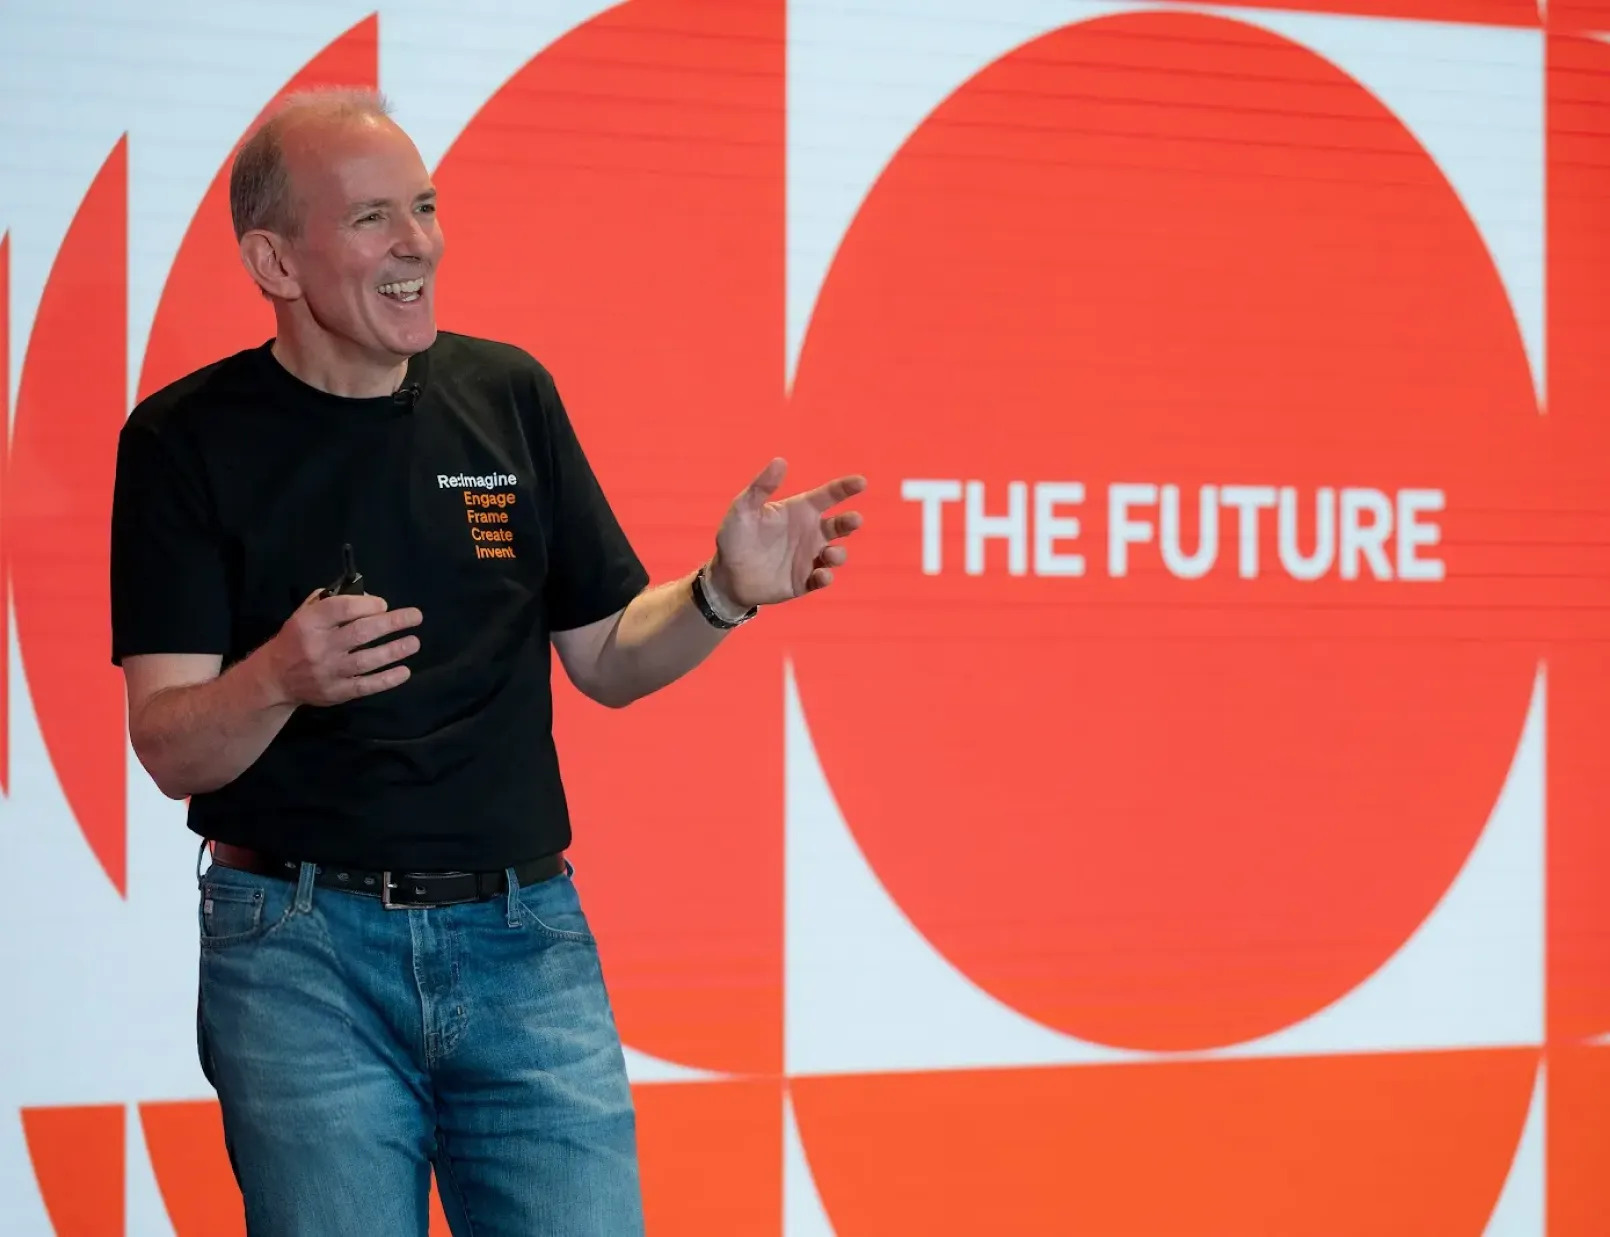
I have been in and around fintech since the day I was born.René Lacerte, founder and CEO
A control room for money that has not stood still
The product now covers the route from an invoice arriving to the books being reconciled. Accounts Payable captures invoice data, checks for duplicates, sends bills through configurable approvals and schedules payment. Accounts Receivable creates invoices, accepts money and automates reminders. Two-way integrations with QuickBooks, Xero, Sage Intacct, NetSuite and other ledgers are central, because automation that ends in retyping is just a prettier queue.
Spend & Expense handles the purchase before a conventional invoice appears. Finance teams issue physical or virtual BILL Divvy Cards, set budgets and merchant rules, and see transactions in real time. Employees attach receipts in the app. The software is free of subscription and per-user charges; BILL earns interchange when the card is used. Credit lines depend on approval, and payment methods elsewhere in the suite can carry transaction fees.
The newest layer is BILL AI. Its agents handle jobs such as complex invoice coding, W-9 collection, reconciliation and customer assistance. In 2026, BILL also launched Travel so employees can book trips within policy and send the resulting spend into the same control system. The pitch is no longer “pay this bill.” It is “run the financial back office from here.”
The wrapper is software. The engine is movement.
The $3.1 billion shopping trip
The company did not build every room in this control center itself. In 2021 it paid roughly $2.5 billion for Divvy, using $625 million in cash and about $1.875 billion in stock. Divvy brought corporate cards, budgets and expense management, plus an estimated $100 million annualized revenue run rate at the time. A few months later, BILL bought mobile invoicing company Invoice2go for about $625 million. Forecasting startup Finmark followed in 2022.
What changed the company's mind about staying a bill-pay specialist? Customers were already saying it. Divvy's team reported that businesses wanted one platform instead of several financial systems. BILL had approvals and payments but did not control card spend. Divvy had the card and budget data but lacked BILL's broad payables, receivables and workflow network. The combination was expensive because the gap was strategically obvious.
The bet can now be seen in the income statement. Spend & Expense produced $675.6 million of transaction revenue in fiscal 2026, up 22 percent. That is slightly below the $740.1 million of subscription and transaction revenue generated by AP and AR together. The acquisition moved from sidecar to nearly half of BILL's integrated-platform revenue.
The moat wears an accountant's sensible shoes
BILL competes with Ramp and Brex in spend, Tipalti and AvidXchange in payables, Expensify in expenses, and the expanding financial modules inside QuickBooks and enterprise suites. Yet the company names manual work as its primary competitor. That is not rhetorical camouflage. Many small organizations still move approvals through email, share a corporate card and reconcile after the fact.
Its difference is breadth tuned for the middle. Large enterprise platforms can be heavier; point solutions can be sharper in one category. BILL connects AP, AR, cards, expenses and payments, then distributes them through the people and systems a small business already trusts. As of March 2026, 98 of the top 100 U.S. accounting firms partnered with BILL. Banks can embed a white-label version. Paychex, Oracle NetSuite and Acumatica are newer embedded channels. Every partner adds customers, and every customer can invite suppliers into the payment network.
The less my clients have to think about the process, the happier they are. They want the experience of the thing being done.Shazam Accounting, on using BILL
The cleanest metric is a missing afternoon
BILL's customer evidence is most persuasive when it stays close to the clock. TED Conferences says automating payables cut its AP time and effort by 60 percent after a process that once required a CFO to sign as many as 150 checks a week. Apparel company Marine Layer says its small finance team handles 200 to 300 weekly invoices and saves at least a couple of hours a day. Chattanooga Christian School reported that a 32-hour manual AP workload fell to 18 hours after moving approvals online and connecting the process to Sage Intacct.
The less tidy cases show what fails first. RenewalMD traced confusion in its check process to payment errors and fraud, while a card statement carrying roughly $30,000 of monthly charges turned reconciliation into a page-by-page chore. Its reason for changing was not a love of dashboards. It wanted fewer checks in circulation, dedicated virtual cards for vendors and charges flowing into QuickBooks with the correct general-ledger code. Reconciliation that had delayed the monthly close by several weeks began updating within about a day.
Those are individual customer results, not a promise that every implementation will reproduce the percentages. They reveal the buying trigger more clearly than a feature matrix does: the existing routine has become costly enough, risky enough or slow enough that changing systems finally feels easier than preserving it.
What a finance team can actually copy
The most useful BILL customer stories begin small. Map who receives, codes, approves and releases a bill. Move predictable, low-risk invoices first. Keep duties separate: the person entering a bill should not be its only approver. Add a digital audit trail, then connect the accounting ledger. One nonprofit adviser started with four executives and recurring utilities; within three weeks, the bookkeeper recovered three hours a week. Only after the team trusted AP did it replace the shared card with controlled spend.
Begin with recurring invoices and a written approval map. Prove the route before moving every payment.
Count seats, payment methods, card rewards and transaction fees - not just the monthly software price.
Document roles, export records and preserve bank controls. Automation should reduce key-person risk, not rename it.
The conditions matter. BILL is compelling when invoice volume is real, approvals cross several people, remote access matters and the accounting sync eliminates duplicate work. It is less convincing for a solo operator paying five bills a month, a company satisfied with free bank bill pay, or a large enterprise whose procurement rules already live deep inside a customized ERP. International reach is broad, but country, currency and payment-method coverage still need checking. And no automation removes the need to verify vendors, protect credentials and review exceptions.
BILL ended fiscal 2026 with an 80.9 percent gross margin and a small $11.2 million GAAP loss. It had also cut headcount to 1,683, announced a remote-first shift and spent money responding to activist shareholders. The next proof is harder than digitizing checks: show that AI agents, embedded distribution and the integrated suite can keep growth moving while competitors copy features and customers scrutinize cost.
Still, the enduring lesson is pleasantly unglamorous. Find the job that recurs every week, where mistakes are expensive and nobody wants to become an expert. Make it legible. Put controls around it. Then notice what passes through. BILL started with the paperwork and ended up standing beside the money.