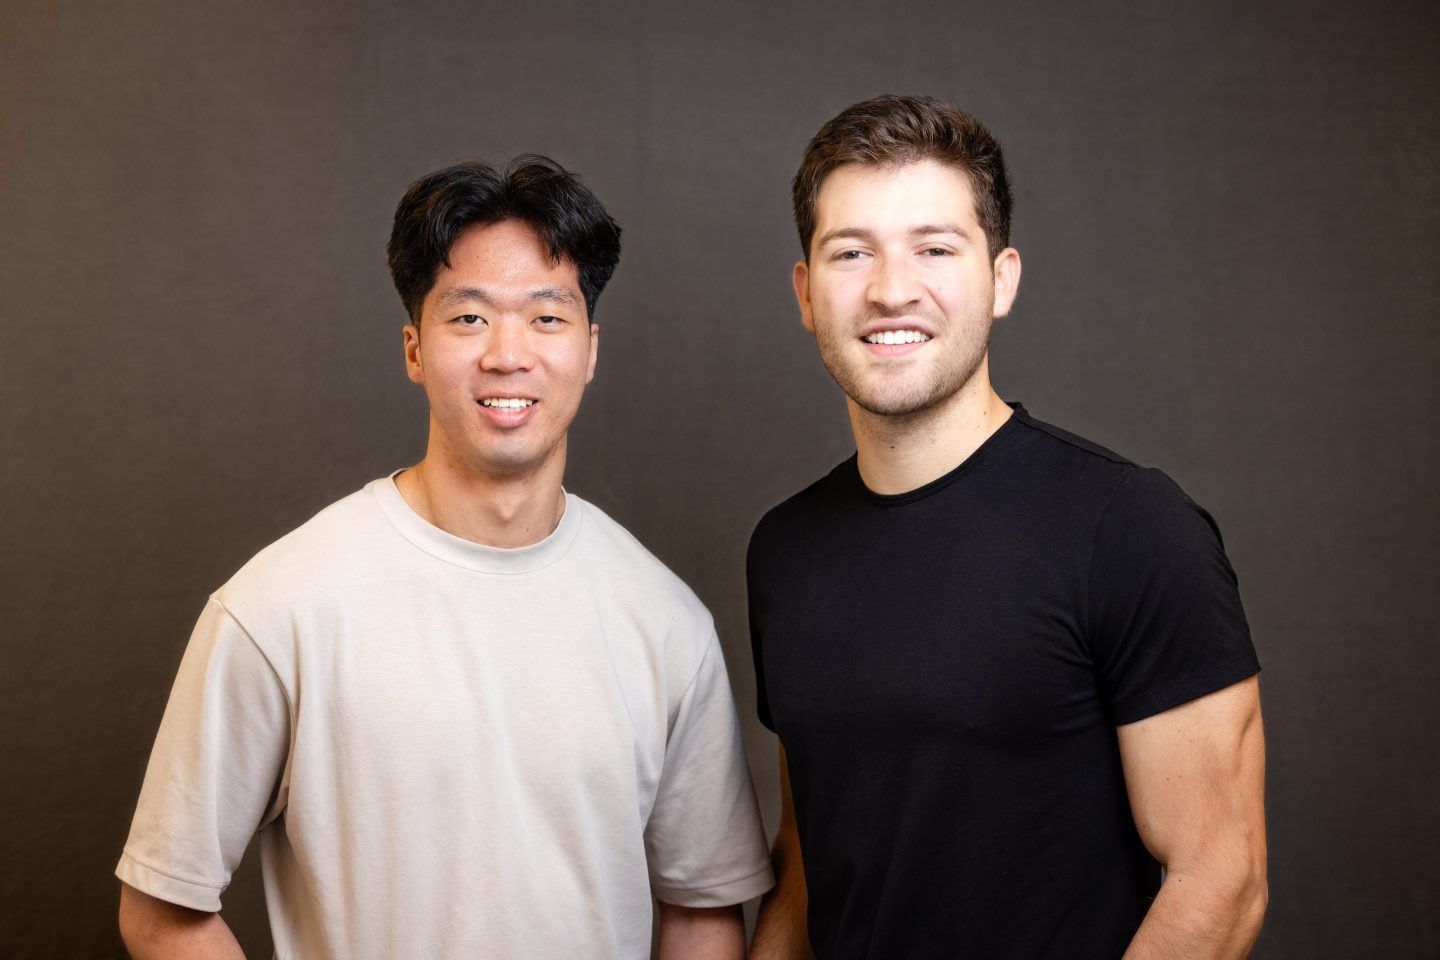
The first version of Slash had a peculiar customer request: more cards. Sneaker resellers needed enough virtual card numbers to enter competitive raffles at scale. To an ordinary bank, this could look like an eccentric edge case. To Victor Cardenas and Kevin Bai, the founders of Slash, it looked like a product specification. They built for it, and the resellers came.
- Slash bundles business accounts, corporate cards, expense tools and payments in one dashboard.
- Its first niche - sneaker resellers - weakened, pushing the company toward larger businesses and more industries.
- The published entry price is $0 a month; Pro starts at $25 a month, with separate fees for some transfers and services.
- In April 2026, Slash raised $100 million at a $1.4 billion valuation.
It was a good business until the business around it changed. The Yeezy brand's collapse helped puncture the sneaker resale market that had fed Slash's early growth. Cardenas later described the loss of that growth engine as nearly overnight. He also called it the best thing that happened to the company - an unusually cheerful verdict on watching your first market vanish.
The pivot did not require forgetting the resellers. It required remembering exactly why they had liked Slash: not because they wanted a prettier balance screen, but because a financial tool let them do a specific job. That distinction now runs through the whole company.
One customer's odd problem can be a map
Cardenas and Bai started working on Slash in 2021. The early pitch was banking for self-employed people, with resellers at its center. A connection through Y Combinator brought the founders close to sneaker traders; a head of customer success with resale experience helped them understand the trade. Slash says it reached $5 million in annual recurring revenue within about a year of finding that initial fit and announced $19 million across seed and Series A rounds in 2023.
Then came the awkward question: if the sneaker customer was gone, who else had financial work that a bank account should help perform? Slash chose a series of answers rather than one grand abstraction. Agencies needed to separate spending by client. Wholesalers wanted another route for cross-border payments. Contractors had jobs and crews to track. A growing team needed permissions that would keep one employee's card from becoming everyone's problem.
“Your bank account should adapt to your business, not the other way around.”Victor Cardenas, Slash co-founder
The resulting product is a business finance stack. Slash offers checking accounts through its partner bank, Column N.A.; physical and virtual corporate cards; limits and spend policies; expense reports and reimbursements; accounting connections; treasury products; international transfers; and supported stablecoin payments. In September 2026, it added card payment acceptance for invoices and embedded checkout. The money can now arrive, move and be recorded in the same system.
The account is the interface
For a marketing agency, the practical version might be one card per advertising account, with limits and a virtual account for each client. For an e-commerce operator, it could be a payout from a storefront, a supplier payment abroad and a card purchase for inventory. For a healthcare group, it may be separate accounts by practice location and expense approvals for staff. These examples explain why Slash talks about industries so often: the same financial rails become valuable for different reasons.
The platform's main distinction is proximity to the transaction. A standalone expense app sees a charge after it happens. A card and account platform can decide whether the charge is allowed, record it immediately and carry its data into the books. Slash's engineering team has described a three-second window to approve or decline a card authorization. In that interval it checks balance, spending controls and fraud signals. A timeout can mean a declined purchase for a business placing a time-sensitive order. The plumbing, rather than the polished dashboard, is where this promise is tested.
These are company-reported measures, and annualized volume is a run rate, not a year's settled total. They still show the distance from the raffle-card niche. Slash's April 2026 release also reported more than $250 million in annualized revenue and more than $1 billion in annualized stablecoin payment volume within nine months of launching that product. A founder post from the same month gave a lower customer count, more than 5,000 companies; the release said more than 10,000 businesses. The exact denominator deserves a question, but the direction is plain.
What the convenience costs
The list price is refreshingly readable. Slash's Free plan starts at $0 a month and offers unlimited virtual cards. Its Pro plan starts at $25 a month and removes listed fees on same-day ACH, domestic wires and outgoing real-time payments. International wires are listed at $25 on both plans. The free tier lists $6 for a domestic wire and $1 for same-day ACH. Stablecoin conversion has its own fee; Slash's help center currently lists 1.5% for supported on- and off-ramps. Card foreign transaction charges also apply. These are September 2026 published terms, and a customer should calculate their likely mix of payments rather than judge by the monthly price alone.
Slash is a financial technology company, not an FDIC-insured bank. Column N.A., an FDIC member, provides banking services. That arrangement matters to anyone evaluating deposits or card terms. So does eligibility: the core business account requires a qualifying US entity, while Global USD addresses eligible businesses outside the United States. Payment processing is subject to review, and not every product will be available to every business.
There are obvious alternatives. A traditional business bank may be enough for a company with simple payments and a bookkeeper who likes the existing process. Ramp and Brex compete in cards and spend management; Mercury is another modern business banking choice. Slash's case becomes stronger when a company can use several pieces at once: accounts, controlled cards, supplier payments, invoices and reconciliation. Its advantage is less a single extraordinary feature than the number of times the same transaction data can be used without re-entering it.
The next customer is not a sneaker reseller
The 2025 Series B raised $41 million at a $370 million valuation. The April 2026 Series C brought in $100 million, led by Ribbit Capital with Khosla Ventures and Goodwater Capital co-leading. This money bought Slash room to build, but it also bought a harsher standard of proof: a wide platform has to serve each new industry well enough that customers keep their money and daily operations there.
The company's newer tools point toward that test. Twin, its AI assistant, can analyze account information and perform selected actions. Payment processing adds incoming card revenue to a system that already handles outgoing funds. Visa DPS supports the card program and its authorization controls. Each addition is plausible on its own; together they ask a larger question about whether a bank account can become a working surface for the financial back office.
A founder copying Slash's path should start with a task, not a slogan. Find the customer who repeats an expensive financial chore every day. Build the smallest tool that changes that day. Then ask which adjacent customer has the same underlying problem in a different costume. The sneaker raffle was not the future of banking. It was a remarkably specific clue.