Consider an employee who needs to buy something for work but has no company card. The usual workaround is familiar: pay personally, keep the receipt, ask for reimbursement. The purchase is quick. Explaining it comes later. Elan Corporate Payment Systems builds tools for changing that sequence: give the person spending authority, attach limits, and let the transaction leave a record.
- Partner banks bring Elan’s commercial payment tools to their clients.
- Physical and virtual cards put boundaries around business spending.
- Reporting and AP tools connect the purchase to the accounting work.
The bank behind the bank
Elan sits inside Elan Financial Services within U.S. Bank. Its corporate-payments business serves commercial and public-sector organizations through financial institution partners. That gives it two constituencies: the bank that wants payment capabilities for its clients, and the finance team that has to make those capabilities useful on Monday morning.
Renasant Bank provides a concrete example. Its One Card offering comes from Elan and combines purchasing and corporate-card functions. A customer can approach a familiar bank for a program whose payment machinery comes from elsewhere. The distribution relationship is part of what Elan sells.
The business is therefore a banking service with software around it. Elan identifies itself as the creditor and issuer on its Commercial Rewards Card page. TravelBank supplies the combined management experience. For a buyer, understanding those roles helps separate questions about credit and program terms from questions about how employees submit expenses.
This puts Elan in the market for commercial cards and spend management, alongside other bank programs and software-led providers. TD, for example, also offers combined purchasing and travel cards, controls and reporting. Those features alone do not distinguish Elan. Its partner-bank route, combined with account tools and software partnerships, explains its particular place.
Permission, with an expiry date
The One Card combines travel, entertainment and purchasing expenses. Administrators can set limits and merchant-category permissions. A Managed Spend Card handles more unusual assignments, including projects, grants and relocations, with declining-balance and pre-funded options. The underlying question is practical: how much authority does this particular job require?
Easy Pay addresses the occasional spender. An administrator enters recipient details, chooses a credit limit and expiration date, then sends a virtual card. The recipient can use card details online or add the card to a mobile wallet. Elan also supports creating up to 500 cards through a file process. Temporary authority can be issued in batches.
Virtual Pay takes a related idea into supplier payments. Its cardless accounts can be restricted to a supplier, an amount and a date range. Elan supplies an enrollment team to help bring vendors aboard. That last detail is revealing. A payment method needs someone willing to receive it. Distributing account numbers is only one part of adoption.
A payment still has to become an entry
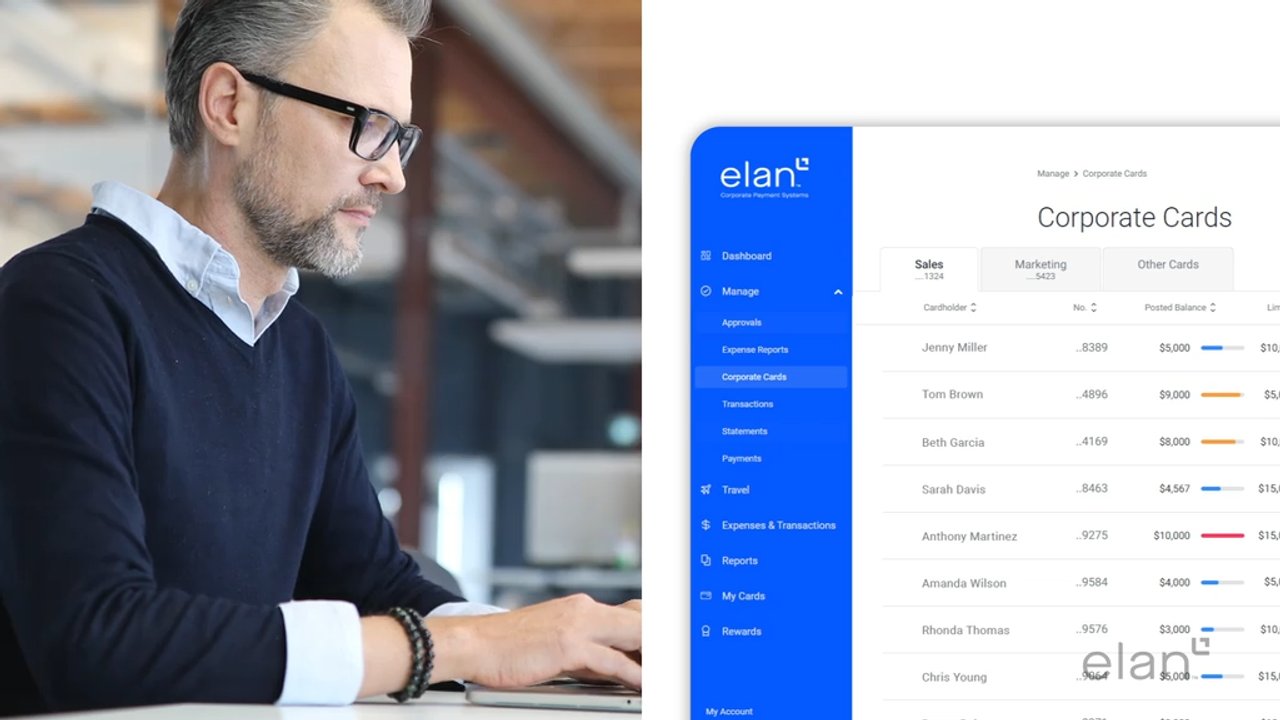
After permission comes administration. Access Online lets program managers maintain accounts, inspect transaction histories, retrieve spending data and extract information for financial systems. The point is to make a purchase usable as accounting information without repeatedly typing it into another screen.
Program monitor adds continuous, rules-based transaction review. Elan says it can review all card transactions and flag suspected misuse or policy violations. The distinction matters: coverage describes which transactions get checked. A flag still requires interpretation and follow-up. Neither a dashboard nor a rule relieves a company of deciding what to do next.
“There’s no charge for card, card management, and travel and expense.”
Elan Commercial Rewards Card FAQ
For the invoice side, Elan works with PaperTrl. A single file can carry instructions for checks, ACH and virtual cards. PaperTrl routes instructions to the appropriate processors and provides consolidated reporting. Existing ACH bank relationships can remain in place. Its AP automation offering also covers invoice entry, approvals, three-way matching and reconciliation.
Notice what that arrangement preserves. An organization can change how it assembles payment instructions while retaining its ACH providers. That is a different proposition from asking a finance department to move every banking relationship at once. It gives the discussion a manageable unit: the payment workflow, rather than the entire treasury operation.
Zero is a price. It isn’t a business case.
The Commercial Rewards Card brings cards, expenses and travel into a TravelBank-powered platform. Its dedicated product page targets organizations with up to $150 million in annual revenue, offers points or rebates, and publishes no annual fee. The FAQ states that the card, management, travel and expense platform carry no charge. It also lists accounting integrations, including QuickBooks Online and NetSuite.
Virtual Pay’s overview separately advertises its service at no cost, and Elan’s Program Optimization assessment is also free. These are specific published offers. A finance team still needs a calculation that includes setup work, supplier acceptance, accounting connections and the terms of its chosen program. A fee line cannot measure the hours spent changing a process.
Start with the handoff
Elan’s optimization service offers a method worth borrowing: establish a baseline, compare the program with peers, identify gaps, project the return, choose an action plan and measure progress. A buyer can apply that sequence before changing providers. Start with one recurring problem: an approval delay, an awkward reimbursement, or a reconciliation task that gets rekeyed.
The conditions matter. A supplier must accept the proposed payment method. A shop may not accept a mobile wallet. Accounting connections have to fit the existing system, and somebody must resolve flagged transactions. These are useful questions for a pilot, with actual users and suppliers, before a wider rollout.
A useful trial would count the manual touches per invoice, the time until approval, and the exceptions someone must investigate. Then repeat the count after the change. Those measures put the purchase decision back in the buyer’s hands. A rewards rate can attract attention; a shorter queue of unresolved work can justify adoption.
What makes Elan interesting is how much of its offering surrounds the card: the bank relationship, the spending permission, the supplier conversation and the accounting record. For a finance team, the question is where work gets stuck between those points. Fix that handoff, then measure what changed.