A small-business loan contains a surprisingly large number of opportunities to get stuck. A tax return needs translating into a financial workbook. A borrower has missed a document. Someone needs to check a rule. Each task looks manageable. Together, they form a queue. iBusiness has built a software business around that queue.
- LenderAI brings loan sales, underwriting, closing and servicing into one system.
- Lendsey adds AI agents for document analysis, follow-ups and credit memos.
- Platform0 and iBuild extend the idea: let bank teams shape their own software.
The revealing early example is modest. In November 2023, iBusiness introduced an SBA rules chatbot inside LenderAI Prodigy. Staff could ask about the Small Business Administration’s procedures and receive an answer pointing to the relevant section. The company had already used the tool internally. Experience with that internal version persuaded it to offer the feature to customers.
That sequence matters. The problem came from people doing the work. The software had a bounded assignment, a reference document and an answer a lender could check. Before the ambitious talk of autonomous agents, there was a person trying to find the right paragraph.
A lender’s view of the bottleneck
Founder and CEO Justin Levy’s financing career predates the current AI excitement. He founded Knight Capital Funding in 2013 and launched iBusiness Funding in 2015. Ready Capital acquired both businesses in 2019. The funding operation subsequently acquired Funding Circle US in 2024, adding another lending platform to the group.
The distinction is useful: iBusiness is selling technology informed by a lending operation. Its expertise includes the forms, financial analysis and handoffs that sit between an application and a funded loan. The technology brand now markets to enterprises and smaller businesses as well as financial institutions.
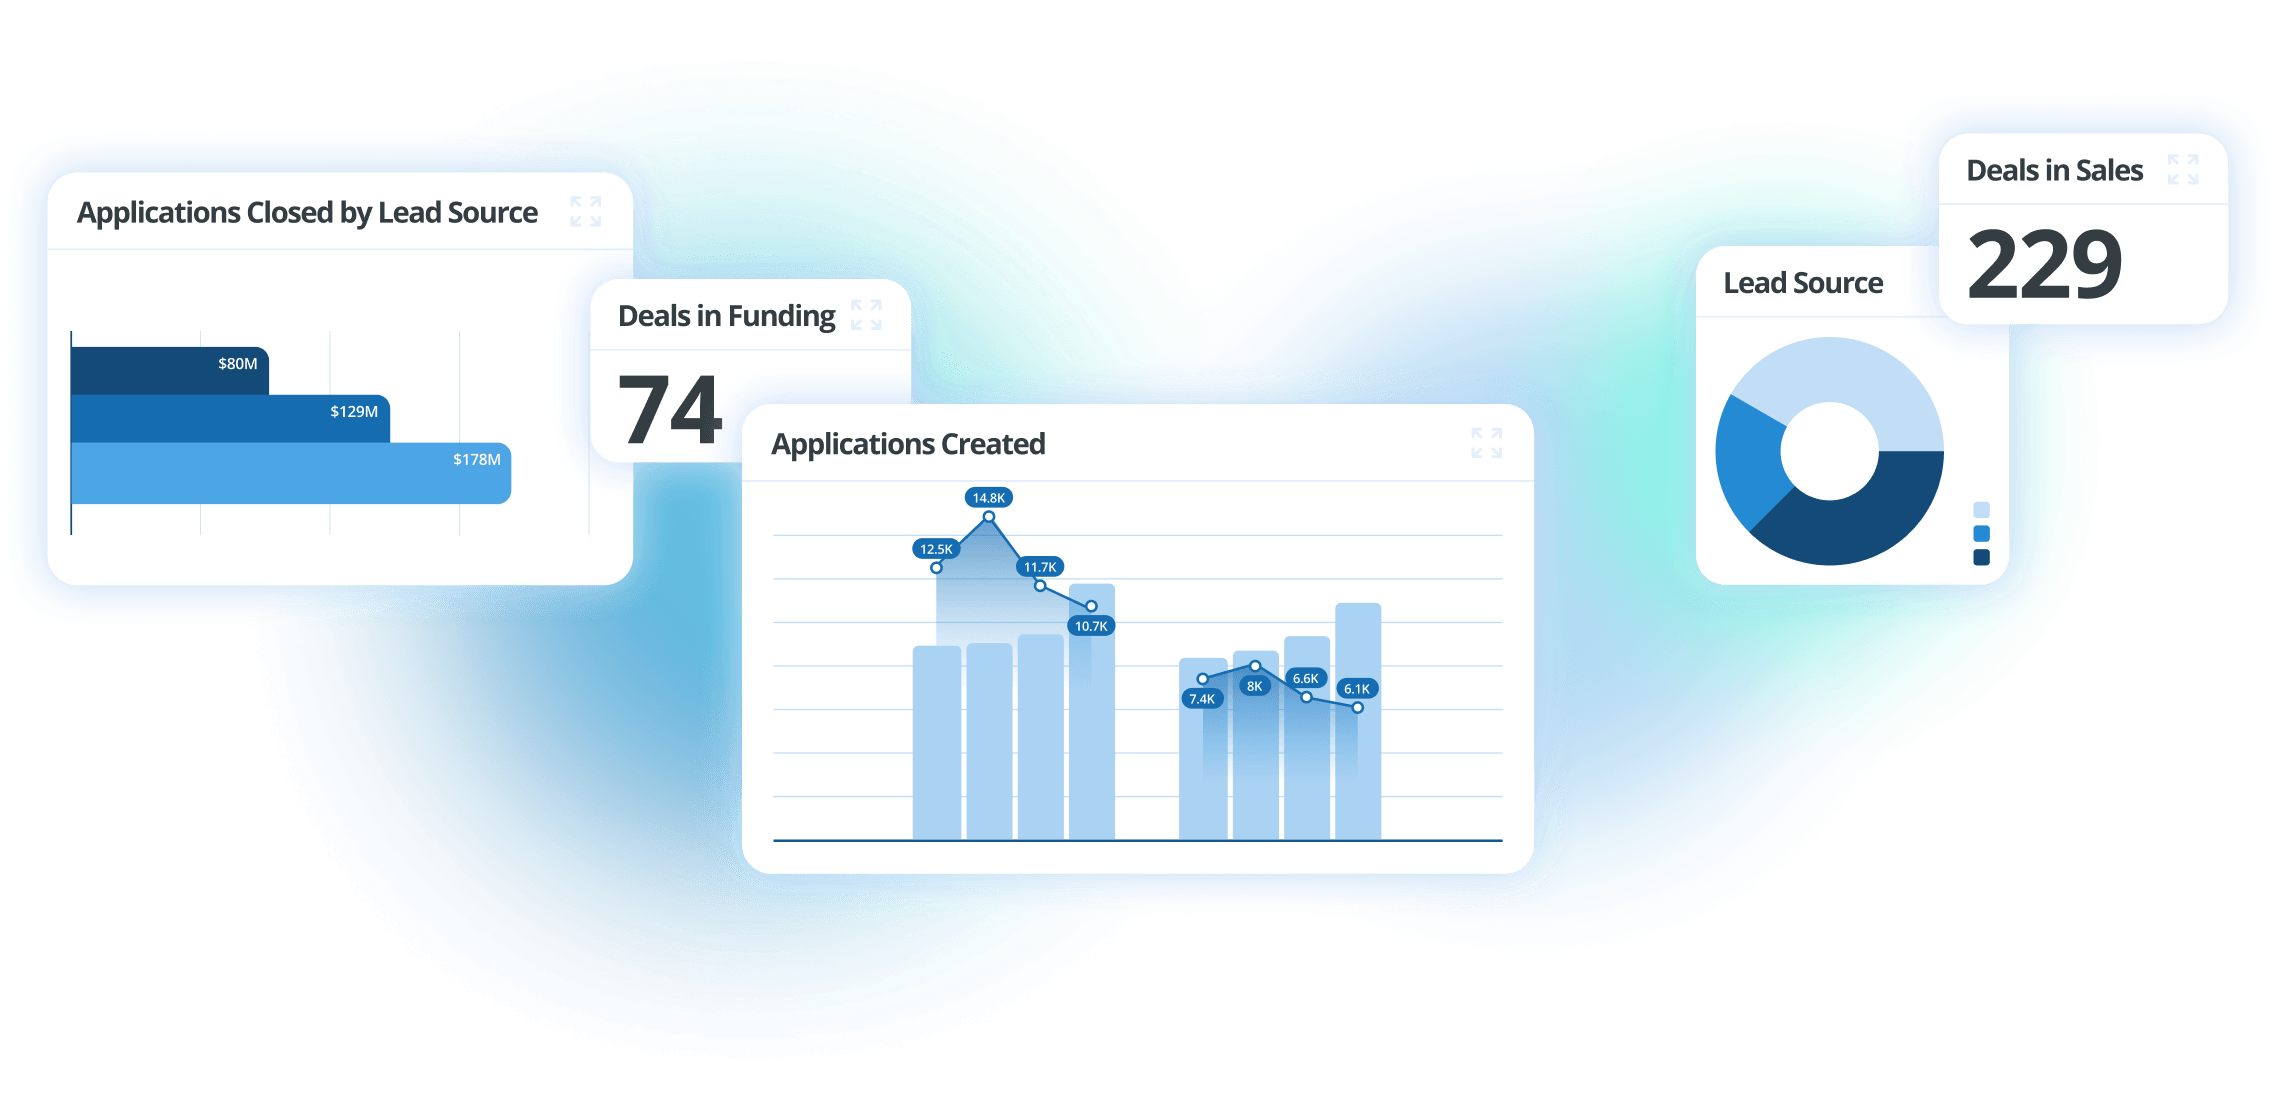
LenderAI’s proposition is consolidation. The product covers borrower intake, underwriting, closing and servicing. It includes financial workbooks, document generation, customer portals and a connection to the SBA’s ETRAN system. Institutions can run it themselves or use Lending as a Service, in which the company’s team operates the process for them.
Give the assistant something to do
In April 2025, iBusiness Funding announced Lendsey, an AI add-on to LenderAI. The interesting distinction is the assistant’s access to work. A statement-reading agent can extract figures, flag irregularities and prepare follow-up questions. A credit-memo agent can assemble a draft for review. Email and task tools let analysis lead to another step in the file.
Illustrative sequence based on advertised Lendsey capabilities. Human review can remain in the process.
The company markets more than 600 agents and offers both fully agentic and human-in-the-loop operation. That count describes its advertised catalogue. It does not establish how much work an institution can safely delegate. Permissions, data access and review points still determine what happens to a particular loan.
Security is central to the pitch. iBusiness says its models use its own lending data rather than training on customers’ data. Its security materials describe isolated customer AI memories, audit trails, encryption and SOC 2 Type II controls. Those are meaningful design commitments; a bank still has to assess its particular deployment.
The customer is buying fewer handoffs
The customer list makes the market easier to understand. Integrity Bank & Trust adopted LenderAI for its SBA program. SBA WORX selected it for the lending-service-provider business, where banks need visibility into files handled by another organization. Business Loan Capital chose it for bridge lending, extending the product beyond its SBA roots.
In February 2026, financing adviser Benetrends announced it would use LenderAI for centralized intake and lender-ready submissions. Its problem begins before a bank makes a credit decision: getting a customer’s information into a consistent, usable package. That is another part of the same queue.
For the bank employee, useful automation may mean fewer requests to re-enter information. For a borrower, it may mean a clearer request for the missing item. These are different experiences of the same underlying problem: a file that has stopped moving. The product’s value depends on connecting those experiences without losing the institution’s control over the decision.
There are established alternatives. nCino also offers SBA workflows and E-Tran submission. iBusiness’s positioning combines lending software, optional operational services and AI tools inside its own environment. Buyers are choosing an operating arrangement as well as a feature list.
iBusiness Funding said the commitment would be financed internally through operating revenue.
That commitment is a spending plan, not a disclosed venture round or a measure of customer savings. For an institution evaluating the software, the relevant calculation is more specific: license and implementation costs, integration work, staff review time and the expense of moving an existing process.
Then the queue reached the developers
iBuild, launched in October 2025, takes aim at another delay: turning an employee’s useful idea into working software. Users describe an application in ordinary language. The platform generates the application and supports testing and deployment. EasyDoc supplies document and signature tools; Ocrio handles document extraction; iCompose provides custom-agent construction.
The June 2026 launch of Platform0 made the wider ambition explicit. It supplies a configurable foundation for workflows and applications, including LenderAI 2.0. Product chief Chris McCay described clients having to compromise their plans because of development backlogs. The proposed change is to let them build and refine what they need.
“Our clients don’t want to conform to a platform; they want a platform that conforms to them.”
Chris McCay, Platform0 launch announcement, June 2026
The boundary between a convincing demonstration and a working system deserves attention. iBuild’s sandbox excludes production integrations, data storage and connections to other iBusiness applications. Enterprise licensing adds production capabilities and integration support. Its own product page also specifies manual review before publishing.
There is a practical lesson here for anyone building automation. Start with a repeatable task, make the answer inspectable, test it with people who know the work, then connect it to the next step. The approach depends on usable data, defined permissions and institutional oversight. A beautiful prototype cannot supply those on its own.
iBusiness’s wager is that banks have accumulated enough software, yet still spend too much time waiting between systems and teams. Its next test is whether giving those teams more control actually shortens that wait.