Fred Ngan understood insurance for a living. Then he needed heart surgery. The medical cover supplied by his employer, a major accounting firm, would not stretch to the operation at a private hospital. He went through the public system instead. The awkward detail is his profession: Ngan was an actuary. If somebody trained to measure risk could misjudge his own protection, what chance did everybody else have?
- Bowtie sells life and health protection directly online, without sales commissions or savings components.
- Its products serve individuals, families and employers, with human help alongside the website.
- The experiment has grown. Its audited accounts show that building an insurer still costs real money.
The policy that fell short
Ngan’s experience helped push him out of consulting and into entrepreneurship. With fellow actuary Michael Chan, he built Coherent Capital Advisors and the insurance comparison platform Seasonalife before Bowtie. Both had studied mathematics at Waterloo. They knew the machinery behind the promise: pricing, capital, risk and the distance between a benefit schedule and an actual hospital bill.
A conversation with an insurance executive supplied another nudge. Why keep working around insurers? Build one. Ngan initially considered the barriers formidable. The idea persisted. In September 2017, the team decided to apply for a virtual-insurer licence. Authorization arrived in December 2018. Their first online VHIS Standard Plan followed in April 2019.
“People don’t look at their plans until something happens.”
Fred Ngan, speaking to Tatler Asia
That is the first failure in this story: existing coverage falling short when somebody needed it. It explains Bowtie’s attention to a deceptively ordinary task. Help people understand what they have bought before the diagnosis arrives.
Delete the commission. Keep the help.
Bowtie’s proposition begins with two removals. There is no sales-agent commission. There is no savings component inside its insurance products. Customers pay for protection, rather than a package combining protection with accumulated value. The website handles quotes, applications, underwriting and claims. Bowtie is the licensed insurer behind the policy, with responsibility for the risk.
This puts it alongside Hong Kong’s established medical and life insurers, including AIA, AXA, Prudential and Manulife, while giving it a different shopping experience. Someone can inspect the product without arranging a sales meeting. Removing distribution expense creates room for a lower price. It does not make every Bowtie policy cheaper than every rival’s equivalent cover.
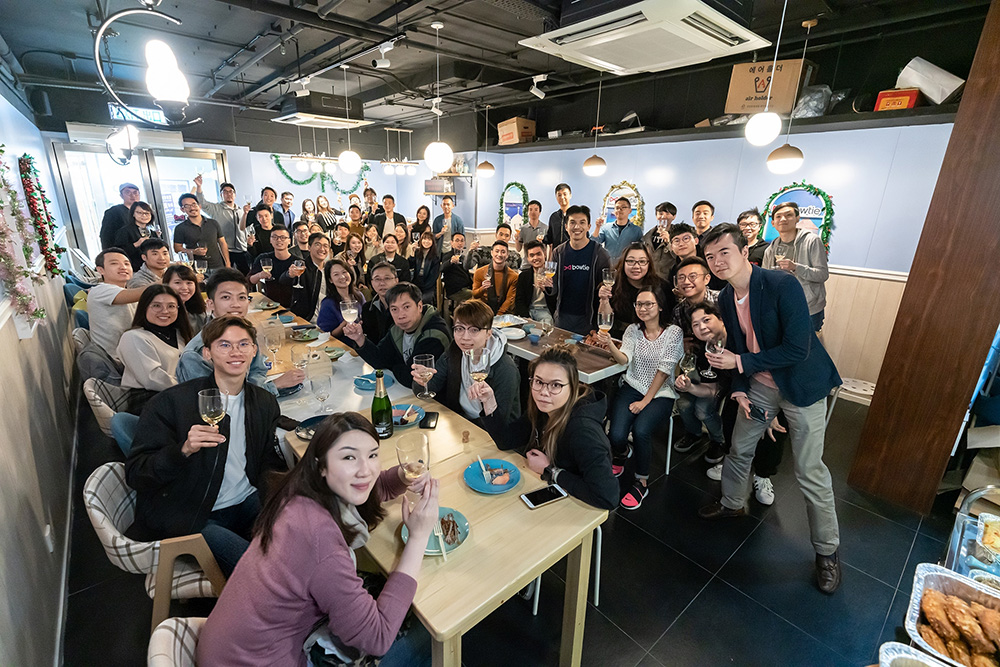
The early operational promise was striking: at launch, a suitable applicant could complete the process in as little as ten minutes. But a quick purchase leaves another question. Who answers when the customer is confused? Bowtie has product specialists, customer-service staff and claims assistance. Its chosen phrase is “Here to help, not to sell.” The distinction lives in the incentives and the service.
The bill still has a first page
The range follows familiar household worries. VHIS Standard and Flexi plans cover eligible medical expenses. Bowtie Pink offers broader medical-plan options. Term life protects beneficiaries; critical illness pays according to qualifying diagnoses. Cancer Fighter concentrates on cancer treatment, while Touch Wood addresses accidents. Employers can buy group medical benefits. The company’s group page reports more than 500 corporate customers.
Pink makes the price-versus-risk decision unusually visible. Customers can select deductibles of HK$0, HK$20,000, HK$50,000 or HK$80,000. A higher deductible can reduce the premium, while leaving the customer responsible for more of the eligible bill. Employer cover may help with that first portion, but it can disappear when employment ends. The useful question is how much you could pay yourself.
Available deductible options. Benefits remain subject to the policy’s terms and limits.
StillCover, introduced in April 2026, approaches a different gap: people with stable chronic conditions, including diabetes, who may struggle to obtain conventional medical insurance. It supplements public-hospital care and designated services. The product page retains individual underwriting, possible medical-report requests and case-based exclusions. A friendlier doorway still needs an eligibility test.
Nor does submitting a claim online abolish evidence. Medical forms, receipts and relevant reports remain part of the process. Cashless arrangements require approval and do not guarantee final payment. Bowtie’s convenience matters most when it helps people navigate those obligations rather than overlook them.
A virtual company goes outside
There is a pleasing wrinkle in Bowtie’s development. The insurer that moved buying online also developed physical touchpoints. Its Bowtie & JP Health venture offers primary and preventive care. Partnerships with Gleneagles Hospital and CUHK Medical Centre connect VHIS riders with wellness services. BowtieGo provides outpatient access through a health membership, distinct from insurance.
The logic is practical. Customers can use a health service before they have a major claim. A clinic makes the relationship tangible. Ngan told Tatler that physical touchpoints mattered because insurance depends on trust. By 2026, Bowtie also had its name on a Wan Chai tower. The browser is one part of the relationship.
Growth has a price tag
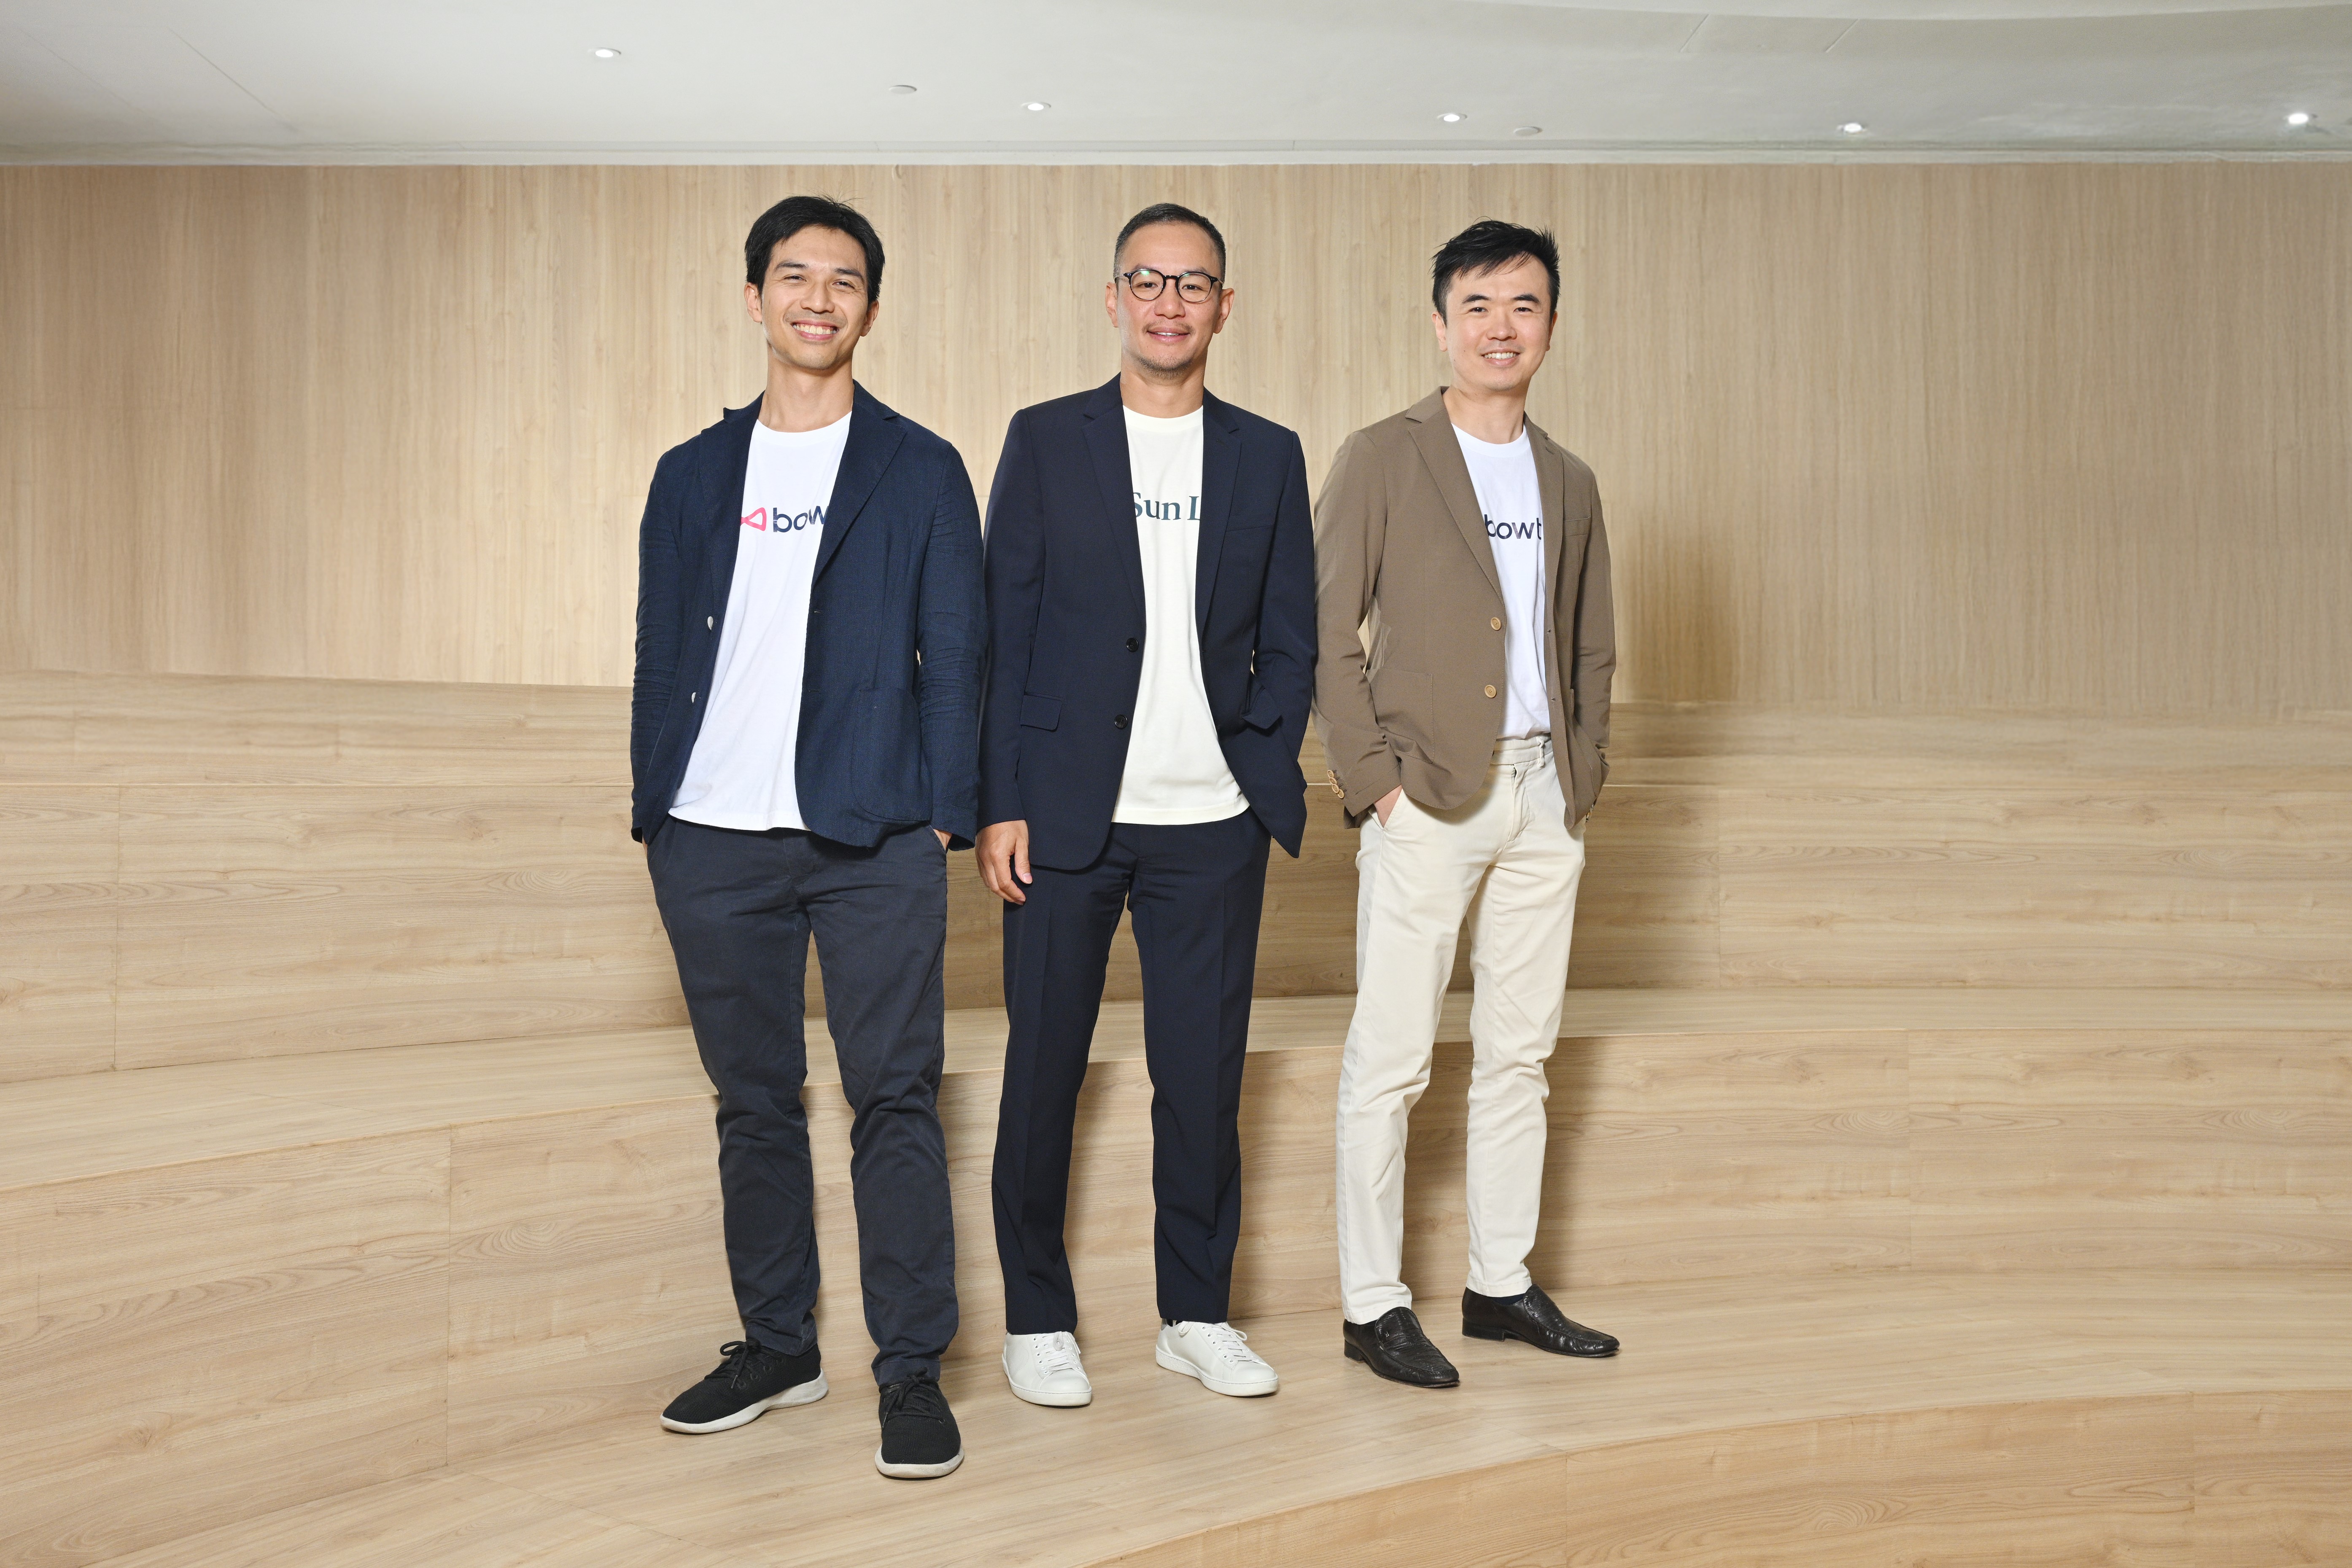
Bowtie announced US$30 million in Series A funding, US$22.6 million in Series B1 and US$34.9 million in Series B2. In July 2025 came a Series C announcement of up to US$70 million led by Sun Life. The subsequent audited report describes Bowtie becoming a Sun Life subsidiary undertaking. Insurance needs capital behind the interface.
HKFRS 17 insurance revenue. This is different from annual recurring revenue.
Its 2025 accounts record HK$511.8 million in insurance revenue and a HK$150.4 million loss attributable to shareholders. July 2026 disclosures report more than 150,000 customers and annual recurring revenue exceeding US$100 million. Those figures measure different things. Growth, a recurring premium base and profitability deserve separate sentences.
What can another business copy? Publish the price. Explain the purchase. Remove a cost customers resent, then invest in the help they still need. For an insurance buyer, the transferable lesson is narrower: compare the actual benefits, deductibles and exclusions before comparing premiums. Bowtie suits people comfortable buying protection directly. Somebody seeking savings inside a policy, or coverage outside its underwriting and network rules, needs a different fit.
Ngan’s original surprise was that having insurance and having enough insurance were different conditions. Bowtie’s most useful contribution is making that difference easier to examine while there is still time to choose.