The strange thing about employer health insurance is how much everyone resents it and how alarming it feels to change it. A chief financial officer sees premiums jumping again. Human resources sees a calendar full of enrollment meetings. Employees see the pediatrician who finally knows their child’s history and wonder whether that doctor will vanish behind an out-of-network wall. Remodel Health lives in that gap between “the old plan is unsustainable” and “please do not make this worse.”
The Indianapolis company is neither a carrier nor a health plan. It administers individual coverage health reimbursement arrangements, the alphabet soup known as ICHRA. An employer chooses a tax-free monthly contribution. Employees take that allowance into the individual insurance market and choose their own qualifying plans. Remodel Health supplies the benefit design, shopping software, enrollment, compliance work, payroll connections, reimbursements, premium payments and licensed advisers.
The promise is appealingly blunt. The employer gains a budget it can predict instead of absorbing whatever increase lands at renewal. The worker gains more options than the one or two plans usually parked in a group-benefits portal. Then comes the catch: choice is work. Networks, drug formularies, deductibles and household needs do not line themselves up because a dashboard has cheerful buttons.
01 / The actual product
A benefits switch with people hiding inside the software
Remodel Health’s flagship, ICHRA+, is aimed at employers that want more control and service than a lightweight reimbursement tool provides. Its software recommends and compares plans, records elections, supports reporting and connects benefit data to payroll. Behind it sit advisers who can discuss doctors and prescriptions, specialists who handle Medicare questions, account managers who review strategy, and an operations team that watches carrier payments.
That last room is less glamorous and more important than it looks. A missed task in ordinary business software produces a reminder. A missed premium can produce a coverage lapse. Remodel Health says its AutoPay operation clears 99 percent accuracy and routes employer-funded money to carriers while a team handles exceptions. Integrations with UKG and Paylocity, plus connections to more than 200 payroll and HR systems, remove the ritual of copying employee changes between databases.
In August 2026, the company put a name on the human layer: ClearChoice. It covers the path from implementation to renewal, including employee education, licensed advocacy, compliance guidance and payment operations. ClearChoice is included with the flagship ICHRA product. Certain on-site enrollment support is included for enterprise groups with at least 250 lives. It is a clever positioning move because every rival can say “white glove”; fewer publish a 96 percent adviser-satisfaction figure, 95 percent annual retention and payment accuracy above 99 percent.
“Technology should scale human empathy, not replace it.”Remodel Health’s operating idea
02 / How it got here
The first failure was the old group-plan math
Scott Lingle and Justin Clements founded Remodel Health in 2015, when the Affordable Care Act had redrawn the individual market and plenty of organizations still faced group-plan costs they could not comfortably absorb. The company’s early wedge was practical: give brokers the quoting technology to move employers toward individual insurance. Crossroads Church of Avon and Eckhart & Company became early customers in 2016.
The earliest proof came from churches, where a premium increase competes directly with salaries and programs. In 2017, Remodel Health and GuideCare threw a party to mark $1 million in annual savings returned to Indiana churches and ministries. GuideCare was its top-performing broker partner. Remodel Health acquired it, and GuideCare founder Austin Lehman became CEO. What changed minds was not a lecture about market design. It was money that could be pointed to, followed by a team willing to manage the frightening transition.
The federal ICHRA rules took effect in 2020, turning an early thesis into a defined category. Remodel Health says it added more than 2,500 customers in 2021, crossed 90 percent retention in 2022 and surpassed $100 million in cumulative customer savings in 2023. Its case studies include a church projected to save more than $1 million over six years and an 81-employee oil-change business projected to save more than $3 million over the same period. Those are company-selected examples, not universal returns, but they show exactly how Remodel Health sells: put the ugly renewal curve next to a fixed contribution.
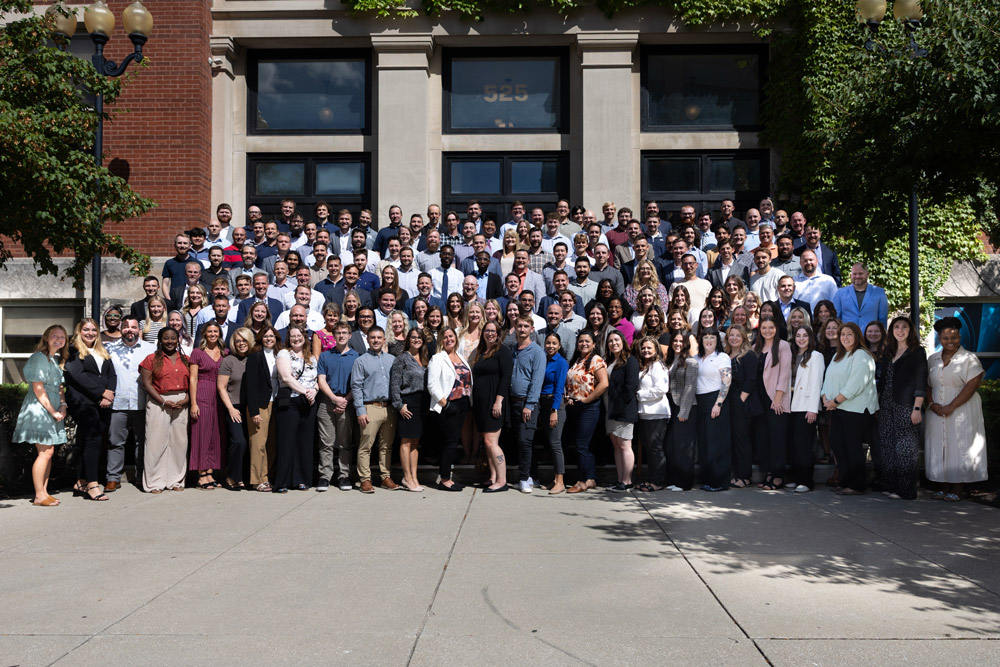
In February 2024 it acquired PeopleKeep, an older HRA administration business with products for small employers. That gave Remodel Health two lanes: high-service ICHRA+ for larger and more complex organizations, and PeopleKeep for smaller ones. Ten months later, Oak HC/FT led a growth investment of more than $100 million. The company passed 200 employees in 2025 and, in August 2026, appeared on the Inc. 5000 for a seventh consecutive year.
03 / The trade
Predictability for the boss, responsibility for the worker
The relevant cost is not only Remodel Health’s administration fee, which is sold by contract. It is the contribution the employer chooses to provide. In healthcare organizations using Remodel Health, the company reported an average 2025 self-only contribution of $579 a month. Employers may vary allowances within federal rules by age, family status and employee class. Unlike a traditional plan renewal, the ceiling is designed up front.
What improves
A fixed employer budget; employee choice; coverage that can be retained after leaving a job if the worker pays; less exposure to one group’s claims experience.
What gets harder
Employees must shop; individual plans can have narrower networks; market quality differs by location; a favorite doctor or medication can shrink the useful options fast.
This is where the model can fail. It is a poor fit when the local individual market has weak carrier competition, when key physicians sit outside available networks, or when employees have complex care and no trusted help comparing plans. A workforce that values one broad national network may experience “choice” as a downgrade. Employees also cannot keep an Affordable Care Act premium subsidy while participating in an employer ICHRA. The arrangement needs careful affordability calculations, clear communication and enough contribution to make the available plans credible.
That limitation explains Remodel Health’s differentiation. Take Command, Venteur, Thatch and other administrators compete in the same expanding category; traditional brokers, PEOs and group plans remain the default alternative. Software features converge quickly. Remodel Health instead emphasizes operational density: licensed support staff, direct carrier payments, dedicated launch coordinators, compliance expertise and the ability to sit between broker, employer, payroll system and employee without dropping the baton.
Its place in the market is therefore somewhere between benefits SaaS, insurance brokerage and outsourced administration. The buyer may be a broker protecting a client relationship, a school trying to preserve classroom dollars, a healthcare organization hiring clinical staff or a private-equity operator standardizing benefits across a portfolio. The end user is still the employee staring at plan names. Remodel Health has to satisfy both levels at once: show the organization a financially defensible design, then make that design usable household by household. PeopleKeep extends the same defined-contribution idea to small companies, while ICHRA+ and ClearChoice carry the heavier implementation and service load for larger employers.
04 / The stealable playbook
Do not automate the moment that scares the customer
There is a useful company-building lesson here even if “reimbursement arrangement” is not written on your vision board. Remodel Health automated comparison, reporting and data movement, then kept humans at the points where anxiety and consequence peak. It turned service from a vague adjective into a product with a name and metrics. It expanded distribution through brokers rather than trying to erase them. And it integrated with payroll systems customers already trusted instead of asking HR to maintain another island.
Five moves worth borrowing
- Sell the transition, not merely the destination.
- Give every stakeholder a separate win: finance gets control, HR gets fewer chores, brokers keep relevance, employees get guidance.
- Measure the unglamorous promise - retention, payment accuracy and response quality.
- Acquire a second product when serving a smaller segment would distort the flagship.
- Put a person beside every irreversible or expensive decision.
The company still depends on a market it does not control. If individual premiums surge, networks narrow or regulation changes, good administration cannot rescue bad underlying options. ICHRA also remains small beside the roughly 154 million Americans covered through work. Remodel Health’s bet is that rising group costs will push more employers across the line - and that the administrator trusted to handle the awkward first year can keep them for the next ten.
That makes Remodel Health less a flashy insurtech story than an infrastructure story. Its job is to make an unfamiliar system feel boring enough to renew: the right contribution on the payroll file, the right plan on the screen, the right premium at the carrier, and a real person when the answer cannot be reduced to a tooltip. In American healthcare, boring is not faint praise. It is frequently the product.