A phone is a modest place to begin an automobile business. It fits in a pocket, needs no parking space and can survive a disappointing launch without anyone building a service garage. Yet Xiaomi has followed its customers from the handset to the driveway. In 2025, the company delivered 411,082 electric vehicles. The maker associated with affordable Android phones now has a substantial car business attached to it.
That expansion gives Xiaomi its most interesting commercial argument: win a place in someone’s daily routine, then sell useful things for the rest of it. A phone leads to earbuds, a fitness band, a television or a robot vacuum. Software helps keep them in conversation. In China, the same ambition now extends to a sedan and an SUV. Xiaomi calls the arrangement “Human × Car × Home.” The multiplication signs are doing considerable work.
There is a timely complication. After revenue reached RMB457.3 billion in 2025, the first half of 2026 brought an 8.4% decline in sales and a 42.8% fall in adjusted net profit. Xiaomi attributed pressure to factors including rising component costs and intense competition. More connected gadgets do not automatically produce better economics. That tension makes this a company worth studying beyond its launch spectacles.
The software arrived before the phone
Lei Jun and his co-founders established Xiaomi in 2010. Lei already had a career in software; fellow co-founder Lin Bin brought experience at Microsoft and Google. The sequence of their first releases mattered. MIUI, Xiaomi’s Android-based software interface, appeared in 2010. The Mi 1 smartphone followed in 2011. The company could develop a relationship with enthusiasts before asking them to buy its own hardware.
Those enthusiasts became Mi Fans, a community the company described in its listing documents as contributors of feedback and feature ideas. The useful lesson is specific: let people participate in improving something they actually use. An audience assembled around a working product can tell a business more than an audience assembled around a launch countdown.
Xiaomi’s stated culture still puts users near the center. Its vision is to “Make friends with users and be the coolest company in the users’ hearts.” That is unusually conversational corporate language. It is also the company’s description of its aspirations, rather than independent proof of what every employee or customer experiences.
A low price, with an important footnote
Xiaomi sells smartphones under Xiaomi, REDMI and POCO, alongside tablets, wearables, televisions, appliances and other connected hardware. Customers range from shoppers stretching a phone budget to photography enthusiasts buying flagship models. Its internet services include advertising and gaming. The business therefore earns money both when equipment changes hands and through activity on its software platforms.
In 2018, it made a conspicuous promise: the overall annual net profit margin of its hardware business would not exceed 5%, with any excess returned to users. The original pledge covered smartphones and IoT and lifestyle products. It did not mean that each phone carried a 5% markup. Nor should readers treat it as a universal ceiling on group profitability or assume that its original scope automatically covers cars.
“Be friends with our users.”
Xiaomi’s vision, as stated in its 2018 listing documents
The distinction matters because gross margin, net margin and the price of an individual product answer different questions. Development, marketing and administration cost money after a device leaves the factory. Xiaomi’s pledge expressed a philosophy about the hardware business after relevant costs, rather than a formula shoppers could apply to a bill of materials.
Against Apple, Samsung, OPPO and vivo, Xiaomi competes with a combination of specifications, price, distribution and the breadth of its connected products. There is no single comparison that settles every purchase. A budget REDMI and a Leica-equipped Xiaomi flagship serve different priorities. Treating the entire range as “cheap phones” misses the company’s deliberate pursuit of more expensive models.
Then the internet ran out of shopfronts
The early sales formula had a limit. Online distribution helped Xiaomi reach buyers economically, but rivals could copy it. By 2016, its position in China’s smartphone rankings had deteriorated. Supply-chain problems added pressure. The company that had made online selling part of its identity needed to become easier to find in the physical world.
In January 2017, Reuters reported Lei’s explanation that e-commerce represented only about 20% of China’s smartphone market. He outlined plans for 200 additional Mi Home stores that year. Xiaomi’s listing documents show the subsequent change: its mainland China Mi Home count rose from 51 at the end of 2016 to 331 by March 2018.
*March 2018. Mainland China Mi Home stores.
This was a change in operating method with real consequences. Stores require space, people and inventory. They also allow a shopper to handle a phone and discover several other products during the same visit. A broad catalogue makes more sense when it helps the economics of a shop, rather than merely giving the marketing department a longer list.
For another business, the copyable move is to revisit distribution when growth stalls. Xiaomi’s experience suggests asking which customers a favored channel excludes. It does not establish that every online brand should sign leases. Physical retail needs sufficient demand, product variety and execution to pay for the additional costs.
Leica brings the camera. Qualcomm brings the chips.
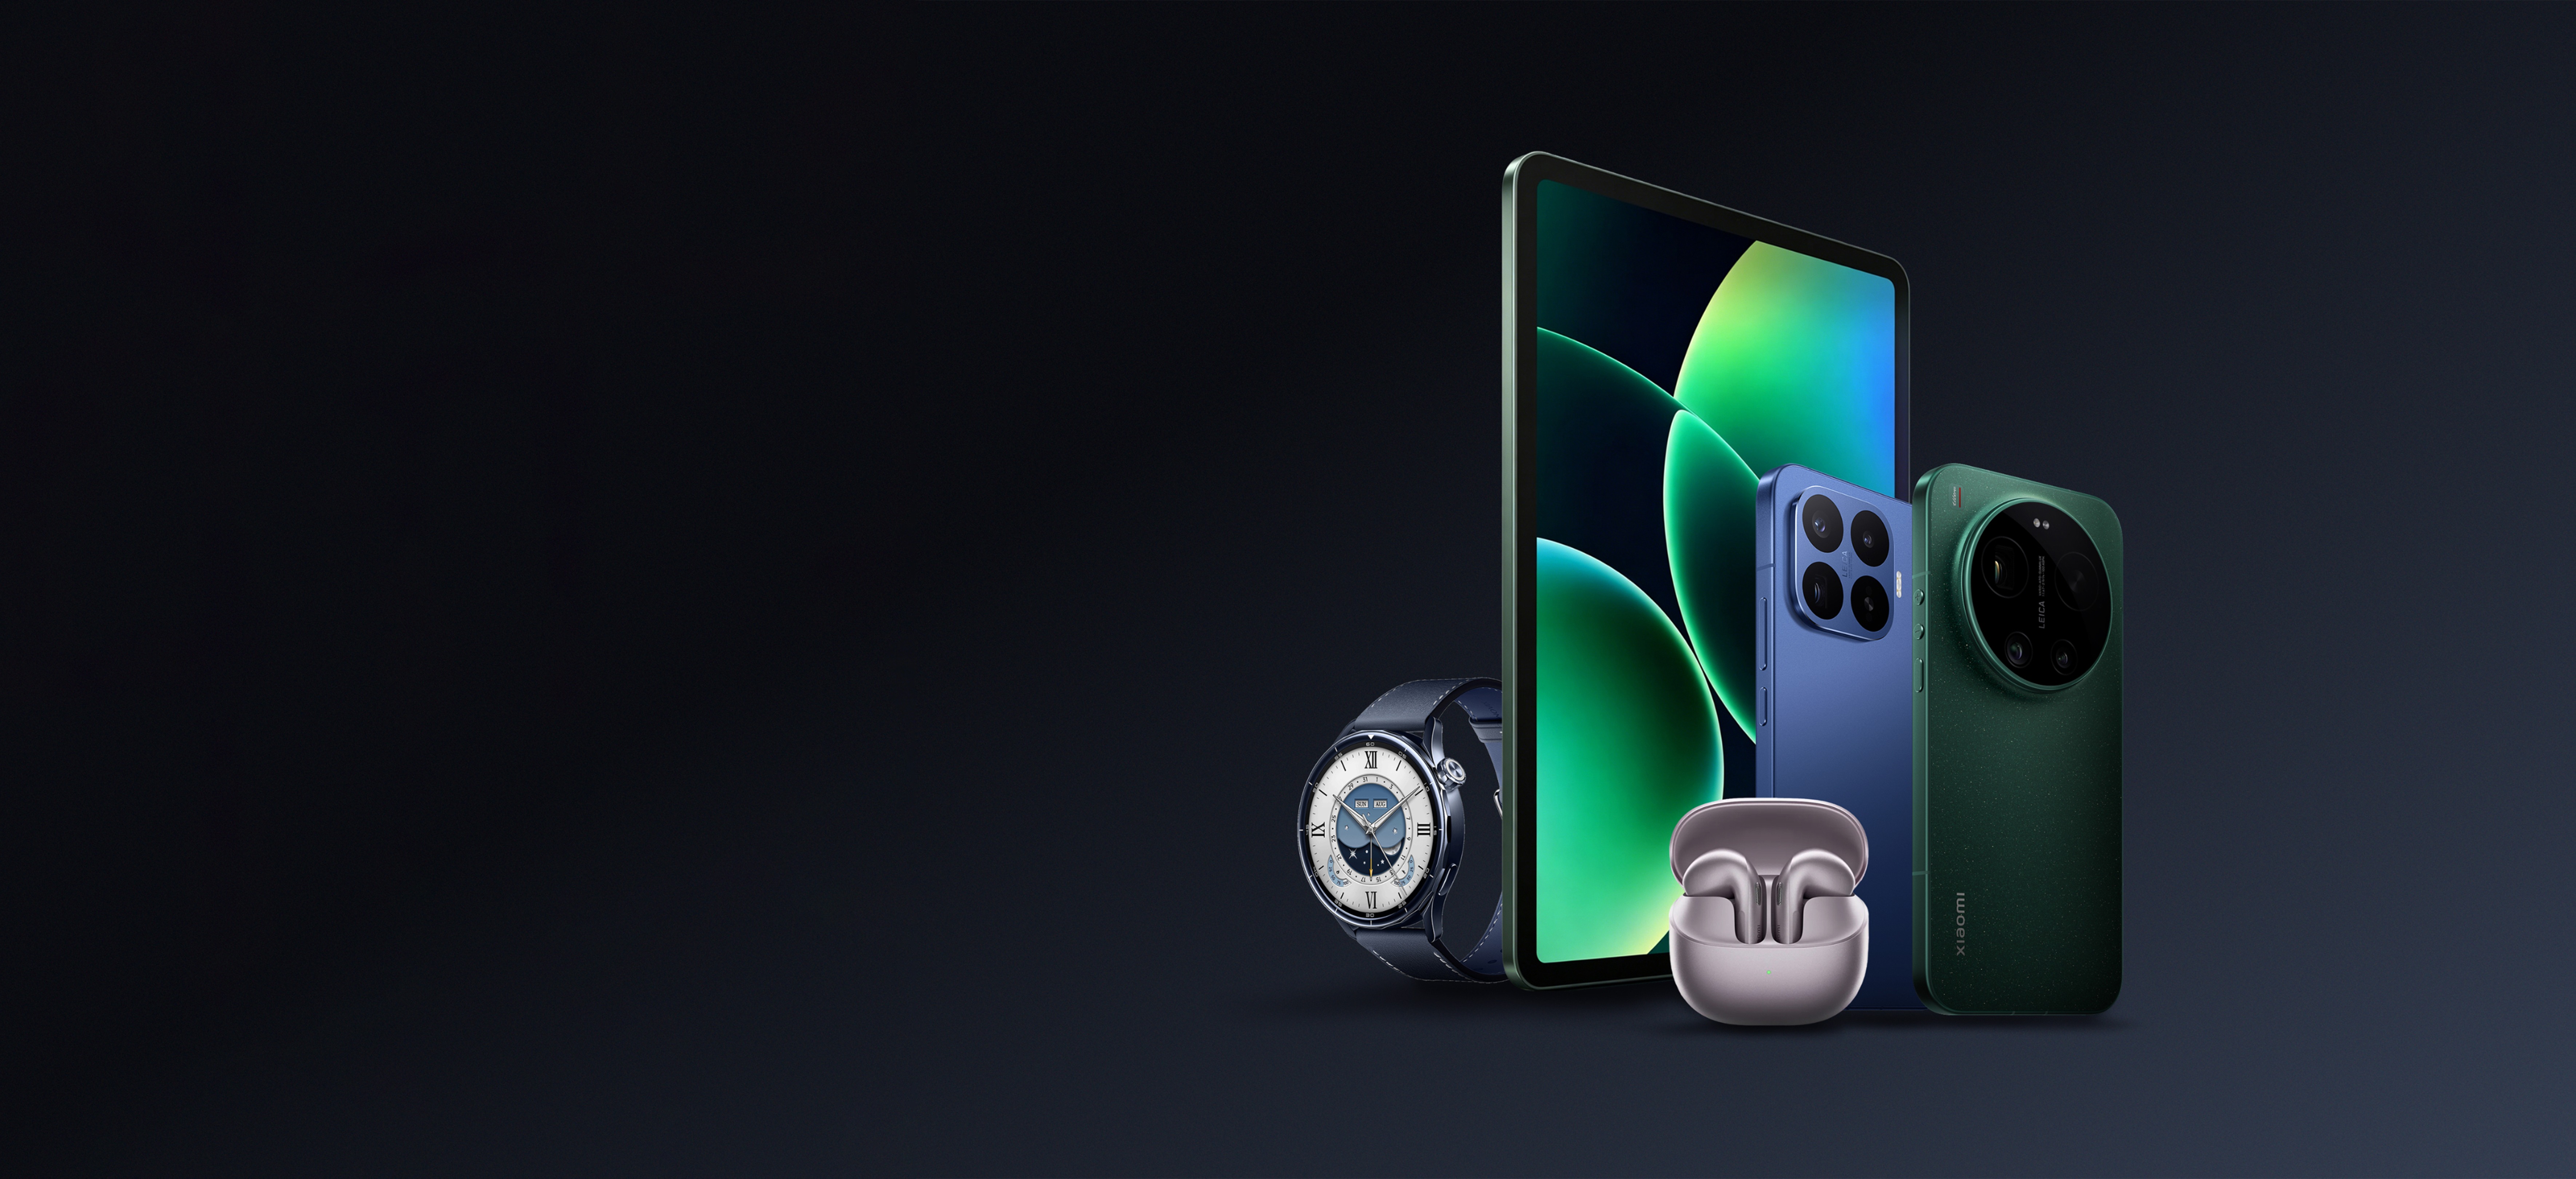
Xiaomi’s capabilities extend across industrial design, software, connected-device integration, sourcing and manufacturing. Partnerships fill important parts of that picture. Leica announced its strategic imaging relationship with Xiaomi in May 2022; the jointly developed Xiaomi 12S range followed that July. Leica contributed to camera-module development, bringing specialist imaging knowledge to a phone maker seeking more credibility at the expensive end.
Qualcomm’s relationship runs deeper into the machinery. In May 2025, the companies extended their collaboration through a multiyear agreement covering Snapdragon 8-series platforms for premium phones. Qualcomm also supplies technology for the SU7’s smart cabin. The same partner can therefore appear in both the object in a customer’s hand and the electronics inside the car.
Xiaomi is also developing more technology internally. Its XRING O1 chip, launched in 2025, uses Arm technology. Designing a chip and buying processors from Qualcomm can coexist; independence is rarely an all-or-nothing condition in electronics. The sensible question is which capabilities Xiaomi needs to control and which are better obtained from specialists.
The next accessory needed a factory
Cars changed the size of the bet. When Xiaomi announced its EV entry in March 2021, it specified an initial RMB10 billion investment and an estimated US$10 billion commitment over ten years. These were investment plans, not a statement that the full dollar amount had already been spent. Lei took responsibility for the new business himself.
The SU7 went on sale in China in March 2024 at an introductory starting price of RMB215,900. Its launch was unmistakably a technology event, complete with an extended presentation and orders through an app. But behind the familiar launch format sat unfamiliar obligations: production capacity, repairs, vehicle quality and the consequences of faults on a public road.
The YU7 SUV followed in 2025. That year, the segment Xiaomi calls smart EV, AI and other new initiatives generated RMB106.1 billion of revenue and recorded its first positive full-year operating income, RMB0.9 billion. The segment’s name matters: those figures should not be presented as a pure car division’s standalone results.
Success also brought a sharper test of trust. In September 2025, Reuters reported a recall affecting 116,887 SU7 sedans, involving a software remedy for insufficient warnings under highway assisted driving. A community’s affection cannot substitute for safety engineering. Moving into cars changes what a product failure means, however familiar the dashboard software feels.
A billion devices is not a billion people
The scale is considerable, but its units need care. In June 2026, Xiaomi reported 766.5 million global monthly active users across smartphones and tablets. Its connected IoT count was 1.1608 billion devices, excluding smartphones and tablets under the quarterly report’s definition. One household can own several of those devices; adding the figures together would produce a meaningless customer total.
June 2026
June 2026
For users, the attraction is practical. Xiaomi Home manages compatible smart-home products on Android and iOS, so buying a Xiaomi phone is not a prerequisite for every home-device purchase. HyperOS supplies the broader software framework, with supported features for sharing content and connecting devices. The useful result is fewer separate controls for everyday tasks.
Compatibility still deserves a check before checkout. Xiaomi’s feature documentation specifies supported models, software versions and other requirements; some interactions need matching accounts and enabled connectivity settings. Product availability also varies by market. A demonstration in China is not a promise that every feature or appliance is available to a buyer in Hyderabad.
The cost of keeping the bargain
The financial history shows how much funding and patience this expansion required. Xiaomi raised US$1.1 billion in December 2014 at a reported US$45 billion valuation, with investors including All-Stars Investment, DST Global and GIC. Its 2018 Hong Kong listing raised roughly US$4.7 billion. Those historical valuations are milestones, not current price tags.
Today, the challenge is sustaining the proposition as inputs become dearer and rivals press harder. First-half 2026 adjusted net profit fell faster than revenue. That is a warning against assuming that scale alone protects a company committed to value. Xiaomi must fund engineering, support its expanding range and persuade customers that its more expensive products deserve their prices.
The useful lesson is smaller than Xiaomi’s catalogue. Start with a product people have a reason to use repeatedly. Give their feedback somewhere to go. Add adjacent products that solve recognizable problems, and change the sales channel when customers require it. Xiaomi’s history also supplies the qualification: each new category introduces costs and responsibilities that a familiar logo cannot erase. The driveway makes that particularly clear.