Marc Brownstein went into Stage 2 Capital’s Catalyst program with a company to grow. He came away with a reason to reconsider the timetable. Lively, the business he co-founded, lacked the product-market fit needed to scale, he recalled in a testimonial. The useful discovery arrived before the bigger hiring plan. In venture capital, where speed gets plenty of applause, that is an interesting thing to sell.
- Stage 2 backs B2B software and AI companies from pre-seed through Series A.
- Each investment gets a venture investor and a go-to-market operator.
- Its framework puts customer success and acquisition economics ahead of faster hiring.
Stage 2 supplies money and people who know the awkward middle of building a software company: setting prices, hiring the first seller, finding a repeatable source of customers. Its current investment range is $200,000 to $5 million. Its distinguishing bet is that revenue expertise belongs inside the investment team, close enough to question the plan before the cash is spent.
The investor who took sales classes
Jay Po had been an investor at Bessemer Venture Partners. Founders kept asking how to scale. He responded with an unusual extracurricular activity: taking sales-development classes on nights and weekends. Here was a financier studying the work behind the forecast. A spreadsheet could describe growth beautifully while leaving its production rather mysterious.
Mark Roberge supplied the other half. HubSpot’s fourth employee and founding chief revenue officer, he had built a revenue organization before joining the Harvard Business School faculty. Po and Roberge co-founded Stage 2 in 2018. Together, they became its original investment pod: one person steeped in venture investing, the other in getting customers to buy and stay.
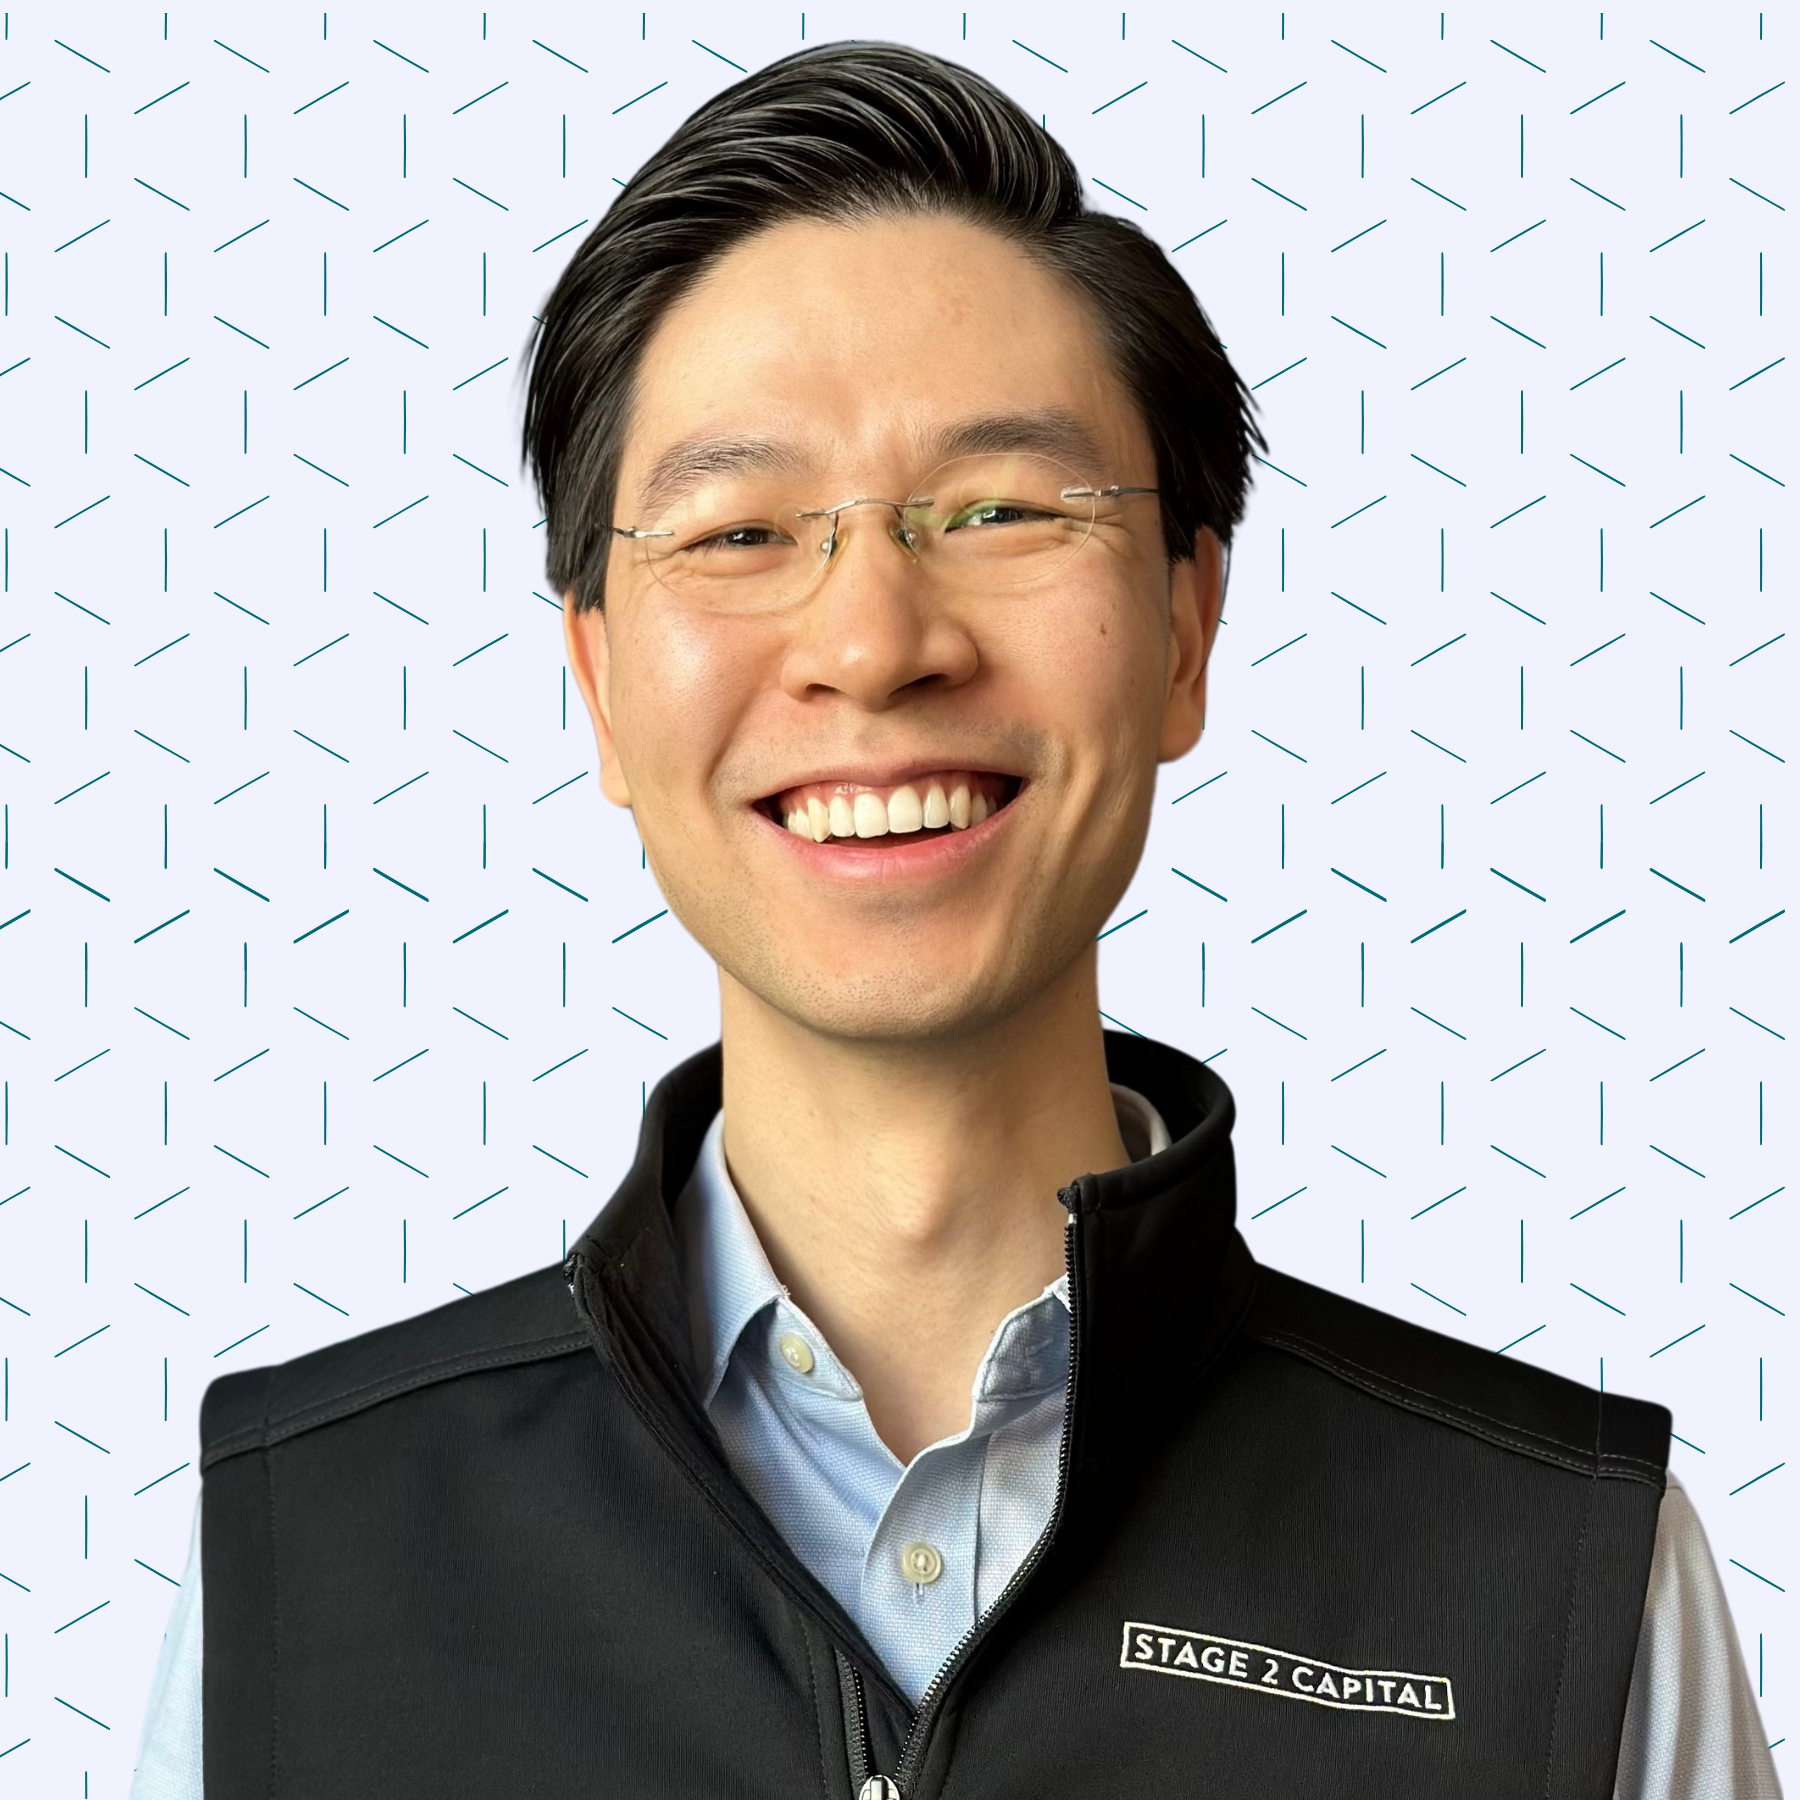 JAY PO / INVESTING
 MARK ROBERGE / OPERATING
That pairing became the firm’s operating design. Every deal has an investor and an operator. After investment, a go-to-market review produces observations and recommendations. Founders can then draw on operator limited partners for introductions, hiring advice, pricing discussions, and customer-success work. The people supplying fund capital can also help diagnose why a sales process is wobbling.
Put customer value ahead of headcount
Roberge’s Science of Scaling framework separates three tasks: establish product-market fit, establish go-to-market fit, then pursue growth and a defensible advantage. The sequence matters. A company can close contracts before it reliably delivers value. It can deliver value before it knows how to acquire customers economically. Hiring more sellers at either point multiplies the unresolved problem.
Retention is useful evidence, but annual renewals take a year to observe. The framework therefore asks founders to identify an earlier customer behavior that predicts staying. Choose an observable event, a time window, and a target share of customers reaching it. Track successive customer cohorts. Crucially, the event must connect to customer value; a signed contract alone will not do.
This explains the significance of Brownstein’s account. The program changed his assessment of readiness. Lively experimented with its product and sales playbook and used the lessons to inform hiring, according to his testimonial. That is a founder’s account of a useful correction, rather than a controlled demonstration that the method causes growth.
“we didn’t have the product-market fit that we needed to scale”
Marc Brownstein, co-founder of Lively
What a $200,000 check commits you to
Catalyst packages instruction and coaching alongside investment. Its published 2024 offer was $200,000 through a SAFE at the previous round’s valuation, with a maximum $15 million post-money cap. The virtual curriculum covered first hires, compensation, pricing, demand generation, and the sales playbook. Those are historical terms, useful for understanding the offer rather than pricing a future cohort.
The cost is an ownership trade-off. A SAFE can convert into equity; it is consequential even when there is no tuition invoice. Founders also commit attention to applying the lessons. Stage 2’s central business is venture investing, with limited partners supplying capital to back private companies. Its first three flagship funds totaled $245 million in announced commitments. That figure measures investment capital, not the firm’s revenue.
A network with a customer inside
Momentum shows how the operator network can work. Stage 2 heard about the customer-intelligence company through Kyle Norton, a limited partner who was already a customer and advisor. The firm co-led its Series A in 2024. In its later account, Stage 2 described advisors helping with customer success, operations, marketing, feedback, and introductions.
By February 2026, Momentum had signed an agreement to be acquired by Salesforce. The example makes the network tangible: an operator brought firsthand product experience into the investment process, and other operators helped afterward. It does not reveal Stage 2’s financial return. In August 2026, the firm announced another investment, joining Axle’s $17.5 million Series A for insurance-verification infrastructure.
The spreadsheet you can steal
A founder can borrow the method without receiving a check. Define an early customer-success event. Test whether it predicts retention. Separate customer segments so a healthy average cannot conceal an expensive failure. Increase hiring in increments while watching whether newer customers still succeed and acquisition economics hold. Put that evidence into the board discussion before approving the next expansion.
The method needs judgment. An easily measured event can be a poor predictor. Advice needs a founder willing to act and an advisor who understands the business. A company without a useful product cannot coach its way around that gap. Against generalist funds and broad accelerators, Stage 2 offers a specific concentration of revenue experience. Its practical challenge to founders is equally specific: show what is working well enough to repeat.
That question travels beyond a fundraising conversation. A sales leader can use it to challenge a headcount target; a customer-success team can use it to ask which buyers thrive. The framework gives those teams a common decision to work on, with a measurable consequence: spend more when the customer evidence supports it.