Forty investors asking questions at once sounds like a pleasant problem. For a founder, it can become an administrative siege. Thuria Wenbar, founder of healthcare company Evaro, describes that situation in a testimonial for Mountside Ventures: investors needed answers, financial information needed organising, and somebody had to take responsibility for the data room. Mountside embedded itself in the financial and data teams. The useful detail is the work it took off the founder’s desk.
- For founders: free early-stage fundraising training, then bespoke advice for larger raises.
- For fund managers: a free programme covering the business of raising a VC fund.
- For readers: prepare the documents before you start collecting introductions.
The spreadsheet before the handshake
Mountside’s commercial offering is an interim CFO and fundraising service for post-revenue companies seeking more than £2 million. Its published process begins with the pitch deck, investor questions, financial model and data room. It then tests the proposition from an investor’s perspective, maps suitable sources of capital, makes introductions, helps negotiate and supports due diligence. The handshake arrives after quite a lot of homework.
That sequence explains where the firm fits. A founder can assemble a deck and approach funds alone, hire a fractional CFO, or bring in a fundraising adviser. Mountside combines financial preparation with the management of the raise. Its public client list includes Transreport, SEND, Springpod and Sifted. The offering also covers debt, so the conversation need not end with selling another slice of the company.
- 01Prepare
- 02Challenge
- 03Map
- 04Introduce
- 05Negotiate
- 06Diligence
Documents first. Conversations next. Execution all the way through.
Three accountants leave the building
The founders’ expertise makes this emphasis less surprising. Jonathan Hollis, Alex Reed and Jon Steinberg are chartered accountants. Hollis and Reed helped build PwC’s early-stage startup propositions; Reed also worked on their expansion into Europe. Their training supplied an appreciation for the part of fundraising that remains stubbornly unglamorous: making numbers withstand scrutiny.
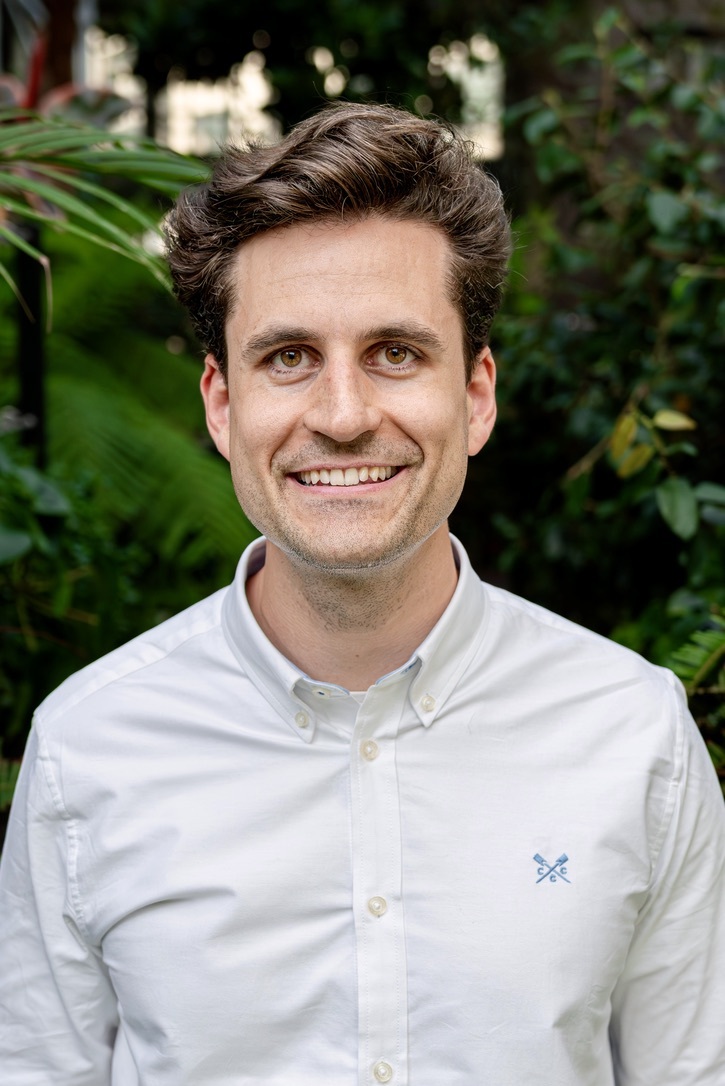
In a 2025 interview with Zanda, Steinberg explained that the team’s hands-on approach had ceased to fit PwC’s wider strategic direction. They wanted to build their own business helping startups raise. Mountside’s operating partnership was incorporated in May 2020. Leaving a large firm put them in the position of the entrepreneurs they advised, with a proposition of their own to prove.
Their wager was that fundraising could be made more deliberate. A persuasive story matters, but the revenue assumptions, market argument and funding request must agree. For a technical founder meeting institutional investors for the first time, having someone translate between those worlds can be useful. Charm has its uses; it is a poor substitute for a defensible forecast.
Free has a paying customer
For pre-seed and seed companies, Mountside runs a different service: free investor-readiness accelerators. Corporates, venture funds or government organisations fund the programmes. They target founders expecting to seek VC capital within three to twelve months, with sessions on pitch decks, financial modelling, valuations, term sheets and negotiation, plus coaching and investor office hours.
The toolkit is unusually practical. It includes a cap-table template, financial model, investor FAQ, data-room checklist and investor-update guidance. These are documents a founder can continue using after the workshops. The company says more than 800 founders have passed through its startup accelerators; that is a participation claim, rather than proof that every graduate secured funding.
Commercial advisory has another set of incentives. Mountside says it works entirely at risk. In its published discussion of adviser fees, the firm explains that payment is deferred until closing, with lower fees for later-stage raises. That arrangement makes selection consequential: the same article says it turns away most companies it speaks to. Founders should agree the actual fee and scope before engaging.
Then the investors needed investors
Venture capital contains a pleasing reversal. The person assessing a founder’s pitch must eventually make a pitch of their own. Venture funds raise money from limited partners, including institutions, family offices and funds of funds. Finding promising companies and persuading those LPs to commit are different jobs. Excellence at one does not automatically confer competence at the other.
Mountside had been organising LP events and publishing research when fund managers began asking for more fundraising help. Those requests changed the scale of its response. In October 2024, it announced an Emerging VC Manager Programme; its first cohort followed in January 2025. More than 500 funds applied for 20 places. The people accustomed to selecting founders were now being selected themselves.
Demand for training is a signal of interest, not a measure of investment returns.
The programme serves European emerging managers, broadly raising their first three funds. It offers LP introductions, fundraising templates, workshops and mentoring. Corporate partners fund participation: Blue Future Partners handles fund selection, Osborne Clarke supplies legal expertise, and other partners cover accounting, administration, communications and technology. Free entry removes a financial hurdle while leaving the selection hurdle firmly in place.
“Warm introductions are not required and may delay the process.”Mountside’s VC programme application guidance
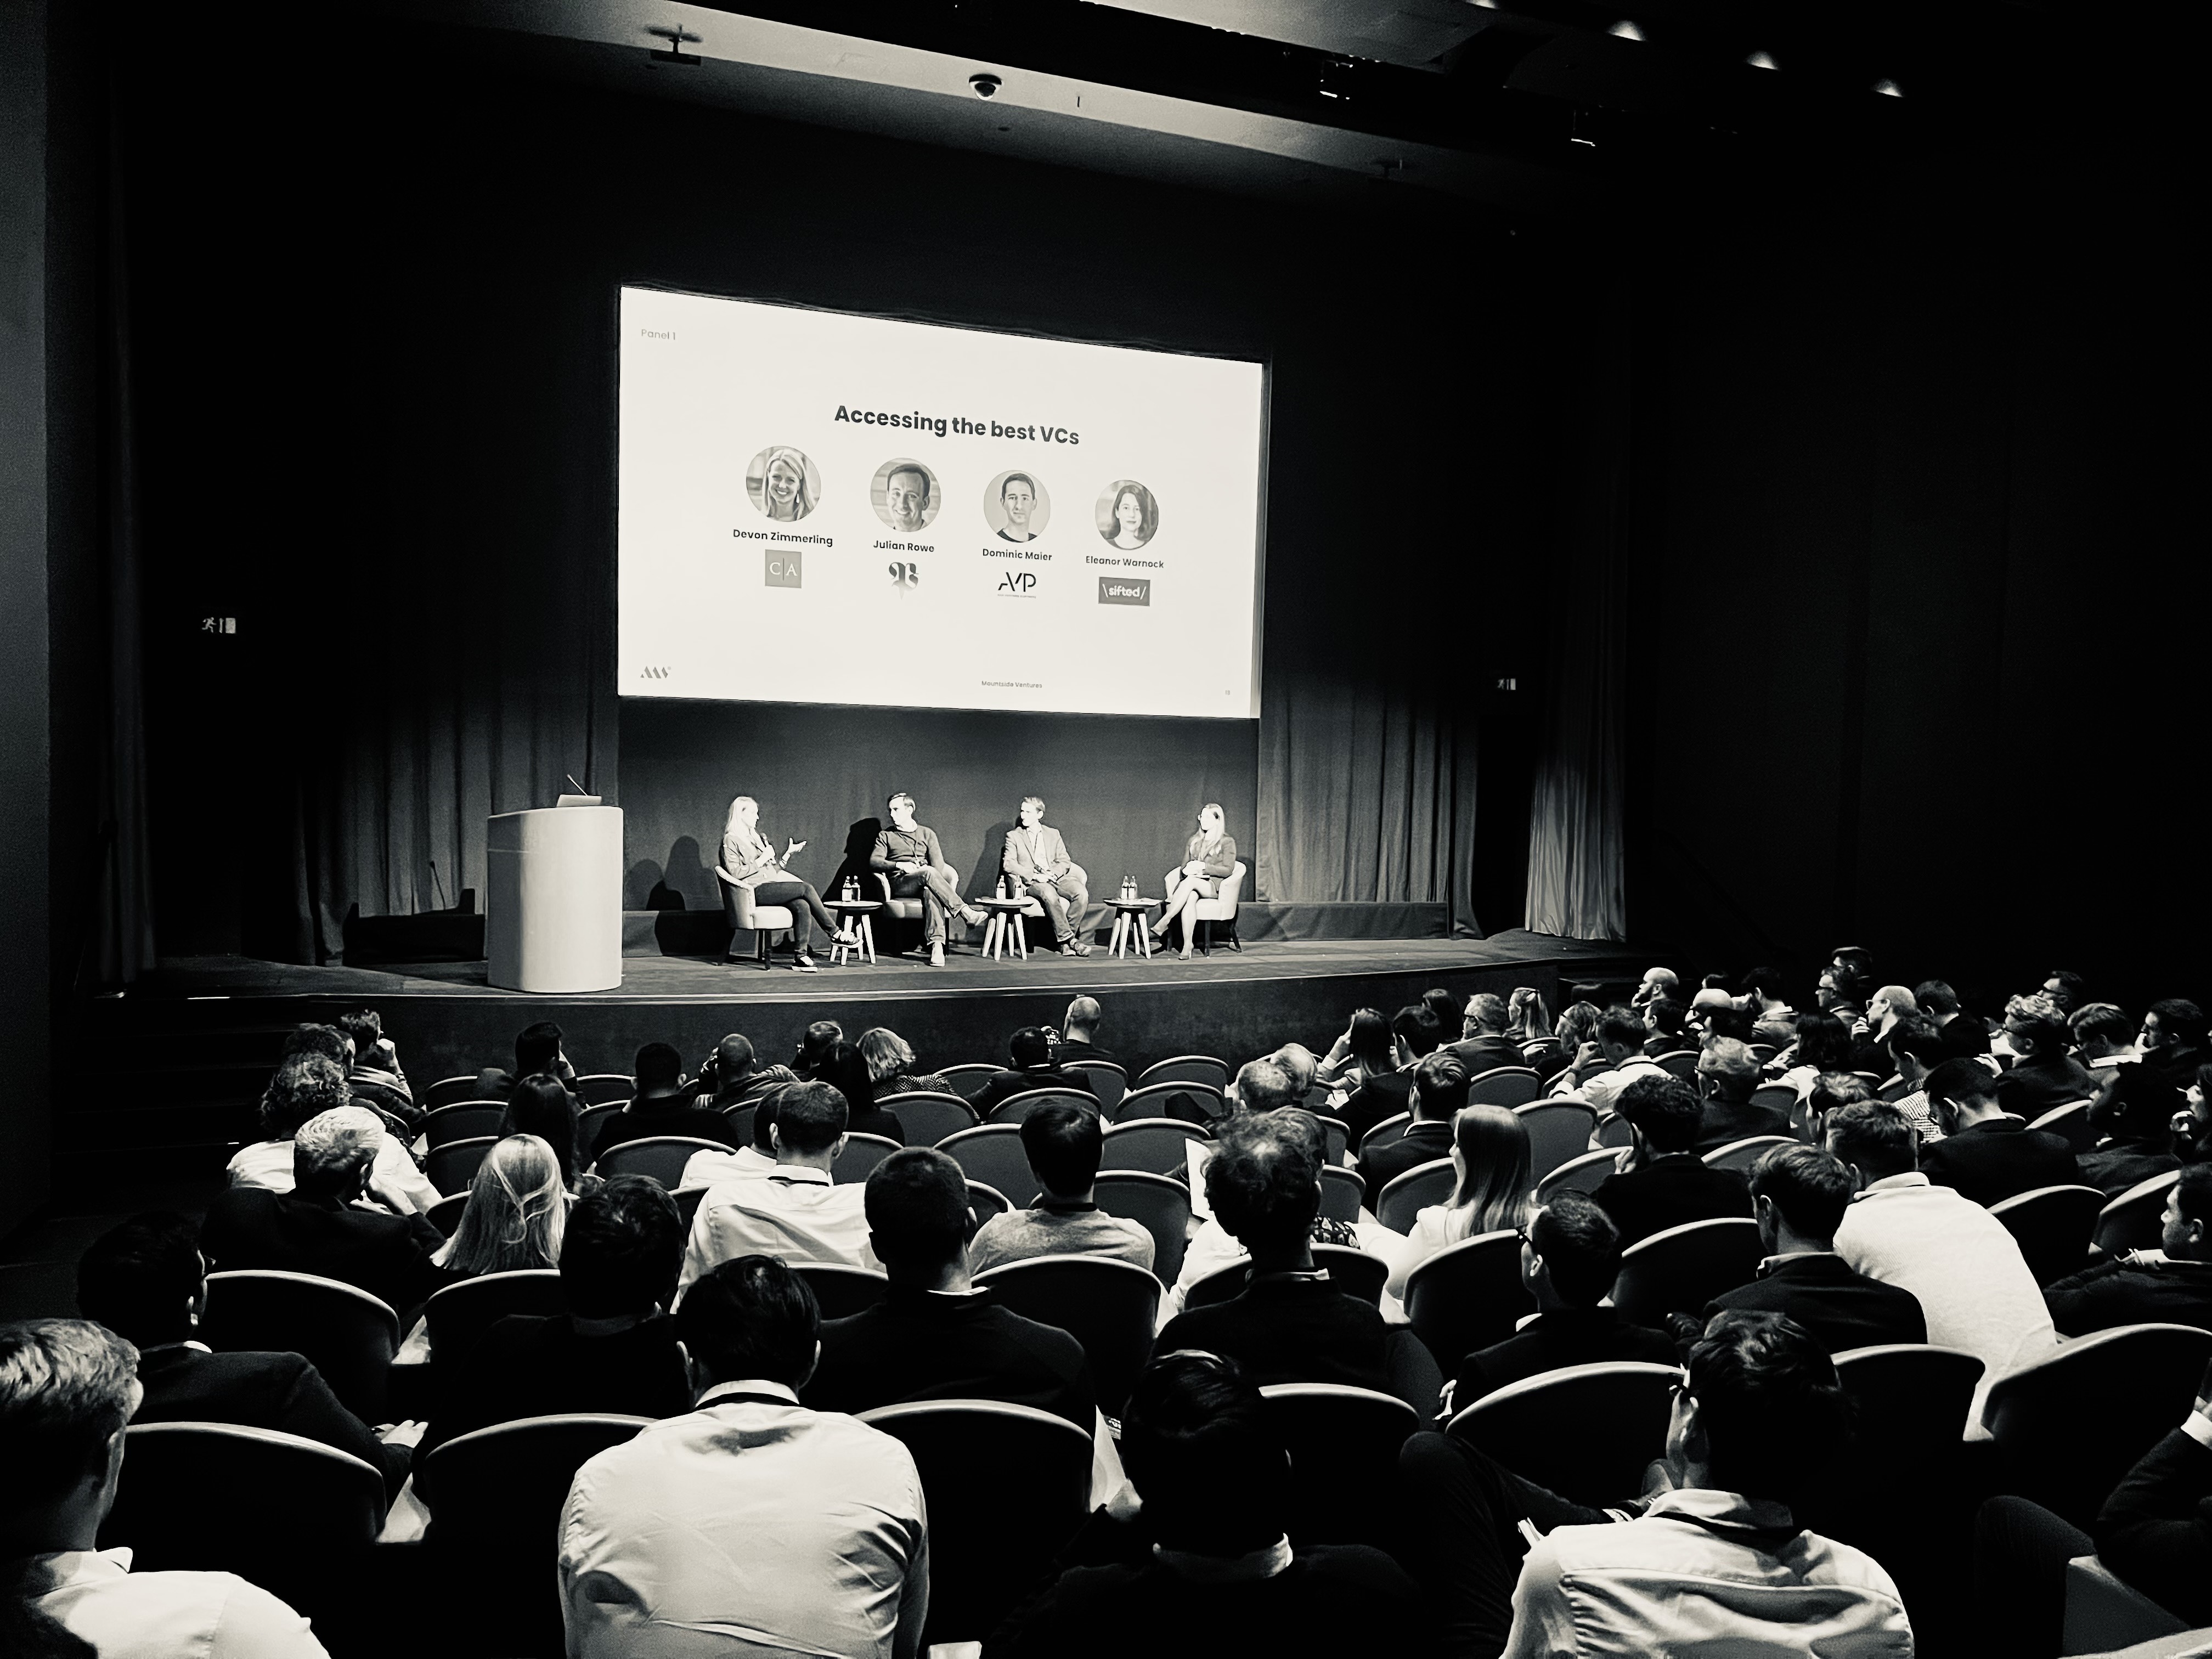
There is also a time price. The published 2026 schedule calls for six workshop days, at least ten hours of mentoring and two LP matchmaking events. Mountside’s Funding Venture conference provides another meeting point, with invited fund managers, LPs and family offices. It says speakers and funds are chosen on merit, rejecting pay-to-play selection. Access still requires preparation.
Copy the preparation, keep the judgement
A founder can borrow the method without hiring the firm. Make the deck and model agree. Write answers to predictable investor questions. Build the data room early. Identify investors whose mandate fits the business, then approach them with materials that can survive scrutiny. A longer contact list is an expensive consolation when the contacts are wrong.
The fit matters as much as the checklist. The startup accelerator assumes a prospective VC raise; bespoke advisory targets post-revenue companies seeking more than £2 million. The VC programme expects evidence of investing activity. None of these services turns an unsuitable business into an attractive investment by rearranging its slides. Mountside’s useful proposition is more modest: give a credible company, or fund, a better-organised chance to make its case.
Open the toolkit
Explore the programmes, preparation guides and conversations behind the company.
Mountside Ventures ↗Startup accelerator ↗Emerging VC programme ↗Fundraising resources ↗Company essays ↗LinkedIn ↗Twitter / X ↗Watch: Jonathan Hollis on fundraising ↗Watch: Jon Steinberg on Venture Voices ↗