The window seat is a small thing until somebody decides who gets it. When RIVO Holdings redesigned its San Diego workplace, enclosed rooms moved toward the building’s core. Workstations went beside the glass. The people handling the everyday business got the daylight. For a company selling customer interactions, that arrangement offers a useful place to begin.
- The offer: outsourced lending operations, from acquisition through servicing and early recovery.
- The buyer: financial businesses needing a department, extra expertise, or a broader operating team.
- The question: how well do service quality, incentives, and the underlying loan fit together?
RIVO calls itself a financial technology company. Its homepage quickly brings that label down to earth: sales, customer service, underwriting, delinquencies. These are the jobs behind the cheerful application screen. Someone must explain a decision, respond to a borrower, and handle the moment when a payment does not arrive. RIVO offers businesses the staff and systems to do that work.
A brand with somebody else on the phone
Consider a lending business as a chain of handoffs. Marketing attracts a prospective borrower. Underwriting evaluates the application. Servicing maintains the account. Recovery addresses trouble. RIVO’s service menu spans that chain, alongside recruiting, training, administration, compliance, analytics, and software development. The company offers support for a single function or a wider operation, configured around the client’s needs.
Its stated lending niches include automotive, dental, education, home improvement, medical factoring, and powersports. These are markets it says it can serve, rather than a disclosed roster of customers. The common problem is recognizable: a financial business wants to grow without rebuilding every operational function itself. RIVO’s proposition is to supply specialized work while representing the customer-facing brand.
- 01Acquire
- 02Assess
- 03Service
- 04Recover
For a prospective client, that suggests a concrete starting point: identify the handoff that is causing trouble. Is it reaching applicants, explaining account details, or following up when payments go wrong? Then define what a good result looks like before choosing the scope of support. That is a way to evaluate the offer, rather than evidence that any particular client has achieved those results.
That places RIVO between an internal operating team and an outside contact-center provider, with lending expertise and technical services bundled into the offer. The practical distinction is breadth. A buyer can discuss underwriting support and customer reengagement with the same organization. Whether that arrangement beats separate specialists depends on execution, integration, and the buyer’s requirements.
The office is part of the argument
Founder Daniel Koetting’s biographical page dates RIVO’s start to 2008. The name spells out respect, integrity, value, and opportunity. On its company page, RIVO connects those values to training, professional opportunity, and representatives who act as ambassadors for clients. This is an employer’s account of itself, but the office supplies something concrete to inspect.
Architect BNIM documents a 15,100-square-foot project completed in 2016. It included 139 workstations and 14 private offices. Low partitions preserved views; planters replaced conventional workstation end panels. Shared rooms gathered around an open stair. Design and documentation had an eight-week schedule, followed by a four-month construction phase. The team detailed interiors during permitting to keep the work moving.
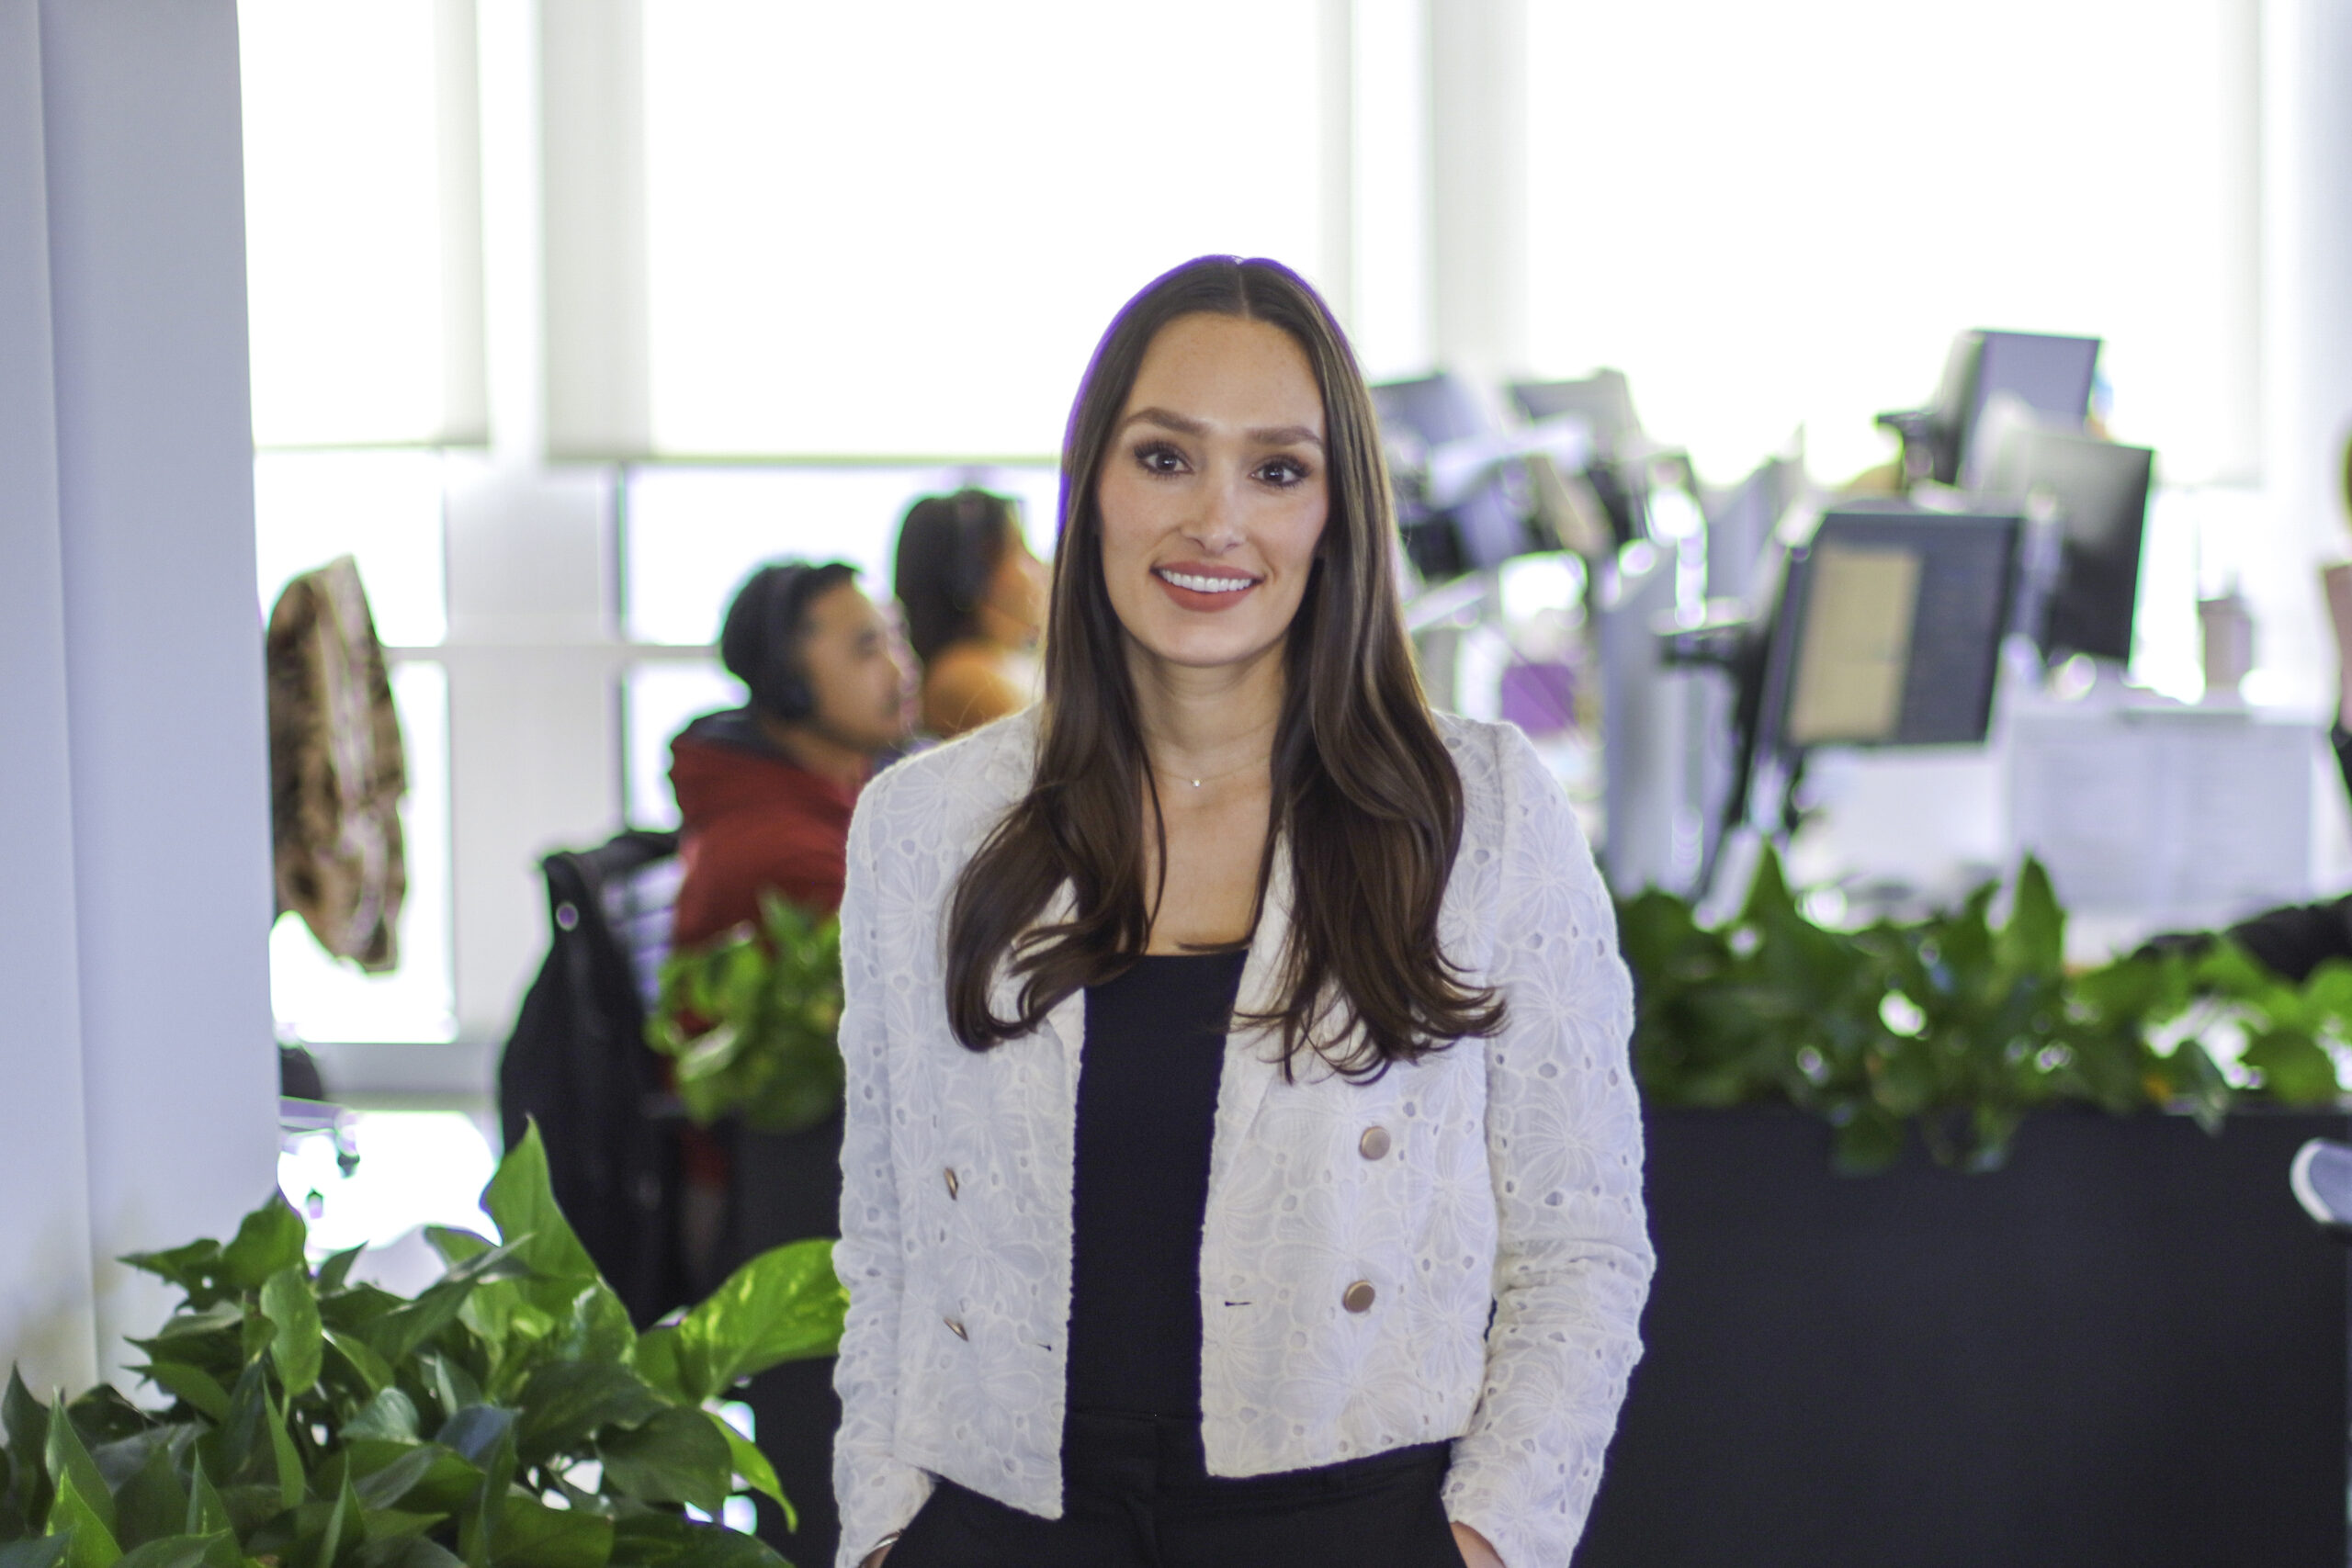
The inference is straightforward: if attentive service depends on people, the workplace belongs in the operating discussion. Plants cannot establish a return on investment. Neither can a handsome staircase. What the design demonstrates is a set of choices about daylight, shared space, and who receives them.
Opportunity has a performance target
RIVO’s careers page makes the employment bargain explicit. It advertises performance bonuses and recognition alongside training, internal promotion, tuition reimbursement, and daycare reimbursement. Its culture pitch combines advancement with measurable work. For someone considering a role, that combination matters more than the adjective “fun”: there are incentives, expectations, and a proposed path upward.
The company’s published testimonials add another view. DataX describes balancing business needs and customer experience. Decision Cloud discusses analysis, reporting, and decisioning. These are selected endorsements, rather than independent performance studies. Still, their subject matter is revealing. RIVO’s business involves the decisions around a customer interaction as well as the conversation itself.
“People are our passion.”RIVO Holdings, company statement
A useful clue in a job description
A current engineering vacancy describes a more specific technical ambition: hire RIVO’s first in-house Senior Data Platform Engineer to modernize legacy data structures and support analytics, machine learning, and near-real-time processing. The advertised annual salary is $160,000-$220,000. That is compensation for one role, not the price of the platform or a client contract.
Annual salary range for the senior data platform role. A hiring plan, not a completed transformation.
The distinction is useful. A recruitment brief can reveal where a business wants to go without proving it has arrived. Here, it points toward infrastructure that can serve both reporting and more demanding data workloads. It also gives prospective technical employees an unusually concrete assignment: help determine the architecture while rebuilding the foundation.
A pleasant call does not settle the lending question
There is another side to this operating story. In September 2024, ProPublica reporting republished by Wisconsin Watch identified RIVO as servicing two websites associated with Lac du Flambeau lending businesses. The investigation examined high-interest tribal lending and the relationships behind it. It identified Koetting as RIVO’s founder and CEO and reported that he did not respond to its requests for comment.
A May 2023 federal complaint in McLaughlin v. Opichi also named RIVO, alleging involvement in unlawful lending. Those are allegations in a complaint, not findings of liability. They belong in the profile because the underlying product matters alongside the quality of the service used to deliver it.
For an operator, the transferable lesson is to examine the whole relationship: acquisition incentives, underwriting decisions, customer explanations, repayment, and recovery. Outsourcing can help organize those handoffs. Its usefulness depends on clear responsibilities and compatible systems. A courteous representative can improve an interaction; evaluating the loan itself requires a separate look at its terms. Both judgments belong in the same conversation.