Andrew Rea had a last-minute trip to San Francisco. Recall Capital built him a miniature CRM: whom to meet, why each person mattered, and how to approach the conversation. Then it arranged the introductions. Rea’s account, published by the firm, puts the result at 10-15 meetings. The revealing detail is the preparation. Someone had done the homework that usually gets left to the founder.
- Pre-seed capital for B2B software, fintech, and infrastructure.
- Sales help includes buyer introductions, pitch work, and pipeline programs.
- The useful lesson: make every request for help specific.
That small administrative object explains Recall’s ambition better than a sweeping promise about founder support. A contact list becomes useful when it contains judgment: this buyer, this problem, this reason to talk now. Recall wants to occupy the space between an investor recognizing a promising company and a customer recognizing a reason to buy.
A partner with editing rights
Founded in 2023 by Somrat and Sarah Niyogi, Recall invests at pre-seed in enterprise software, vertical SaaS, infrastructure, and fintech. Its published check range is $300,000-$1 million. The intended founder is early enough that selling remains a personal responsibility, with messaging and market fit still being worked out alongside the product.
Consider Volca, which builds revenue software for trade businesses. Its co-founder and CEO, Brendan Kazanjian, describes Somrat requesting access to edit the fundraising deck. Three days of discussion followed about expanding the company’s vision and usefulness to home services businesses. The deliverable was a document the founder was already using. The intervention happened inside the work.
“he asked for editing rights”
Brendan Kazanjian, co-founder and CEO of Volca, on Somrat Niyogi
There is a sensible distinction here. A pitch can reveal uncertainty about the buyer, the market, or the product’s purpose. Working through the deck gives an investor a chance to challenge those assumptions while they are still cheap to change. Kazanjian’s account describes a larger vision emerging from that exchange. It does not establish that every suggestion became a successful sale.
Six chances to write the first pitch
Somrat’s biography supplies the background: two startups as CEO and co-founder, and operating experience at Salesforce, Clari, and Gusto. The six first sales decks are a particularly apt credential for this strategy. They place the emphasis on starting the commercial conversation, before a company has a polished sales machine or a dependable explanation of why customers buy.
Sarah and Somrat’s AngelList syndicate described an earlier habit of investing through their own network. A March 2026 Slice interview identifies Sarah’s background as Plaid’s first general counsel and six years at Scale. Their route into venture grew out of operating careers and angel investing. That history helps explain the emphasis on people who can answer a practical question or open a relevant door.
Put the network to work
Recall packages its support into coaching, educational programs, and pipeline generation. Its public network spans sales, marketing, revenue operations, product, finance, and other functions. Listed participants include Gusto co-founder Tomer London and finance and product leaders with experience at companies such as Carta and Tableau. For a founder, the attraction is access to experience matched to a particular problem.
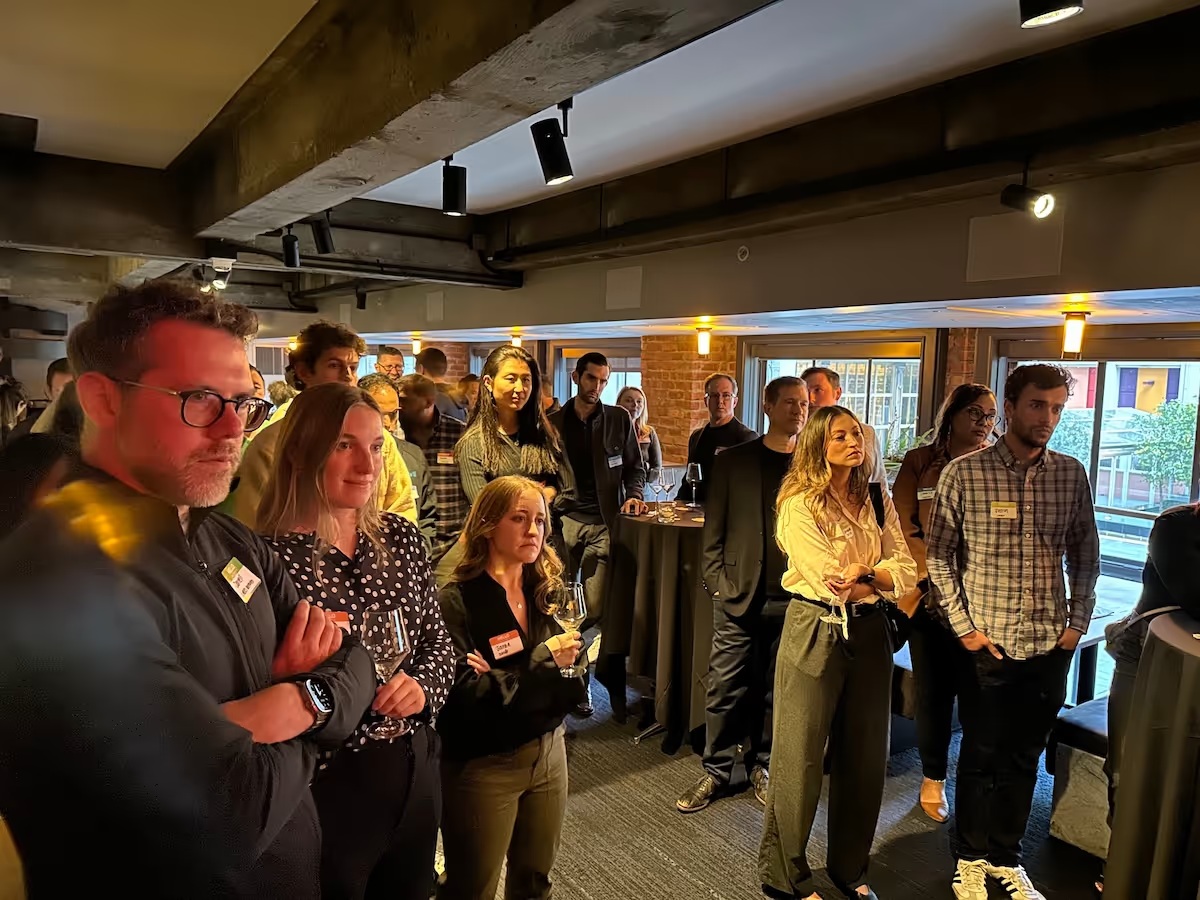
The firm’s April 2024 newsletter makes that network tangible. It reported a marketing-leader event with Bain Capital Ventures and announced a vertical SaaS and embedded fintech reception with OMERS and Gusto. Events serve a commercial purpose in Recall’s explanation: connecting potential buyers with founders. A dinner earns its place in the strategy when the people across the table have a reason to keep talking afterward.
- 01Identify
the buyer - 02Prepare
the reason - 03Make
the intro - 04Follow
through
The check has a denominator
Recall is a venture investor: it puts pooled investor capital into young companies. The February 2025 Fund I filing summary reports $13.87 million sold to 81 investors. An April 2026 Fund II filing reports a $25 million offering, with approximately $4.6 million sold to 17 investors. Those figures describe fund fundraising. They measure neither the firm’s revenue nor the revenue its founders produce.
The same care applies to the portfolio. Recall’s site separates Angel investments from Fund I positions. Deel, Collective, and CaptivateIQ appear under Angel; Arphie and Clarify appear under Fund I. The distinction lets readers see a longer investing history without treating every recognizable company as an investment made by the newer fund.
A useful mistake, discussed in public
Recall’s interest in early selling also appears in Recall Sessions, hosted by Somrat on the Village Global Podcast. In a March 2026 conversation, London described Gusto’s early $2-per-employee monthly price. He had treated a low price as a way to remove resistance. Customers could read it as a question about whether the payroll provider would survive. His conclusion: price itself communicates trust.
That is a guest’s experience, rather than a Recall portfolio result. It nevertheless shows the kind of revision this approach values: examine what the customer hears, then reconsider the founder’s original assumption. An introduction can expose a company to the market. It cannot make the market interpret the offer as intended.
For a founder choosing help, the comparison is practical. A sales advisor can work on a defined assignment; a venture investor also takes a financial interest in the company’s future. Recall combines that investment relationship with commercial assistance. The fit therefore turns on the work ahead. A team with a clear buyer and a thin pipeline has a different problem from a team whose product draws polite interest but little urgency. Before asking anyone to open doors, a founder should be able to explain what a useful meeting would teach and what decision could follow it.
Borrow the homework
Founders can copy the preparation immediately. Name the accounts you want to reach. Explain why each belongs on the list. Give the person making an introduction enough context to make it credible. Track what happens after the meeting. This is an inference from Recall’s examples, and its usefulness depends on having plausible buyers and a product that addresses their needs.
For companies selling outside that network, or still unsure whose problem they solve, access alone has limited value. The meaningful test comes after the introduction: does a customer recognize the problem, commit resources, and return? Recall’s proposition puts an investor close enough to help work on those questions. Rea’s mini-CRM is a good place to start looking.