Gabriel Jarrosson looked at RealRoots and passed. That could have been the whole story: another startup, another investor, another polite no. Then the numbers interrupted. Lobster Capital’s system flagged the company’s traction, and Jarrosson took the meeting. The investor had built a process capable of disagreeing with him.
He describes the reversal in an October 2026 essay. It is a useful introduction to Lobster because it shows something more interesting than conviction: a rule for revisiting conviction. In a business that sells judgment, the willingness to reopen a decision deserves attention.
- The territory: early-stage Y Combinator companies, exclusively.
- The offer: managed startup exposure for LPs; capital and introductions for founders.
- The test: customer traction first, then the pace of growth.
The price of a smaller pond
Lobster begins with an unusually explicit boundary. Its pitch is to invest in the top 2% of YC companies. Read that as a selection ambition, rather than a certified league table. The company wants a small shortlist inside a pool already selected by somebody else.
The attraction is understandable. YC says it has funded more than 5,000 companies and accepts roughly 1% of applicants. Demo Day takes place four times a year and is invitation only. For an investor watching from outside, even knowing where to look does not guarantee a seat.
Lobster sells the work between knowing and owning: finding companies, assessing them, obtaining allocations and monitoring the portfolio. Its LPs supply capital to a fund; the fund buys startup stakes. Founders receive financing and, according to the firm, targeted introductions. The product is professional judgment applied to private investments.
That puts Lobster alongside specialists such as Rebel Fund, which also combines YC concentration with data-assisted selection. Direct angels and syndicates offer more individual choice. A managed fund hands those choices to a manager. Lobster’s proposed advantage is familiarity with one ecosystem, coupled with its own traction filter. Those claims still have to earn their keep.
The ticket is substantial. Its public LP explainer describes typical commitments of $1 million to $10 million. A Fund II filing describes management and performance compensation. For the buyer, commitment size is only the beginning: fees, ownership and eventual proceeds determine the economics.
- 01YC universeChoose the hunting ground
- 02TractionClear the evidence bar
- 03GrowthAssess the trajectory
- 04DecisionWeigh price and access
Conceptual sequence from Lobster’s published approach. No implied success rate.
In the same pricing essay, Jarrosson describes entering RonanRx at a $50 million valuation ten days before Demo Day; he says the company raised at $100 million there. The story illustrates his interest in growth and timing. A subsequent valuation also reflects demand for the round. It cannot, by itself, prove what the investment will ultimately return.
Notice what happened at RealRoots. The initial impression failed the process’s second look. The copyable move is to define evidence that can challenge an attractive story - including the story an investor tells himself about his own instincts.
“I passed on RealRoots at the first look, but then our data flagged the traction and I took the meeting.”
Gabriel Jarrosson · October 2026
A camera at the deal table
Lobster also spends time explaining itself in public. Its video library ranges from investment commentary to founder conversations, including an interview with AgentMail’s Adi. The subjects are adjacent to the work of finding and understanding startups. For a prospective founder or LP, they provide a way to inspect the investor before a meeting.
The practical mechanism is familiarity. Someone can hear the questions Jarrosson asks, decide whether those questions are useful, and arrive with a view of his judgment. Publishing can make an otherwise obscure firm easier to recognize. That is an interpretation of the distribution strategy, rather than proof that an audience produces better investments.
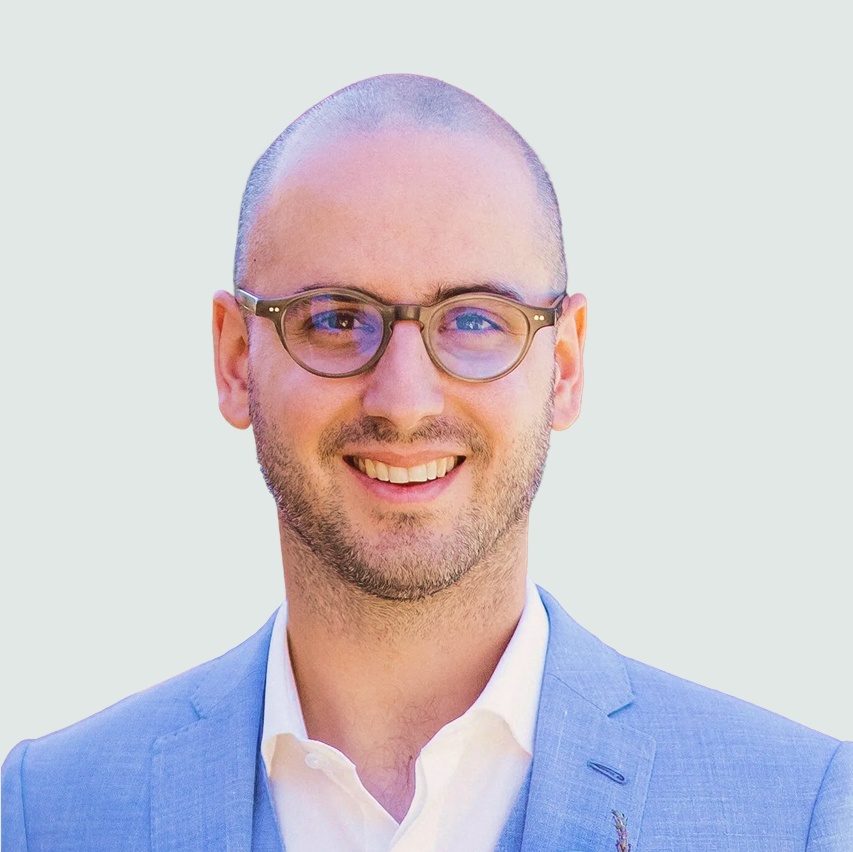
The firm’s biography describes seven ventures, three exits and four failures. That is a refreshingly untidy résumé. It also places his experience on both sides of the table. The firm dates its investigation of YC concentration to 2019 and its launch to 2023. The groundwork preceded the fund.
Forty-one bets. Still an open question.
The debut fund closed at $12 million. In an April 2026 update, Lobster said Fund I was fully deployed across 41 companies. Its final investments included identity platform Didit, note-taking company Pocket, recruiting business Perfectly and data-center developer Voxel Energy. One accelerator can contain very different businesses.
deployed first fund
A portfolio count measures deployment. Investment outcomes take longer.
The wider portfolio directory extends from VideoGen’s video tools to Scanbase’s diagnostic-test analysis and Array Labs’ satellite mapping. The common thread is the sourcing network. Industry variety gives the portfolio different commercial exposures while leaving it dependent on the same startup ecosystem.
For a founder, the fit is straightforward: YC membership gets the company into Lobster’s territory; evidence of demand makes the conversation relevant. For an LP, the job is to evaluate the manager doing that selection. Neither audience should confuse an accelerator’s reputation with a guarantee about an individual company.
Numbers require boundaries. Lobster’s broader $40 million-plus, 100-plus-company history begins before the firm’s formation. It should not be mistaken for Fund I alone. Likewise, a private holding marked up after another financing is an estimate of value still held. Cash distributed to LPs answers a different question.
Copy the second look
Lobster’s manager-diligence guide makes a useful demand: examine what a manager could buy, what it chose, and what it paid. Ask for dated decisions and passes. Look at deals pursued but lost. A selection process becomes easier to assess when the record contains the awkward cases.
This approach needs conditions: access to investable rounds, reliable customer evidence and prices that leave room for returns after dilution and fees. It offers little comfort to someone who needs ready access to their money. A narrow network can concentrate blind spots as well as expertise.
For readers outside venture capital, the useful habit travels well. Keep a record of refusals. Decide what evidence would reopen them. Then actually look. RealRoots makes Lobster’s process tangible because the first answer was allowed to change.