Payroll has a funny way of looking simple from the boss's side. A number leaves one account on Thursday. Somewhere across a border, a designer, engineer or recruiter begins refreshing an app. Between those two screens sit a contract, an identity check, a tax form, a foreign-exchange spread, several payment networks and at least one person in finance quietly hoping nothing bounces.
Ontop built its company inside that anxious space. Founded in Bogota in 2020 and now headquartered in Miami, the company sells software for onboarding, managing and paying independent contractors in more than 150 countries. Then it keeps going. The worker can receive earnings into an Ontop Global Account, hold money in dollars or euros, move it to a local bank, or spend through a Visa card where available. The employer buys an orderly process. The contractor gets something closer to a financial home.
01 / The wedge
It followed the money past payroll
The obvious product in this market is an employer dashboard. Put contracts in one tab, invoices in another, add a big button marked “pay,” and sell relief to a people-operations lead. Ontop does that. Its more interesting choice is to treat the payment as the middle of the experience rather than the end.
That choice changes the product. A contractor in Colombia or Argentina may invoice a US company in dollars but live in a currency that moves differently. A bank can force conversion, an international wire can take days, and intermediary fees can turn the promised number into a smaller surprise. Ontop lets eligible workers keep funds in a dollar-oriented account, choose among payout routes and use a linked card. Availability, speed and fees still depend on the country, but control itself is the feature.
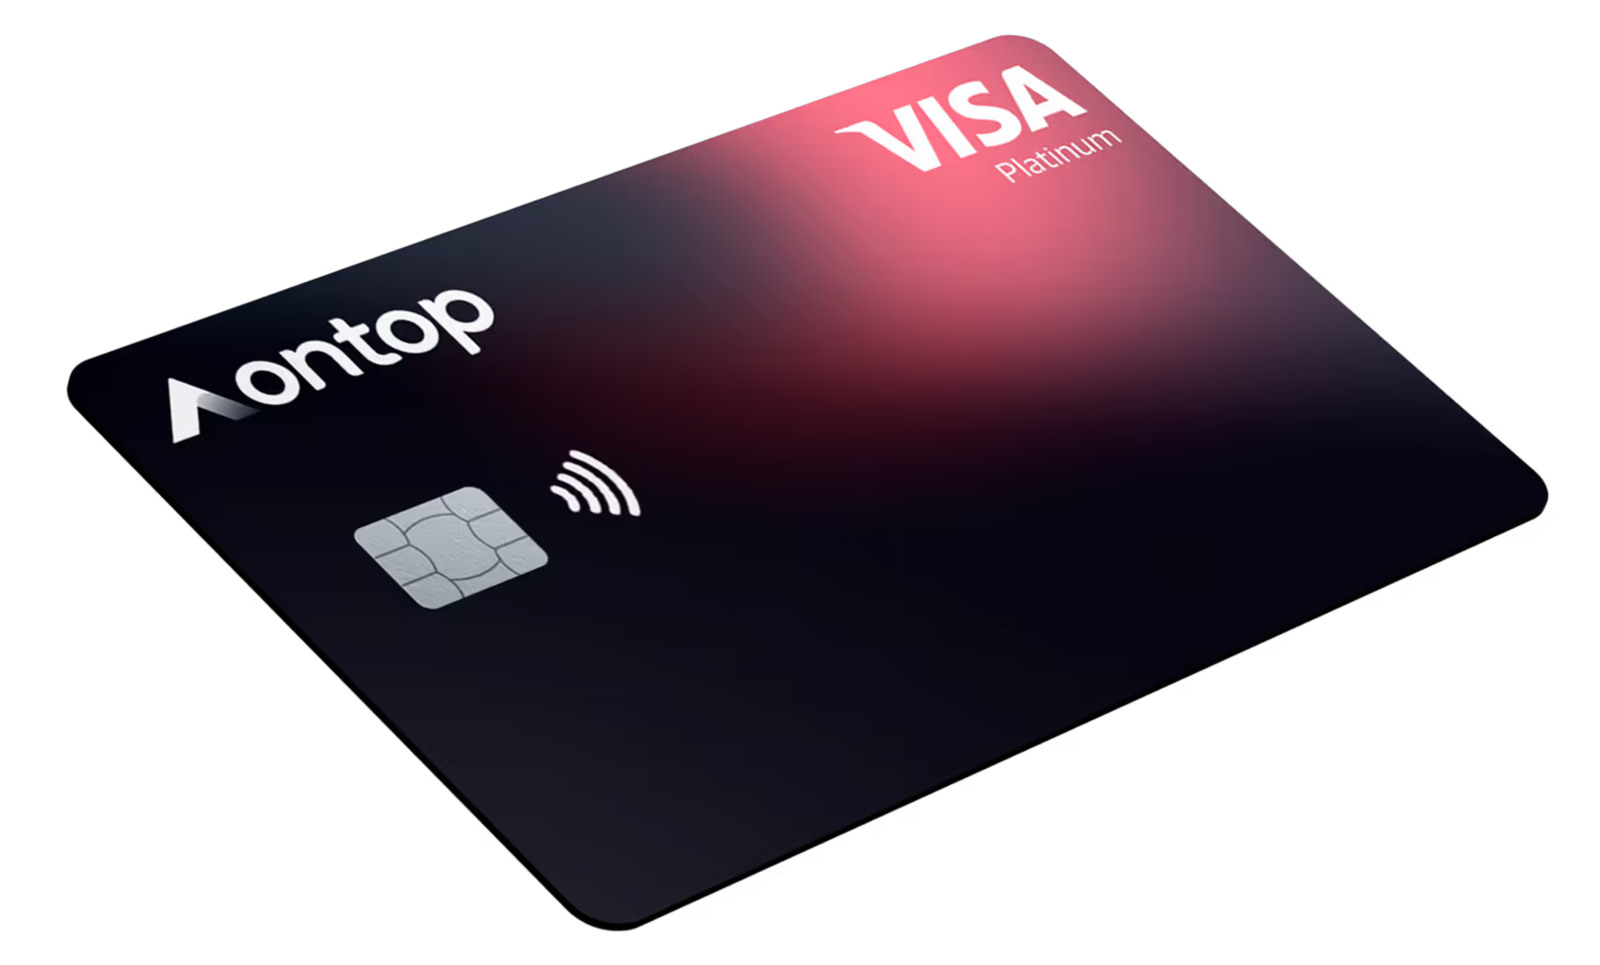
For the company, the pitch is consolidation. Contractor agreements, document collection, compliance checks, recurring payroll, approvals and records live in one place. Public customer stories feature businesses such as Shared Tech, BrightChamps, Zero-Code, OLIVER, NFTrade and Trii. The ideal customer described in Ontop's own materials is remarkably concrete: a remote or hybrid company with at least 20 employees, ten or more contractors abroad, and enough cross-border admin to make every pay cycle feel homemade.
“We are building the global bank for the future of work.”María Camila Ramírez, COO, on The Founder's Code
02 / The machine
Four jobs hiding inside one payday
Ontop's workflow is less magical than methodical. A company first passes know-your-business checks. The worker completes identity verification. The parties generate and sign an agreement. Finance funds and approves payroll. Only then does money reach the worker's account. Ontop says verification averages about three days, while a company's first payroll typically arrives 18 to 25 days after onboarding begins. That distinction matters: a payout can be quick even when becoming ready to pay is not.
The company makes money like SaaS, charging per active contractor, with a public starting point of $49 a month. The final quote changes with countries, volume and contract model. The worker account has no maintenance fee. Ontop Reserve, an optional benefits membership, is listed at $14.90 monthly or $145 annually. Payment and foreign-exchange charges vary by route. This is the stack in miniature: recurring software revenue on the employer side, financial products on the worker side.
Partnerships supply much of the invisible plumbing. Paysend added direct payouts to Visa and Mastercard cards in 2023. Thredd partnered on issuing, wallets and account tools in 2025. Thunes opened real-time local-currency bank payouts in markets including India, the Philippines, South Africa, Vietnam and the UK. Ontop owns the experience; specialist networks help the money take the last mile.
03 / The correction
More people were not the same as more progress
Ontop's timing was almost suspiciously neat. The pandemic made remote hiring ordinary just as the company was forming. It entered Y Combinator's Winter 2021 batch, raised a $4.5 million seed round and, months later, announced a $20 million Series A led by Tiger Global and Point72 Ventures with SoftBank participating. An additional round followed in early 2023. Publicly reported funding totals differ by database, but the documented rounds show at least $34 million moving into a company barely three years old.
Money bought reach and headcount. A 2024 profile described a team that had climbed from 14 to more than 200 people across 25 countries. Yet founder Julián Torres later shared the less flattering chart: headcount had jumped while revenue per employee fell. Hiring looked like growth from a distance. Inside the machine, efficiency was moving the other way.
The operating assumption that a larger team automatically produced a stronger company. Ontop's public account says the response was to keep headcount steadier, automate critical processes, focus on product and direct office savings toward talent and tools.
That changed the internal story. Ontop is fully remote and says it spends nothing on offices. Leadership has pushed employees to become “AI operators,” applying automation to job descriptions, contract work, tax forms, notifications and operational tasks. Ramírez has said the transition did not require layoffs. This is not evidence that every AI experiment worked, but it is a clearer management idea than buying a chatbot and calling it transformation: train the existing team, choose repetitive workflows, and measure output per person.
The market positioning tightened too. Older descriptions often put employer-of-record services in Ontop's catalog. Its current help center is explicit that Ontop does not employ workers on behalf of clients. The product is contractor-first. That sounds like a retreat only if breadth is the goal. As strategy, it draws a useful border around the thing Ontop wants to do well.
04 / The market
A narrower answer in a crowded category
Deel, Remote, Papaya Global, Rippling, Multiplier, Oyster and Payoneer all approach pieces of global workforce management. Some are strongest in full employment and EOR. Some start from HR records. Others start from payment rails. A company can also build a cheaper-looking pile from local lawyers, spreadsheets, banks and Wise transfers, then discover the cost when a document expires or a payment fails on Friday afternoon.
Ontop's distinction is not that it invented contracts or cross-border payments. It is the contractor-first bundle and the worker account attached to it. The employer gets fewer vendors; the contractor gets more agency over the money. That two-sided experience can create stickiness, though it also creates exposure to payment partners, changing regulation and support expectations on both sides of every transaction.
Good conditions
- Ten or more contractors across several countries
- Repeated contracts, approvals and payouts
- Workers value holding or spending global income
- Finance wants one audit trail
It will not work when
- The role legally requires employment
- The company needs an EOR to become the employer
- Everyone is domestic on one local payroll
- A required payout method is unavailable locally
The legal boundary deserves special attention. A compliant contract does not magically turn an employee-shaped relationship into an independent business. Ontop performs workflow checks and provides localized agreements, but it does not decide classification for the client or file a worker's personal taxes. Companies still own the employment decision. If a manager controls hours, exclusivity and daily methods like an employer, software cannot wish that fact away.
05 / The playbook
What another founder can actually copy
First, map the whole journey, including what happens after the buyer thinks the job is done. Ontop could have stopped at “payment sent.” It followed the money to “payment usable.” That revealed adjacent products - account, card, local transfer, perks - tied to the same event.
Second, state the ideal customer with numbers. “Global companies” is fog. “A 20-person-plus remote company with ten international contractors” gives sales a filter and product a design target. Ontop even publishes the boundary conditions. A domestic employer with one payroll probably does not need it.
Third, use partners for regulated infrastructure but own the user experience. Paysend, Thredd and Thunes extend Ontop's rails. Rebuilding each national network would be slow and capital hungry. The tradeoff is dependency: outages, coverage changes and compliance requirements can still land in Ontop's support queue.
Finally, measure efficiency before the org chart becomes a vanity metric. Revenue per employee changed Ontop's mind because it made the mismatch visible. The reusable move is simple: pick a throughput measure, watch it as headcount changes, automate a small number of high-volume workflows, and retrain the team around the tools. It works when processes repeat. It will disappoint when the work is rare, ambiguous or legally demands expert judgment.
The sharpest part of Ontop's strategy is not the borderless promise. It is knowing exactly which border the product will not cross.
Ontop has reported profitability and more than $1 billion in processed international payments, while its current materials claim more than 950 business customers. Private-company numbers should always be read with care. The more durable evidence is the product's shape. Contracts feed payroll. Payroll feeds an account. The account gives the worker a reason to care about the same platform the employer chose.
That is a tidy loop built around an untidy reality. Global work became normal faster than global employment law and banking became simple. Ontop does not erase those systems. It packages their roughest handoffs, chooses contractors as its lane, and gives payday a better ending than a spinning transfer icon.