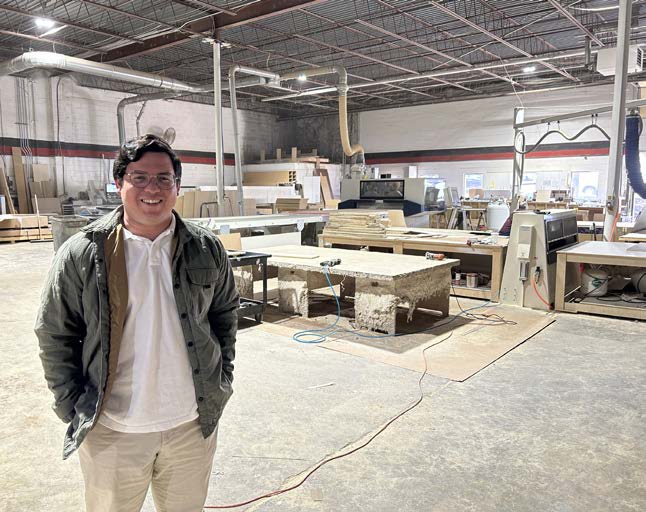
BILTCO had a problem that would have looked peculiar on a sales chart. The Washington-area millwork company could finish a job and then wait as long as 90 days to collect the money. Work was happening. Payment was happening on somebody else’s calendar. Between those events sat the ordinary, expensive business of keeping a company running.
- FVCbank serves businesses and households around Washington and Baltimore.
- Its digital lending uses Numerated; its financial dashboard uses Monit.
- The pitch is faster paperwork plus a banker who understands the customer.
In FVCbank’s account of the relationship, BILTCO also struggled to get a callback from its larger bank. A referral brought it to FVCbank. A lender introduced Lightning Lending. The company completed an online application and obtained two loans, a term loan and a credit line, with funding within 48 hours. One customer story, certainly. But a useful introduction to what this bank is trying to sell: a shorter distance between a business problem and someone equipped to solve it.
A very particular neighborhood
FVCbank opened on November 27, 2007. Its founder and lead organizer, David Pijor, was a lawyer with an earlier banking venture behind him: James Monroe Bank. Before the opening, he met potential investors and held focus groups about what people wanted from a community bank. Patricia Ferrick, an early employee who became president, later described assembling bankers who knew one another through the region’s banking circles.
The geography matters. Around Washington, a business customer might be a federal contractor waiting on receivables, a nonprofit managing its cash, or a property investor assembling a transaction. FVCbank offers specialized services for those customers, alongside professional firms, private schools, faith-based organizations and licensed cannabis businesses. These customers have different operating problems. A familiar checking account is only the beginning.
For contractors, the menu includes working-capital lines, acquisition financing, payment services and a Cync portal for invoices and borrowing-base administration. Property managers can use Rent Direct for collections and payment tracking. Retail customers have checking, savings, CDs and home equity credit. The common thread is a business relationship that can extend to owners and employees.
“We think like entrepreneurs, but work as a team.”
FVCbank’s published manifesto
Borrow the software. Know the borrower.
Community banking has an awkward engineering problem. Customers expect digital convenience even when their bank lacks a national institution’s scale. FVCbank’s response has been to work with specialists. Q2 brought previously separate online, voice and mobile banking systems into one integration. Numerated supplied the technology behind Lightning Lending, introduced in 2023. Monit powers Business Insights.
Those partnerships put the bank in an interesting middle position: a local commercial lender using technology built outside its walls. The distinction matters because the software itself is available to other institutions. FVCbank’s case for choosing it rests on how its bankers use the tools, how they structure credit and how well they understand the regional customer.
As little as 48 hours to receive funds. Eligibility and approval apply.
Lightning Lending’s current product page advertises loans up to $350,000 and funding in as little as 48 hours. The qualifications are concrete: registration in Virginia, Maryland or D.C.; at least two years in business; and a minimum credit score of 670. Ownership restrictions apply, and approved applicants need an FVCbank checking account. An attractive stopwatch does not make this a product for every applicant.
Business Insights tackles the moment before borrowing becomes urgent. Customers connect accounting software such as QuickBooks or Xero to see cash-flow forecasts, financial trends and industry comparisons. FVCbank advertises it at no additional cost to business customers. Rent Direct is also complimentary. In both cases, the tool sits inside a broader deposit and service relationship. Better information can help an owner ask better questions; its usefulness still depends on the records going in.
There is a household side to the relationship, too. Free Personal Checking lists a $50 opening deposit, no minimum monthly balance and no monthly maintenance fee. The Bank at Work program extends personal banking services to employees of business customers. That gives a commercial relationship several points of contact: the company borrowing, the owner managing personal finances and the employee receiving pay. For an owner comparing providers, the sensible exercise is to price the whole arrangement, including transaction activity and treasury services, rather than treating one complimentary dashboard as the entire offer.
The balance sheet gets a vote
The economics remain those of a bank. Interest earned on loans and investments, less the cost of funding them, is the main revenue engine. Account charges and other fees supplement it. A useful application can attract a customer. It cannot repeal the cost of money.
In 2023, FVCBankcorp sold investment securities with a book value of $102.5 million and recognized a $15.6 million pretax loss. It used the proceeds to reduce expensive short-term borrowing and fund higher-yielding commercial loans. That was a real cost of repositioning the balance sheet. It also makes a tidy technology-success story look rather incomplete.
Down 0.36 percentage points year over year. Bars use a zero baseline and a 3% scale.
Funding decisions continued in February 2026, when the parent issued $25 million of senior unsecured notes at 6.75%, after redeeming about $19 million of subordinated debt that had been paying 8.59%. Different balances and issuance costs prevent a simple coupon comparison from becoming a clean savings figure.
By the third quarter of 2026, quarterly net income was $6.6 million, up 19% from a year earlier. Funding costs had fallen, while net interest margin reached 3.32%. There were complications: the parent reported a $403,000 quarterly loss from its Atlantic Coast Mortgage investment. Good banking still requires judging what sits behind the headline number.
The part worth copying
The useful lesson is to start with the customer’s working day. Find the delay, automate the repeatable paperwork and give the unusual questions to someone who understands them. FVCbank’s example suggests a business can buy capable software while developing expertise closer to home.
That approach needs limits. A new startup falls outside Lightning Lending’s published age requirement. A company elsewhere cannot assume access. A borrower with weak repayment capacity still has a credit problem. For the right local business, though, a bank that understands the interval between finishing the work and getting paid can be a practical partner. The button gets attention. What happens after pressing it earns the relationship.