The first day’s deposits came to $227. Provident Bank’s own history puts that small sum in a one-room Jersey City office; an anniversary account adds a tin box. It is an appealingly physical beginning for a financial institution. You can picture the container. The harder thing to picture is what happens when the institution outgrows it, then outgrows the neighborhood, while continuing to sell the comfort of being local.
- Personal banking up front; substantial commercial lending behind it.
- The Lakeland merger expanded the bank across a three-state region.
- More capability came with capital requirements, conversion work and branch consolidations.
That is Provident’s present experiment. Established in 1839 as a savings institution intended to help poor immigrants, it now combines everyday deposit accounts with business finance, wealth management and insurance. The beehive associated with its history remains a useful image: many small relationships gathered into something capable of doing larger work. Whether the experience still feels personal is a question customers have to answer individually.
The useful middle
For a household, the proposition is recognizable. Provident offers checking and savings accounts, certificates of deposit, mortgages and home equity borrowing. Its digital services let customers manage accounts without making every errand a branch visit. A person can deposit a check through the mobile app, pay bills or move money. The attraction is having both a screen and a physical place to go.
The more revealing customer is a growing business. Provident’s middle-market team explicitly serves companies with annual revenue between $10 million and $50 million. Think of the privately owned manufacturer, distributor or contractor whose needs have become complicated enough to include working capital, equipment spending or an ownership transition. Those examples fit the bank’s published target industries; they are not claims about named borrowers.
Here, the problem is less glamorous than innovation advertising suggests. Money arrives after an invoice, but payroll comes before it. A company needs room between the two. Provident offers revolving credit and term financing, alongside acquisition and employee stock ownership plan lending. Its specialty business adds asset-based lending, healthcare finance, mortgage warehouse lines and SBA loans. The expertise lies in understanding what supports repayment.
Illustrative sequence, not a customer case study.
The less visible products matter, too. Positive Pay matches checks presented for payment against the business’s issued-check file. Discrepancies become exceptions for the customer to review. Lockbox and remote deposit services help handle collections. This is where a bank earns its place in the working week: by helping the finance team control the movements of money already earned.
Provident’s business model follows those movements. Lending and investments produce interest income; deposits and other funding carry costs. Fees provide another stream. Beacon Trust supplies wealth services, while Provident Protection Plus provides insurance. Compared with a smaller lender, the combined menu can cover more of a customer’s financial life. Compared with a national bank, Provident emphasizes regional knowledge and personal relationships. That is its positioning, not proof of better service.
The price of getting bigger
In September 2022, Provident and Lakeland announced an all-stock combination valued at roughly $1.3 billion. The argument was complementary capabilities: Provident brought wealth management and insurance, while Lakeland brought additional strength in asset-based lending and equipment lease financing. Chief executive Anthony Labozzetta said the combined organization could “invest in the future.” The original closing target was the second quarter of 2023.
The transaction actually completed in May 2024. Regulatory approval came with conditions. Among them was additional qualifying subordinated debt; the parent ultimately issued $225 million of notes carrying an initial 9% fixed coupon before a floating-rate period. Net proceeds were approximately $219.3 million. Those numbers describe a financing obligation, separate from the announced stock-deal value.
Subordinated notes issued by the parent in May 2024.
Notes due 2034
There was an earnings cost as well. In the second quarter of 2024, the parent reported an $11.5 million net loss, with merger-related charges weighing on results. A transaction can make strategic sense and still hurt the income statement on arrival. The missed closing target and the loss are documented friction; neither establishes that customer systems failed.
Nor did legal completion mean the practical work was finished. Provident says the two banks became a fully united organization on September 3, 2024. Its transition guide scheduled letters, online-banking reminders and card communications. There is a lesson here for anyone combining businesses: changing ownership and changing a customer’s routine are separate projects, with separate calendars.
What survives the merger
The larger balance sheet is real. At June 30, 2026, Provident Financial Services, the bank’s parent, reported $25.66 billion in assets and $19.55 billion in deposits. Commercial categories represented 87.3% of its loan portfolio. Beneath the consumer-facing checking accounts sits an institution heavily engaged in financing businesses and property. That composition helps explain why commercial expertise matters so much to its strategy.
“Commitment You Can Count On”Provident Bank’s brand promise
Growth also redraws the map. Provident’s merger information acknowledges branch consolidations where the networks overlapped. For someone whose usual branch closed, a bigger network could still mean a less convenient journey. A regional bank also makes a weaker case for someone who needs branches across the country. Geography remains part of the product, however capable the app becomes.
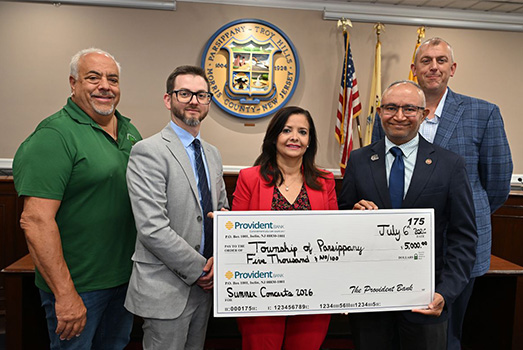
Community claims deserve concrete examples. Provident established its foundation in 2003 and acquired Beacon Trust in 2011. In June 2026, it announced $1 million in grants to ten New Jersey nonprofits for neighborhood revitalization. Those activities do not settle questions about price or service. They do give the local promise something more substantial than an old founding date.
What can another operator borrow from this story? Add capabilities customers can use together. Budget for the capital and transition work that expansion demands. Then keep checking whether the larger organization still solves the small, recurring problems that brought customers in. Provident’s tin box has long since disappeared from the daily business. The obligation represented by those first deposits is easier to recognize: look after the money, and make yourself useful.