For more than a century, WaFd Bank helped people buy houses. Then, in January 2025, it announced it would stop originating single-family mortgages. Consider the awkwardness: a bank founded to finance homes in Seattle's Ballard neighborhood had decided that financing homes no longer justified the effort. The interesting question is what happens when a company takes its founding purpose seriously enough to change its founding product.
- The turn: stop new single-family mortgages and put more attention into business lending.
- The price: a $5.4 million restructuring charge, against estimated annual expense savings of $17 million.
- The next act: a $3.9 billion EverBank combination, announced in September 2026 and still awaiting completion.
WaFd remains a bank for ordinary financial life: paychecks, savings, debit cards, business accounts. Its specialty increasingly lies where money meets a complicated operating business. The neighborhood bank now wants to be useful to the person hiring the neighborhood, stocking its shelves or building its apartments.
A house is a home. A mortgage is a price.
The original institution was Ballard Savings and Loan Association, established in 1917 by local business owners. The ambition was practical: help neighbors finance homes and build financial security. Mergers widened its territory. In 1958, it took the Washington Federal name; in 1982, it became publicly traded. The shorter WaFd Bank brand arrived in 2019. The name on the door kept changing as the organization grew.
For a long time, holding a customer's mortgage fitted that identity. But the economics became less neighborly. Management argued that government-supported mortgage markets let competitors offer borrowers lower rates than WaFd could economically match. Digital applications made comparison and refinancing easier. Familiarity with a banker had become a harder advantage to charge for.
“Everyone deserves a banker.”
Brent Beardall, in WaFd's 2025 shareholder letter
The distinction matters. A borrower may appreciate advice, then choose the cheaper loan. WaFd's decision suggests that goodwill alone could no longer carry the product's economics. Customers still needed housing finance; WaFd had concluded that originating those loans itself was an increasingly poor way to serve them profitably.
The cost of putting down the keys
The mortgage exit was an operating decision with an accounting bill. The 2025 annual report disclosed the restructuring charge and projected savings. Those figures measure different things: a charge associated with the change and an estimate of expenses avoided each year. Neither establishes the eventual profit benefit. Lost lending income still matters.
That report also named the less tidy costs: relationships, community goodwill and revenue could disappear. What failed first was the economic case for this particular lending model, in management's telling. The bank did not stop existing, and leaving mortgage origination did not mean abandoning every real estate borrower. Commercial property remained part of the business.
For another company, the useful move is to separate a customer's problem from the product historically used to solve it. Then count the revenue that disappears alongside the expenses that disappear. Without a credible replacement business, quitting a familiar product can simply produce a smaller company.
The shopkeeper needs more than a rate
Business banking gives WaFd a different conversation to have. A shop may need checking, a seasonal credit line, card acceptance and a way to pay employees. A growing company may need equipment financing or an owner-occupied building. Those needs recur, interact and resist being reduced to one comparison-shopping number.
WaFd offers business term loans, revolving credit and SBA financing, including 7(a), 504 and Express options. It became an SBA Preferred Lender in 2025. The promise is access to bankers who understand the business alongside digital tools. Credit approval still applies; a useful conversation cannot turn an unqualified borrower into an approved one.
Its checking menu shows how that relationship can grow. Free Business Checking has no monthly account fee and no initial deposit requirement, although nonsufficient-funds charges may apply. Business Interest Checking charges $15 monthly when the balance falls below $5,000. Premier Checking carries a $75 flat monthly fee. Analyzed Checking ties charges to activity, with balances available to offset fees.
Heartland supplies merchant solutions covering payments, payroll and point of sale. Treasury tools include ACH, wires and Positive Pay for fraud control. These are practical answers to a business owner's Tuesday afternoon. Against national banks, regional rivals such as Banner, and credit unions such as BECU, WaFd's pitch is the combination of local access and a wider operating toolkit. Whether it wins depends on service and total cost.
A bank is also a network
Personal customers still have checking, savings, money markets, CDs, retirement accounts and mobile banking. The app supports everyday tasks such as depositing checks and moving money. Related businesses extend into insurance brokerage and financial planning through WaFd Insurance and WaFd Wealth. The bank earns interest income and fees; those adjacent services broaden what a relationship can include.
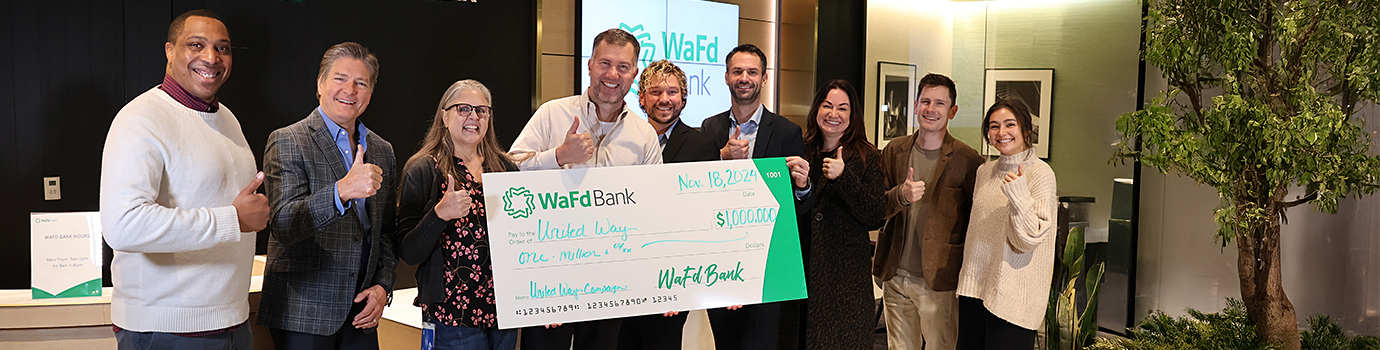
The human element is part of the proposition. WaFd describes its values as integrity, teamwork, ownership, simplicity, service and discipline. Its public business testimonials include Apex 3D Hunting Supply and Bonner Community Housing Agency. A retailer and a housing nonprofit make a useful pair: local banking has to understand very different versions of cash flow.
The next name on the door
In September 2026, WaFd and EverBank announced their proposed combination. The resulting public company would take the EverBank name, with Greg Seibly as CEO and Brent Beardall as president. Closing was expected in early 2027, subject to regulatory and WaFd shareholder approval. Until closing, the banks remain separate.
The operating turn is already visible. WaFd's October results said commercial loans accounted for 95% of fiscal 2026 originations. But shifting the portfolio does not remove lending risk: resolving one troubled relationship produced a $36 million charge-off in the September quarter. A new strategy still has to survive old-fashioned credit losses.
The lesson worth copying is the willingness to examine a beloved product's economics. WaFd started by helping a neighborhood finance its homes. Its next chapter depends on whether it can help that neighborhood's businesses well enough to earn their accounts, their borrowing and their trust.
Keep exploring
Watch / hear the bankers
▶Beardall & Lagomarsino: leadership and bank mergersTravillian Next / June 2026▶WaFd's official video channelCompany videos and banking explainers