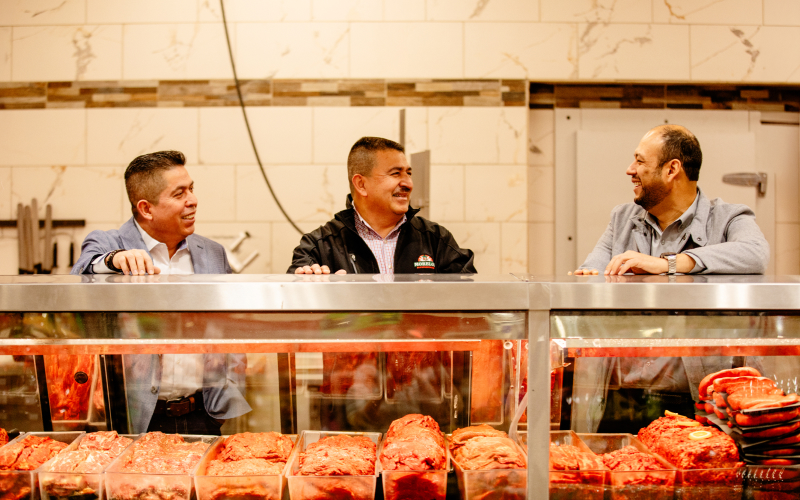
In 2019, Supermercados Morelos was still writing checks to vendors and employees. The Oklahoma grocery business had become more complicated than its payment habits. BOK Financial helped introduce electronic payments, store-level accounts and fraud controls. It is an unglamorous place to begin a bank story. It is also a useful one: expansion creates administrative problems long before anyone cuts a ribbon.
- The business: banking, wealth, payments and specialized finance.
- The distinction: teams built around industries with complicated financial needs.
- The lesson: financial systems have to grow alongside sales.
In the bank’s published account, treasury specialist Veronica Regan describes the opportunity simply: “We could see opportunities to make things faster, safer and more efficient.” That is a better introduction to BOK than a list of account types. Its proposition is that the person arranging your loan should have colleagues who understand the machinery around it.
First, understand what is underground
The lineage begins in 1910 with Exchange National Bank of Tulsa, organized in an oil town that needed capital. Harry Sinclair was among its organizers. The operating bank later became National Bank of Tulsa, then Bank of Oklahoma. The present holding company, BOK Financial Corporation, dates to 1991. Those dates describe different things: a banking inheritance and its modern corporate structure.
Energy remains an unusually revealing specialty. BOK’s team includes engineers, analysts and derivative consultants alongside bankers. It offers upstream and midstream lending, commodity hedging and mineral management. Consider the logic: financing an oil business requires judgments about both money and the asset that produces it. Technical fluency gives a lender a more informed starting point.
Healthcare changes the questions again. BOK serves hospitals, senior-care operators and medical practices, combining financing with treasury and revenue-cycle services. A physician buying into a practice and a health system managing collections need different arrangements. The appeal of specialization is the possibility of spending less time explaining why your business behaves as it does.
Its Native American Financial Services practice makes the distinction sharper. The company reports more than 60 tribal relationships and over $3 billion in committed capital to Indian Country. Its work spans enterprise expansion, government infrastructure, investments and trusts. Sovereignty, governance and tribal law belong inside the banking conversation. They cannot sensibly be added as an afterthought.
The bigger number belongs to the clients
At June 30, 2026, BOK reported $53.2 billion in bank assets and more than $129.3 billion in assets under management or administration. The second number is larger, but it is not extra money sitting on the bank’s balance sheet. It describes client assets served through a different part of the business. Mixing the two would miss the point of BOK’s design.
The trust business started in 1918. BOK says its first wealth client remains a client today. There is a pleasing mismatch between that timescale and the quarterly rhythm of a public company. Trust administration and investment advice can extend a relationship beyond a business loan, a home purchase or the working life of the person who first opened an account.
The economics follow the breadth. BOK earns interest on loans and securities, pays for deposits and other funding, and collects fees from activities including wealth management, trading, cards and mortgage banking. Commercial banking, consumer banking and wealth management are its three reporting segments. One customer can need several of these services, although the services carry different costs and risks.
Growth had a price tag
A comfortable origin story would leave out 1986. Regulators assembled a $130 million assistance program for the group’s troubled Oklahoma City bank, with its merger into the Tulsa bank among the conditions. The FDIC called assistance the least costly option. The institution’s present stability belongs beside that history; longevity alone is a poor substitute for examining what happened along the way.
Expansion also required deliberate spending. In June 2018, BOK announced its CoBiz acquisition at approximately $1 billion, about three-quarters in stock and the rest in cash. The deal added a commercially focused franchise in Colorado and Arizona. By September, BOK expected approximately $44 million in pretax acquisition-related charges. The purchase closed October 1. Geography and expertise arrived with integration work attached.
Today, the family includes Bank of Oklahoma, Bank of Texas, Bank of Albuquerque and BOK Financial. It occupies the space between smaller relationship banks and national institutions such as JPMorgan Chase or Bank of America. The competitive claim is broad capabilities delivered through accessible specialists. Whether that works for an individual customer depends on the team, the terms and the problem.
The checkbook is a management decision
For businesses, Exchange makes the proposition tangible: account reporting, payment approvals, transfers and access permissions in one platform. The useful thing to copy is the sequence. Identify the bottleneck. Decide who can move money. Establish visibility and controls. Then choose the tools. Installing software without changing responsibilities leaves much of the original problem in place.
See the cash02
Set permissions03
Control payments
The relationship model has costs of its own: time spent sharing information, learning systems and comparing fees. A customer seeking only a simple account may place little value on a specialist team. A company needing international branch coverage may prefer a larger network. BOK’s healthcare partnership with ClearBalance, meanwhile, illustrates another route: bring an outside specialist into the offering when the problem calls for it.
That qualification matters in the latest results. BOK’s third-quarter 2026 overview reported $646 million in loan growth and 11.5% growth from a year earlier, while higher rates pressured mortgage banking and fixed-income trading. Diversification gives the company several sources of earnings; it does not make each source immune to the cycle. The practical test is whether the whole arrangement keeps serving customers when one part slows.
“We manage the company for the long term, not for any one quarter.”Stacy Kymes / Q3 2026 investor overview
BOK’s most useful idea is also its least flashy: complicated customers deserve informed questions. Beneath the loan sits a business. Beneath the payment sits a process. Knowing what is underneath is where a banker can start earning the relationship.
Follow the money
Explore BOK Financial, its newsroom and insights. Watch the Exchange platform introduction or visit the official YouTube channel.