Consider the two ends of a money transfer. At one end, somebody taps a screen. At the other, somebody needs spendable money. Between them sit different currencies, identity checks, banks, wallets and shop counters. The screen gets most of the attention. UniTeller Financial Services has spent its history working on the distance between those two people.
That makes this Banorte-owned company an interesting specimen in fintech. It operates its own consumer service, uLink. It also supplies the machinery that lets another institution offer international payments under its own name. Sometimes the company doing the work is the one the customer never thinks to look for.
- For institutions: payment processing, payout connections and partner-branded remittance services.
- For people and businesses: uLink transfers and uLinkbusiness payments.
- The useful distinction: a familiar brand can rent the infrastructure behind its send button.
The brand can stay yours
Take Elektra. A retailer accustomed to paying out remittances wanted a digital channel for sending them. According to UniTeller’s case study, their partnership began in 2020; a consumer platform followed in 2021. Elektra supplied a recognizable name. UniTeller supplied licensed transmission and the backend. The retailer’s American subsidiary, Fraternitas, operated as a digital agent.
The arrangement changes a business’s position in a transaction. Instead of meeting the family only when money arrives, it can meet the sender, too. That is the appeal of Digital Link, UniTeller’s white-label offering. An institution can use a branded application or connect its own interface to UniTeller’s processing capabilities.
“Our technology, licenses, and compliance. Your brand and customers.”
UniTeller’s description of Digital Link
The economics are deliberately shared: Digital Link advertises a revenue-sharing model. The practical trade is clear. A partner gives up some independence and shares the proceeds in exchange for using an established operation. For a bank or retailer with customer relationships already in place, that can be more useful than starting another software project.
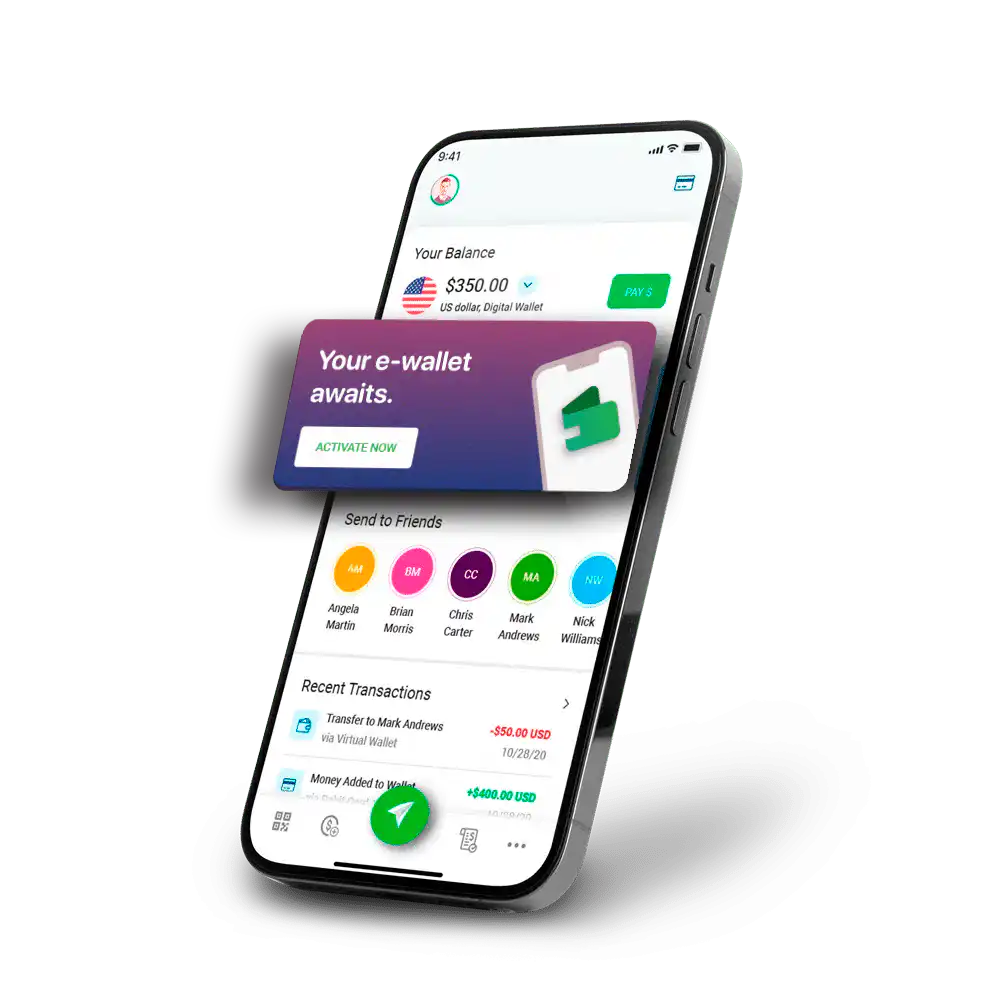
One connection, several ways to collect
UniTeller’s product names describe different entrances to the same problem. Cross-Border Pay connects institutions and payout providers. Cross-Border Send gives businesses and financial services firms access to international delivery routes. Instapago brings the service to retailers, with equipment and training support for agents. These are offers to operators with different starting points, rather than interchangeable consumer apps.
For a would-be partner, the first conversation should therefore be specific. Identify the country money leaves, the country it reaches, the funding method and the promised collection method. Then establish who handles identity checks, customer support and failed payments. A long destination list does not answer those operating questions. A small service that covers the right route can be more useful than broad coverage a customer cannot use.
The processing work includes anti-money-laundering checks, transaction screening, settlement and foreign exchange. Delivery can mean a credit to a bank account, a mobile wallet or cash collected locally. A beautiful mobile experience has limited value if the recipient’s preferred way to collect is missing.
That puts UniTeller alongside infrastructure providers such as Thunes and TerraPay. Its particular combination includes Banorte ownership, Latin American remittance roots, retail distribution and partner-branded digital services. The sensible comparison is the route a customer actually needs, the receiving method and the commercial terms.
You can buy a company. You also buy permission.
UniTeller began in 1994 serving transfers to Latin America. Banorte completed its purchase in January 2007; a securities prospectus put the price at $19 million. A later acquisition reveals how the business had changed. In August 2024, UniTeller completed its purchase of Uruguay-based MORE Payment Evolution.
In a 2024 interview with FXC Intelligence, CEO Alberto Guerra explained the attraction: additional licenses, broader geography and complementary products. UniTeller had been licensed in a handful of markets. MORE added permissions and operations across additional regions, including South America and Africa.
Network reach, not the number of countries with local origination licenses. Figures reported by FXC Intelligence in November 2024.
FXC reported annual send volume rising from $14 billion to $17 billion across the same period. Those figures describe money moved, rather than company revenue. The more useful lesson is organizational: entering a market requires permission and local capabilities as well as demand. Buying an operator can bring those pieces together.
The fine print was part of the product
There is a harder chapter. In December 2022, the Consumer Financial Protection Bureau issued an order over UniTeller’s refund and disclosure failures. The agency found that the company had failed to refund fees properly after certain delayed transfers, and had problems with cancellation information, availability dates, written procedures and record retention.
Civil penalty, plus approximately $30,000 in consumer redress and required compliance measures.
This matters particularly for a company selling compliance capabilities. Processing includes what happens after a promise goes wrong. A refund, a legible disclosure and a reliable complaint process belong in the same operating system as the transfer itself. The order required changes; it should not be mistaken for evidence that every subsequent process has been independently validated.
The next stop is payday
The business now reaches beyond family remittances. uLinkbusiness offers payments for supplier invoices, inventory, international service providers and payroll. Account creation is advertised as free. Buyers still need to evaluate the exchange rate and transfer charges for their particular payment.
In February 2026, UniTeller previewed an upcoming prepaid Mastercard linked to its uLink SuperApp. The announced functions connect payroll deposits, purchases and remittances. For customers underserved by conventional banking, the appeal is having those tasks close together.
For other businesses, the copyable idea is narrower: begin with the customer relationship you already have, then decide which licensed capabilities to rent. It depends on supported markets, workable margins and clear responsibility for mistakes. The test remains wonderfully concrete. Can the person at the other end use the money?