There is a peculiar kind of financial trouble that begins with having earned enough money. The work is finished. The payment is coming. The bill is here. Put those three events in the wrong order and a freelancer has a problem that a monthly income total can neatly conceal. Teller, the San Francisco venture behind helloteller.com, built its historical pitch around that awkward interval.
- The customer: independent workers juggling gigs, accounts and unpredictable receipts.
- The offer: connected financial tools, tax set-asides and interest-free advances.
- The detail that matters: its advertised paid time off involved repayment.
Consider the difference between a dashboard and a spare tire. One tells you something has gone wrong; the other gets you moving again. Teller wanted to offer both. Its archived pages put account visibility beside cash advances, tax withholding and protection against overdrafts. The organizing idea was practical: a person could keep working independently without doing every piece of financial administration independently, too.
01 First, pay people every day
The early proposition was narrower. Founders Space described a mobile service through which employers could give hourly workers daily cash incentives for useful behaviors. The employer wanted people to stay. The worker wanted more financial stability. Teller tried to make the same payment serve both interests.
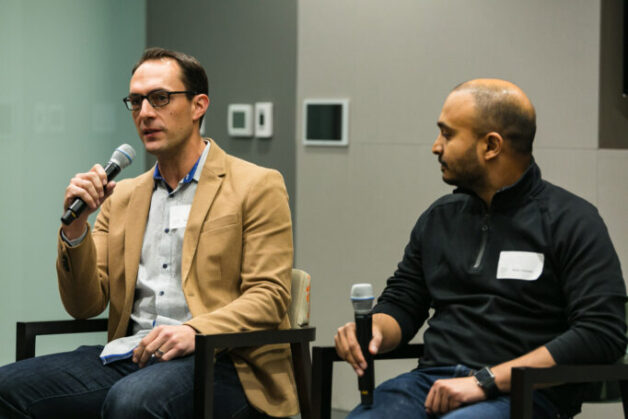
The organizer named three founders: chief executive Akshay Krishnaiah, chief revenue officer Akshay Peshave and chief technology officer Prince Nishchal. Krishnaiah had previously led product at PayPal Research Labs. That background helps locate the company’s expertise: payments and product design, applied to the everyday mechanics of getting through a working week.
There was something concrete behind the pitch. Founders Space reported a two-year Caspex contract covering 100 employees, alongside a Chick-fil-A pilot. A contract has a different evidentiary weight from a promising conversation. The pilot, meanwhile, should be read at its stated size: an experiment, with no company-wide rollout implied.
The commercial starting point matters. An employer buying a retention tool has a business reason to pay for it. A worker seeking financial support has a different reason to sign up. Teller’s descriptions show the company exploring both sides of that relationship.
By its August 2018 website snapshot, the pitch had widened to financial protection for independent contractors. That change is visible in the product descriptions. It suggests a different unit of design: the worker’s financial life across jobs, rather than an incentive attached to one employer.
02 The small print had a calendar
The most revealing feature was called “Paid Time Off.” On the archived page, Teller described typical payouts of about $200, followed by daily repayments over 30 days. The page quoted roughly $4 to $7 per day and said payments were interest-free. Rewards called Teller Treats could reduce the amount due.
Read that slowly. The product supplied money when a person stopped working, then required the money back. It could help someone cross a short interruption in earnings. Its mechanism was a repayable advance. That distinction changes the question a customer needs to ask, from how much time off is covered to whether the next month can carry the repayments.
Cash now. Daily repayments afterward.
Historical advertised terms; bars are schematic.
The May 2019 homepage made the borrowing proposition more explicit: advances up to $500, available without a paycheck, timesheet or credit check. Equipment repairs, time off and gaps between payments were suggested uses. Teller was addressing a customer whose working life did not reliably produce the paperwork of conventional employment.
“No paycheck. No time sheet. No credit check required.”
Teller’s archived homepage / May 2019
What did it cost? The 2018 site advertised initial benefits as free, with a release limited to 10,000 accounts. That was an offer boundary, not a customer count. Interest-free described the advance; it did not cancel repayment of the principal. The product’s attraction depended on that difference remaining clear.
03 One worker, several money trails
Alongside the advances sat a less theatrical problem: scattered information. Teller advertised connections across financial accounts, transaction search and tagging, forecasts of earnings and expenses, and an estimate of spendable balance. Its historical app screenshot looks like an inbox for money. Transactions from different providers share a single list.
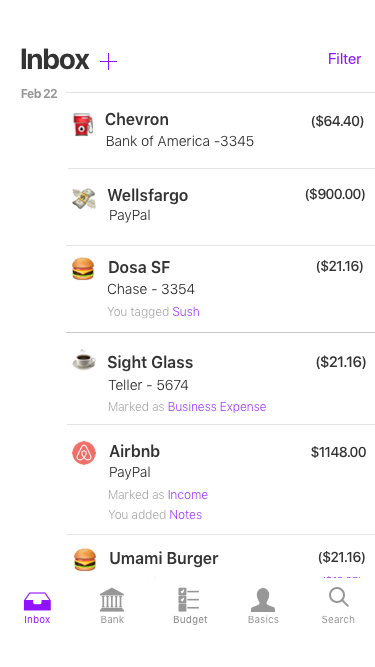
This mattered because a balance alone could tell an incomplete story. Some money might belong in a tax reserve. Some spending might be a business expense. Teller’s pitch combined seeing those distinctions with acting on them: withholding for taxes, moving funds and marking transactions.
The 2019 site also offered rewards for following a budget, withholding taxes, creating savings goals or using its debit card. Rewards could pay down advances. In product terms, that linked routine financial behavior to an immediate consequence a borrower could understand.
Names such as Uber, Lyft and Upwork appeared in the company’s descriptions of the people it hoped to serve. Their presence explained the intended market. It did not establish that those platforms bought Teller’s services. The proposition was to accompany a person between sources of work.
04 Build for the gap
Teller occupied the space between a personal-finance app and short-term financial support. Its competitive argument was the combination: understand the accounts, anticipate the squeeze, offer an action. A customer assembling separate banking, budgeting and advance services would have to do more of that coordination themselves.
There is a useful idea here for anyone building a product: identify the exact interval when the customer loses control. Then place the intervention there. A tax reserve works before the money is spent. An advance works before a temporary shortage stops someone earning. The timing is part of the service.
The constraint is equally concrete. A repayable bridge depends on income arriving on the far side. If earnings stay too low, or the interruption lasts too long, tomorrow’s repayment competes with tomorrow’s bills. Teller’s historical design makes that tradeoff visible. The calendar could be rearranged; the money still had to add up.