Consider the name on a debit card. It tells you where to tap, which app to open, perhaps where to ask for help. It does not always tell you who supplies the banking. In January 2023, Acorns announced another institution behind its checking accounts and cards: nbkc bank. A company known for turning spare change into investments had chosen a community bank in Kansas City. Suddenly, a local bank had another front door.
- Two routes to customers: its own accounts and mortgages, plus banking inside partner apps.
- A small physical footprint: four Kansas City-area branches, with digital services reaching nationwide.
- The useful lesson: simple banking depends on careful work behind the screen.
The name on the card
The Acorns arrangement is concrete. nbkc provides branded checking accounts and debit cards for qualifying customers, while Acorns supplies the experience that brings them in. nbkc became its second bank partner. The partnership makes a distinction easy to see: the company that designs a financial product and the bank supporting it can be different organizations.
There is a banker's logic underneath. In a 2021 account of its partnership business, nbkc described gaining deposits alongside interchange and program-management income. Fintech companies gained banking capabilities without becoming banks themselves. That helps explain why nbkc can court individual depositors and other financial brands at the same time.
A useful kind of small
Its history makes this less surprising. nbkc began in 1999 as Horizon National Bank, focused on online mortgage origination. It became National Bank of Kansas City in 2004 and nbkc in 2015. Digital distribution was already part of the business before the smartphone made a bank branch something you carried in your pocket.
In 2018, it launched Fountain City Fintech. The accelerator brought startups into contact with a potential banking partner. In a 2019 leadership interview, co-founder and then-CEO Brian Unruh and fintech strategist Zach Pettet described the long waits startups encountered at larger banks. Quick decisions mattered, including quick refusals when a company took regulatory obligations too lightly.
The attraction was also defensive. Speaking to BankBeat in 2024, CEO Michael Bartkoski recalled “that fear of absolute irrelevance.” Deposits offered a practical place to begin. The inference is straightforward: nbkc could bring its banking expertise to companies building new ways to reach customers, and learn from those companies in return.
Zero has a price list
For someone choosing a personal account, the backstage machinery matters less than the daily routine. The Everything Account combines spending, interest and savings goals. A customer can organize money for a future purchase without treating every goal as a separate banking relationship. Its Bank On certification for 2025-2026 recognizes an account meeting national standards for affordability, functionality and safety.
Small businesses get another proposition: a base checking account without a monthly maintenance fee or minimum opening deposit. That is useful for a young company whose balance moves around. The qualifications live in the business services price list. Sending wires costs money. So do optional tools. A headline price can be accurate while leaving the total bill dependent on how you operate.
monthly fee
Published pricing checked October 26, 2026. Optional services and other charges apply.
A business sending frequent international wires should do that arithmetic before switching. Someone who wants regular counter service outside Kansas City should count the distance, too. Against consumer alternatives such as Ally or Capital One, and business alternatives such as Grasshopper, nbkc’s appeal rests on the particular mix of access, services and costs a customer actually needs.
The spreadsheet ceiling
Behind a tidy app is a less photogenic question: who approved the advertisement? According to compliance-software provider Themis, nbkc identified a problem in January 2021. Partner approvals, complaints and issues traveled through email and spreadsheets. Visibility was poor; producing records for regulators involved extra work. Growth had made an ordinary office habit expensive.
nbkc adopted shared workflows for marketing reviews, complaints and issues. Themis reports approval turnaround fell 40%. That is a vendor-reported result, rather than an independent audit. The transferable idea is still useful: give each decision an owner, a record and a visible next step. Buying software only helps when people and partners actually use that common process.
The next step belongs in the app
A similar problem appeared after customers opened accounts. Opening was easy; becoming an active customer needed clearer instructions. In 2023, nbkc beta-tested Q2 Getting Started, placing a checklist in the digital dashboard for actions such as linking an outside account and setting security alerts.
“We knew we had to make things much more obvious and consumable for customers after account origination.”
Melissa Eggleston / Q2 case study, 2024
The lesson travels well beyond banking. A welcome email competes with everything else in an inbox. Instructions inside the product meet someone already trying to use it. nbkc’s experiment addressed the gap between acquiring an account and helping its owner do something useful.
Back to the mortgage desk
The bank is still working on its original business. On October 13, 2026, nbkc announced an investment in Vesta and adoption of its mortgage origination platform. The bank reported approximately $3 billion in 2025 mortgage originations. Its stated aim is to automate routine tasks and reduce handoffs, leaving lending staff more time for customers. Investment terms were undisclosed.
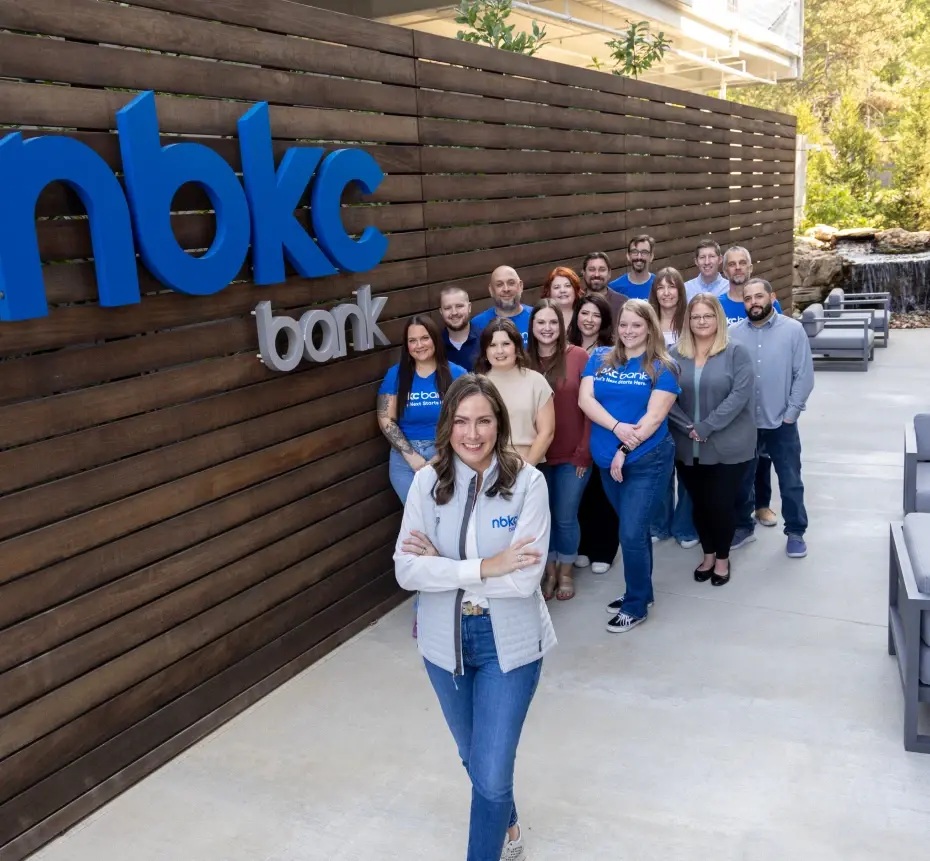
There is a physical commitment, too. nbkc bought a roughly 127,000-square-foot building in Overland Park, with a headquarters move planned for 2027. The digital bank still needs somewhere for people to work together. Its strategy keeps returning to that combination: reach more people through software, then organize the human work carefully enough to make the experience hold up.
Visit, watch, follow
Explore nbkc.com, the Everything Account, business checking and the bank’s news and blog.