At KentBank in Croatia, the problem was fifteen years old. That was how much historical data needed to follow the bank into a new system. Banking records are awkward luggage: leave something behind and the customer may discover it before you do. In a case study published by Mbanq, the migration took 110 days. The interesting part is what the bank wanted to escape: multiple modules, multiple databases, and the work of making them agree.
- Mbanq builds and runs banking infrastructure for institutions, fintechs and brands.
- The bundle reaches beyond software: payments, cards, onboarding, compliance workflows and disputes.
- The bank partner still matters. Buying the machinery does not remove the buyer’s responsibilities.
Fifteen years, packed into 110 days
“What we got with Mbanq was an integrated solution with everything in it”
FRANJO PRGIĆ / KENTBANK IT DIRECTOR
That is a customer’s account, published by the vendor, rather than an independent benchmark. Still, it identifies the practical prize: fewer separate systems between an employee and an answer. The same case study describes staff configuring products themselves through Mbanq’s Skyshaper tool, reducing their dependence on development work.
Mbanq dates its founding to 2016. CEO Vlad Lounegov and CTO Lars Rottweiler are among its co-founders. In a 2022 interview, Rottweiler described the frustration behind the business: banking systems had evolved from pre-internet foundations while regulatory demands kept accumulating. A new mobile interface could leave that older machinery untouched. Mbanq’s opportunity lay further inside.
The app is only the front door
Picture the ordinary act of opening an account. Someone must verify an identity, create the account, record its balance, connect payment services and watch subsequent activity. Later, someone must answer a complaint or replace a card. Mbanq sells technology and managed operations across that sequence. Its expertise sits where software engineering meets banking administration: the places a polished demonstration can conveniently skip.
The current product map has two main entrances. Nebula is core banking for regulated institutions. Mbanq Cloud serves builders adding financial products to regulated infrastructure. Its developer documentation divides the offering into APIs, a back-office interface and white-label self-service apps. Developers can build their own customer experience; clients can also start with branded applications. Eclipse handles card programs. Comet adds AI-related capabilities, having launched in 2024 around digital loan origination.
App · community · service↓MBANQ
Ledger · payments · operations↓FINANCIAL INSTITUTION
Banking relationship · oversight
The proposition is control over more of the operating chain. Mbanq currently emphasizes its proprietary core and in-house operations. Its history also includes partnerships: Galileo for card capabilities, Temenos for a credit-union offering and expanded BaaS collaboration, and SMEApprove for credit decisioning. “Integrated” describes the customer proposition; individual deployments still deserve careful questions about who supplies and operates each component.
Who pays for the plumbing?
Mbanq’s business is B2B software and services. Its customer buys a platform, operational help, or a combination. The alternative is a core-banking supplier plus separate integrations and teams. For a buyer, the meaningful comparison includes staffing, reconciliation and support alongside software fees. A cheap interface can sit above an expensive operation.
A publicly filed Accrew agreement makes the expense categories concrete: partner-bank fees, card processing, Mbanq fees, and card printing and fulfilment. It also describes a requested $1 million financing package, with a 5% initial co-pay and recovery through interchange. Those are customer-specific financing terms, not the price of launching any Mbanq program. They show why founders need a cash-flow plan alongside a feature list.
Capital matters to Mbanq, too. Temenos announced a minority investment in 2022. In July 2026, Mbanq announced an initial Swiss private-bank investment into a note program supporting lending and Earned Wage Access. The program’s capacity is up to $100 million. The initial investment’s size was undisclosed. Capacity measures room to finance future activity; it should not be counted as money already received.
From a bank to a community
Consider two customers. Sagicor Bank Barbados launched on Mbanq technology in 2023, with deposit products, cards, lending and back-office functionality. P2P launched in February 2025 for Brazilians living in the United States, offering dollar accounts, physical and virtual debit cards, and transfers. Mbanq reported that P2P arrived two months ahead of schedule. One is a bank serving an island; the other begins with a community crossing borders.
The latest example stretches the idea further. In October 2026, Mbanq announced work through TekNsol for Le Levier’s network of more than 40 Haitian credit unions. Initial capabilities include onboarding, accounts, loans, internal transfers and checks. Mobile banking and additional payment services are later phases. Shared infrastructure is the organizing idea, while each cooperative retains its own operations and member relationships.
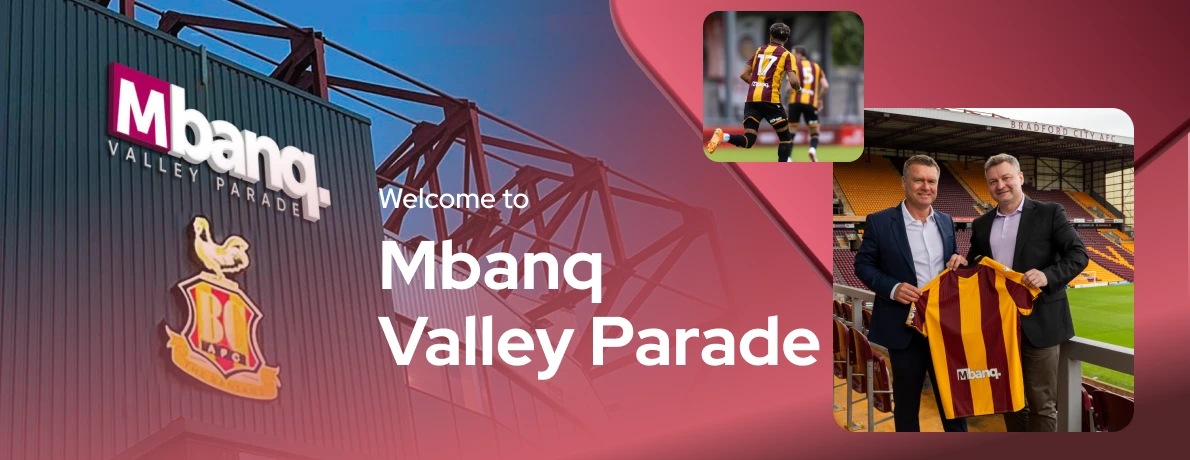
Then there is football. Mbanq’s 2026 Bradford City partnership put its name on Valley Parade and included plans for a UK operating presence. Possible supporter financial services remain subject to regulatory approvals. It is a conspicuous expression of Mbanq’s fan-economy ambitions: start with a relationship people already have, then explore financial tools that belong within it.
The part a founder can copy
The transferable idea is to standardize the machinery and specialize the relationship. P2P’s community focus gives that principle a concrete shape. A founder can begin by defining the customer, then mapping who owns onboarding, disputes, reconciliation and monitoring. Mbanq’s 2022 launch of managed dispute resolution makes the point nicely: an unauthorized transaction is part of the product experience, however distant it seems from designing the app.
The limits follow from those same responsibilities. Mbanq’s documentation requires clients to contract with a partner bank or financial institution. The Accrew agreement preserves customer compliance duties; screening tools do not guarantee protection from fraud. A viable program needs approval, operational discipline and enough revenue to support its costs. Mbanq offers a way to assemble and operate the service. The customer still needs a reason for people to use it.