Consider the insurance shopper who gets away. She visits a carrier’s website, checks a price, and decides to keep looking. The carrier has paid to get her there. Ordinarily, her departure looks like waste. But another insurer may want precisely the customer the first company cannot win. MediaAlpha’s marketplace connects those interests. The exit becomes a handoff. Someone bids for the next click.
- Carriers and agents buy prospects; publishers earn from referrals.
- Each shopper can attract a different bid, informed by data and expected value.
- Better matching helps, but carrier appetite and consumer trust set limits.
01 The tool the neighbors wanted
The business began in 2011 with Steve Yi, Eugene Nonko, and Ambrose Wang. Their backgrounds crossed travel comparison, software, and online marketing. Insurance offered a problem suited to that experience: a shopper’s details mattered enormously, yet advertising buyers often had limited visibility into what they were purchasing.
At first, the company operated QuoteLab. It acquired insurance shoppers and let advertisers bid differently depending on the information those shoppers supplied. Then something useful happened: other publishers asked whether the technology could work on their websites. In Yi’s 2014 account of the pivot, Esurance and All Web Leads became the two beta publishers. Demand for the tool helped reveal the larger business.
MediaAlpha publicly opened the exchange in March 2014, following a majority investment by White Mountains. That changed its reach. A bidding system built around one property became infrastructure for other people’s traffic.
02 A price for this particular shopper
Insurance carriers have different appetites. A prospect attractive to one may be unappealing to another. MediaAlpha gives buyers targeting across more than 35 consumer attributes, alongside predictive models and performance data. Rather than buying an undifferentiated bucket of people, a carrier can adjust what it pays for particular opportunities.
The advertiser tools offer source visibility, reporting, integrations, and managed support. On the other side, publishers can compare advertiser performance and monetize clicks, calls, and leads. A carrier can occupy both sides: buying customers it wants and referring visitors who do not convert. That overlap makes the market more interesting than a simple list of lead sellers.
Agents get a more immediate version of the proposition. They can buy leads and connect with shoppers, with controls over their spending. The Farmers Lead Marketplace’s published terms describe monthly budgets, daily caps, and managed pricing based on conversion probability. A purchased lead still needs follow-up; it does not arrive wearing a policy number.
Its competitive position sits between publishers and insurers. At the June 2026 William Blair conference, Yi described QuinStreet as a more direct marketplace competitor and EverQuote as a lead generator with its own traffic ecosystem. He also described ways the companies work together. These relationships can overlap: a business competing for an insurance marketing budget may also supply useful traffic. The practical difference for buyers is how much control and visibility they get over each source.
“Identify and acquire the right customers at the right price.”
Steve Yi · on predictive analytics
03 Two ways to count the money
MediaAlpha generally gets paid for a qualifying referral action. It need not wait for a policy sale. Prices vary with bidding and agreements, so there is no universal sticker price for a lead. The distinction matters to an agent: the bill can arrive even when the shopper never becomes a customer.
The company’s two transaction models also require careful reading. In the Open Marketplace, the buyer’s payment is revenue and the publisher’s share is a cost. In the Private Marketplace, partners contract directly and MediaAlpha records its platform fee. Dividing company revenue by total marketplace spend therefore produces a misleading picture of what it keeps.
Money transacted, money recorded, and profit are different things.
In its 2025 results, MediaAlpha reported more than 141 million consumer referrals and over 1,150 active partners, excluding agent partners. Referrals are neither unique people nor completed policies. The company also spent $21.4 million on product development that year.
The ownership history is worth separating from the operating economics. A 2019 recapitalization valued MediaAlpha at approximately $350 million; that was a transaction valuation, not a disclosed pile of new growth capital. In October 2020, the IPO was priced at $19 a share. The base offering included shares sold by the company and an existing shareholder, so even the offering’s headline value needs unpacking.
04 The buyers can step on the brake
A clever auction cannot manufacture an insurer’s desire to grow. In 2023, MediaAlpha’s revenue fell 15% to $388.1 million, while property and casualty transaction value fell 31%. Its net loss was $56.6 million. Yi connected the outlook for recovery to carriers restoring profitability and increasing marketing investment.
By July 2026, the company was reporting quarterly revenue of $316.9 million, up 26%. Better matching and stronger buyer demand can reinforce one another. But the earlier contraction supplies a useful boundary: an acquisition platform depends on customers who actually want to acquire.
05 A $45 million correction
The harder boundary concerns how shoppers enter the system. In 2025, the FTC alleged that MediaAlpha misled consumers seeking health insurance into providing personal information subsequently sold to telemarketers. The allegations included deceptive claims about coverage and government affiliation. MediaAlpha disputed the allegations and settled without admitting wrongdoing, agreeing to pay $45 million and strengthen disclosures, content review, and partner monitoring.
The court entered the settlement order in October 2025. This was an operational change as well as a financial cost. In its second-quarter 2025 shareholder letter, management said it had taken additional measures in under-65 health to address FTC concerns and identified Medicare as its primary health focus. The episode exposes a distinction every buyer should understand: a prospect’s willingness to click does not establish informed consent.
06 Buy the outcome you can measure
The lesson a marketer can copy is straightforward: follow the money through to the policy. Compare sources, measure conversion, and set bids against expected customer value. That approach needs reliable data, lawful consent, and people ready to handle the referral. Without those conditions, more volume can simply buy more disappointment.
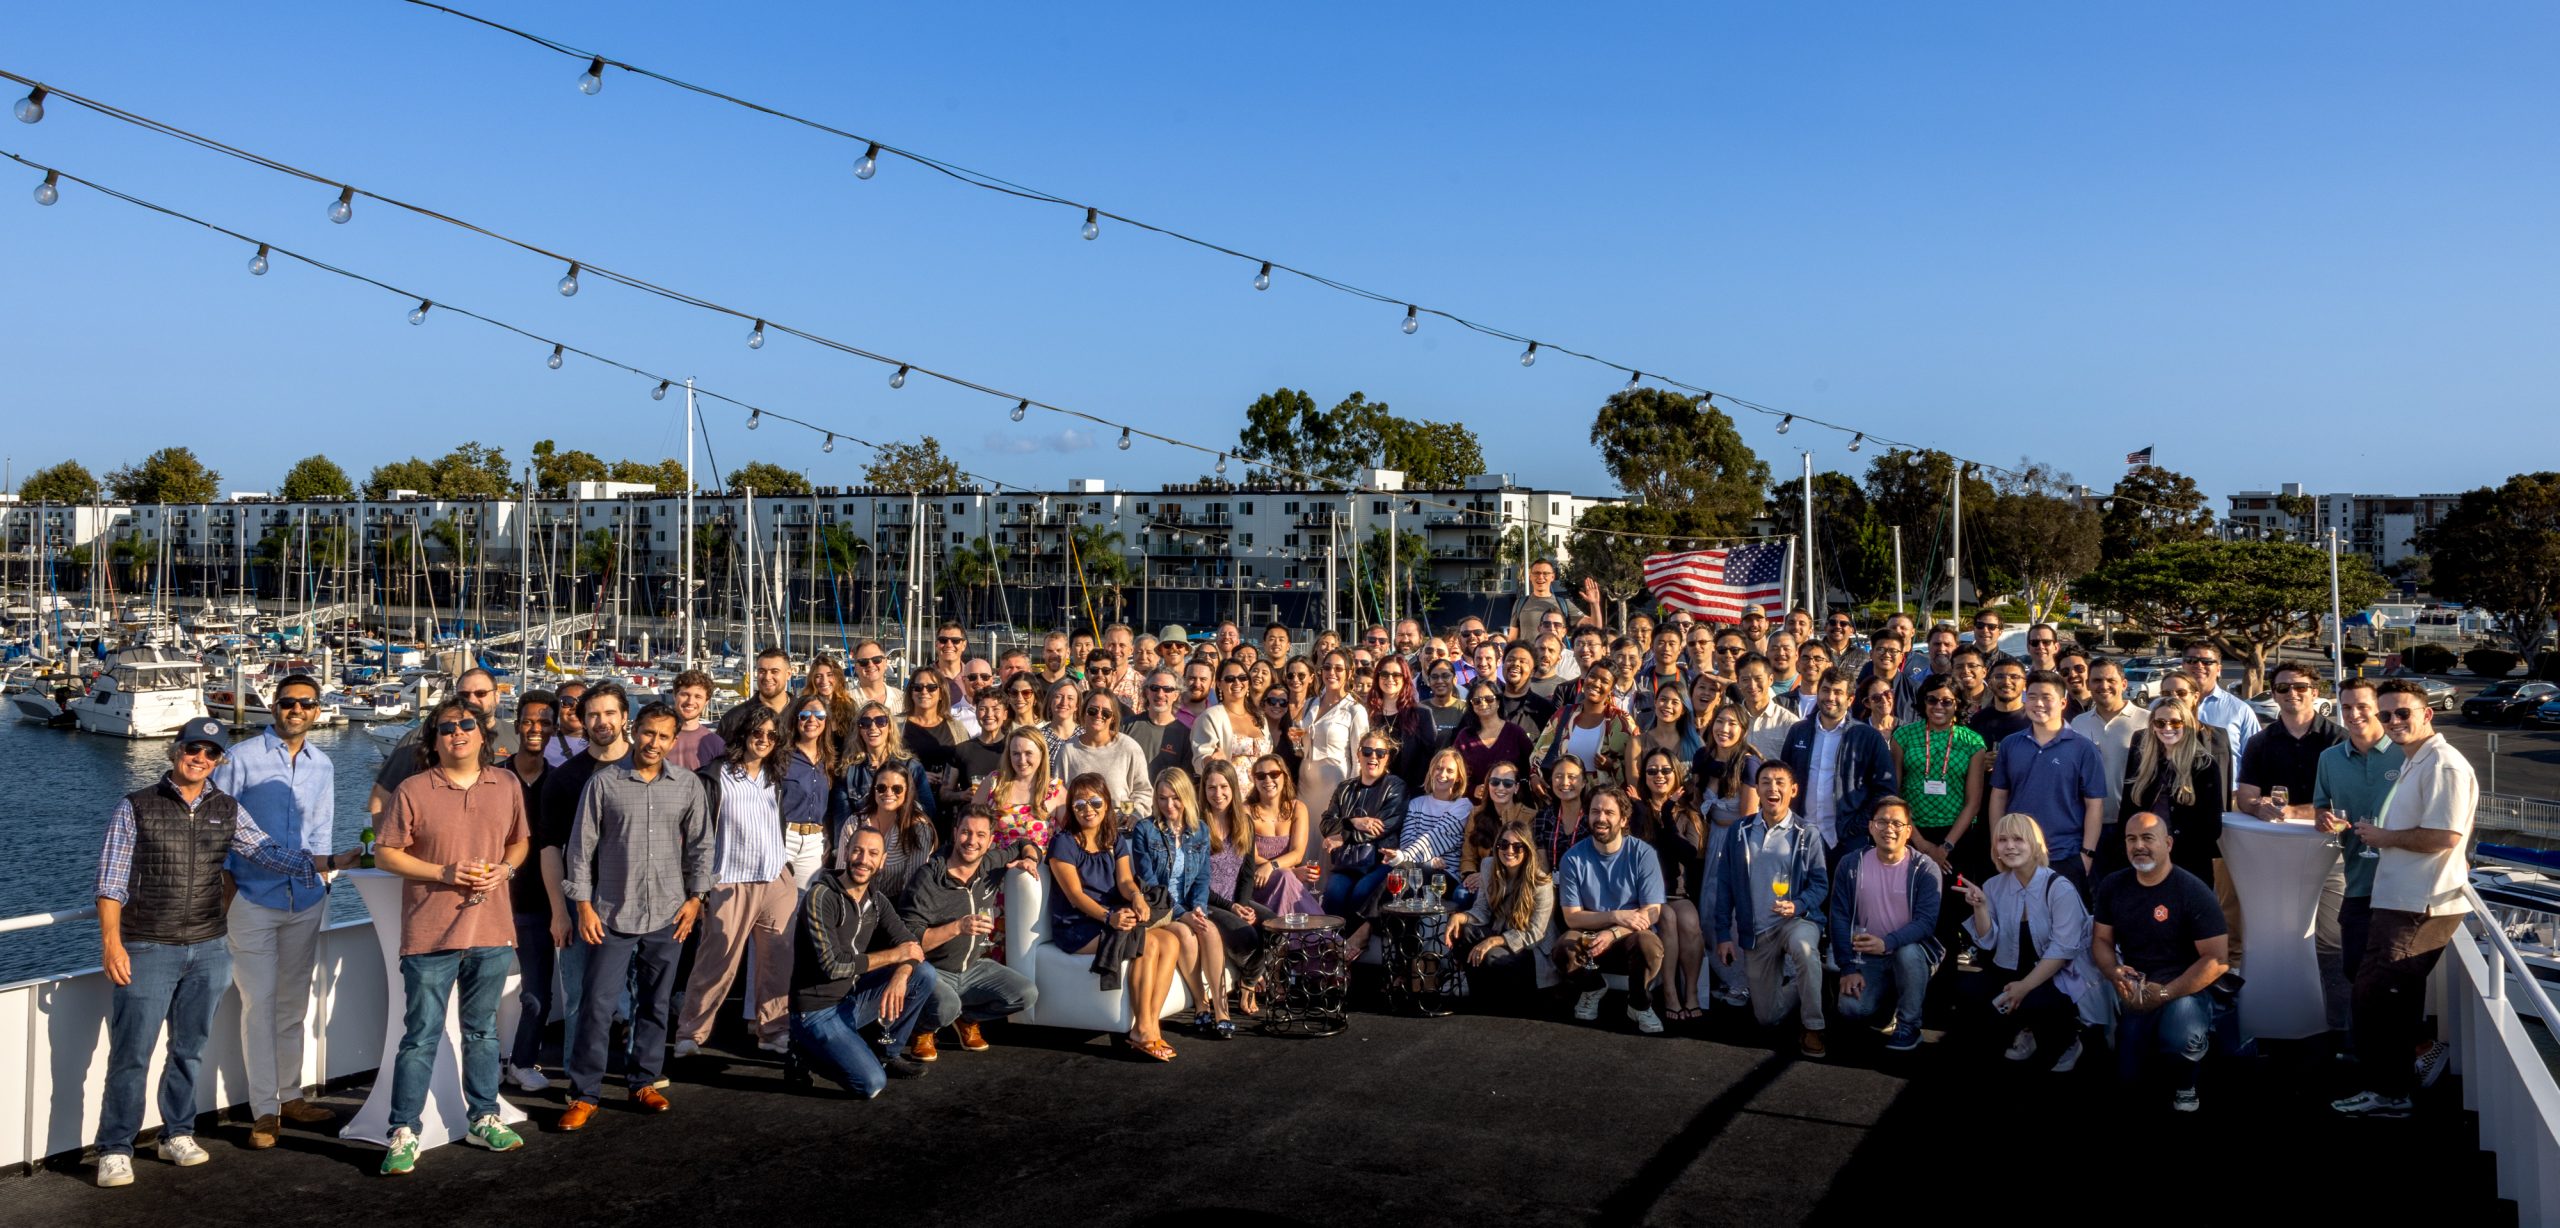
MediaAlpha’s stated workplace values emphasize curiosity, accountability, transparency, and long-term thinking. Its marketplace asks a similarly practical question: what is this particular introduction worth? The company has shown how much business can gather around that question. Its history also shows why the answer must include the shopper’s experience.