There is a curious problem with becoming famous for paying people well: everyone remembers the pay, and almost nobody remembers the work. In April 2015, Gravity Payments announced that its minimum salary would rise to $70,000 over three years. Thirty of its 120 employees stood to see their salaries double. A merchant-services company had become a conversation about how capitalism ought to behave.
- The work: card processing, terminals, online payments and software integrations for independent businesses.
- The price: a published 2.5% + $0.10 for qualified in-person transactions; other setups need their own quote.
- The distinction: payment technology paired with 24/7, U.S.-based human support.
- The useful question: what does the merchant save in money, retyping and time spent chasing help?
That last question gets less applause. It is also the one that keeps the lights on. A restaurant owner does not select a processor merely to admire its employment policies. The terminal has to work, the bill has to make sense, and the person answering the telephone has to understand why a queue of hungry customers is an emergency.
01 The arithmetic behind the applause
The wage announcement had a funding mechanism. Dan Price cut his own compensation from about $1.1 million to $70,000, and the company committed profits to the increases. The subtraction alone released roughly $1.03 million a year. That is a useful detail for anyone tempted to copy the headline: Gravity had an unusually large executive expense it could redirect.
There was a change of perspective, too. In Price’s own account, conversations about the cost of living made him reconsider whether employees could afford ordinary life on their salaries. He connected their financial security to the quality of service they could offer merchants. A company selling relief from payment headaches was asking its staff to work while carrying headaches of their own.
The first visible friction concerned fairness. Two employees left after the announcement, with objections to how the raises treated workers with different levels of responsibility. One departing employee’s complaint, reproduced in a 2015 Express-News commentary, was blunt:
“Now the people who were just clocking in and out were making the same as me.”A departing employee, 2015
A minimum can lift people while compressing the distance between them. An owner considering a similar policy has two conversations to conduct: what workers need to live, and how experience and responsibility will be recognized. A generous answer to the first does not automatically answer the second.
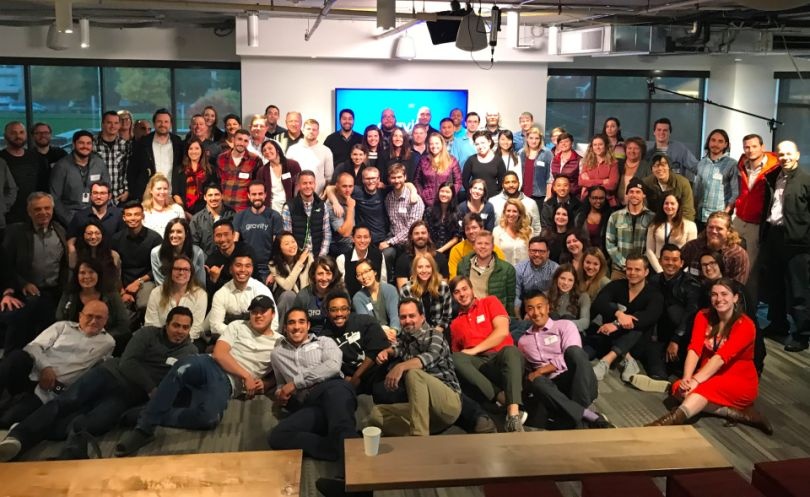
The company’s November 2025 retrospective reports revenue growth of 650% since the announcement and annual employee turnover falling from 22% to 6%. It also describes an $80,000 minimum introduced in 2022 and profit sharing from 2023. These are company-reported results, not a controlled experiment establishing what wages alone caused.
The pandemic supplied a harsher test. In March 2020, merchant activity collapsed and Gravity’s revenue fell by roughly half. Employees took temporary pay reductions; an August report described salaries being restored and noted a federal Paycheck Protection Program loan. Recurring transaction revenue is attractive until transactions stop recurring. Even a celebrated salary promise depends on cash.
02 A payment company lives in the awkward minutes
Gravity’s commercial territory is the independent business: restaurants, retailers, veterinary practices, bridal shops, professional services and nonprofits. Historical company materials described nearly 20,000 customers across all 50 states. The examples are revealing. These are organizations for which accepting money is necessary, but rarely the reason the owner opened the doors.
Consider a veterinary practice. A payment has to be accepted, matched to a bill and visible later when someone reconciles the day. If staff must copy amounts between systems, each extra step creates another opportunity for a mistake. Gravity offers integrated payments that connect acceptance with the business software already handling the work.
software
accepted
reported
Illustrative workflow. Compatibility depends on the merchant’s software and integration.
The company advertises round-the-clock, multilingual support based in the United States. Its proposition is partly technical and partly organizational: the merchant gets payment tools and people to help operate them. Alternatives include Square, Stripe and merchant-service providers attached to banks or independent sales organizations. A useful comparison starts with the actual workflow rather than the most handsome rate on a landing page.
Gravity remains a business beyond its founder. Tammi Kroll succeeded Price as CEO in 2022 amid misconduct allegations he denied. He returned as an adviser in 2024; a California charge was dismissed in 2025. Its current careers page names Kroll as CEO.
03 Ten cents can be a large number
The published flat rate is straightforward: 2.5% plus ten cents per qualified in-person transaction. On a $100 sale, that produces a $2.60 processing charge. On a $10 sale, it produces 35 cents, or 3.5% of the ticket. The fixed component makes small purchases proportionally more expensive.
Calculated from 2.5% + $0.10. Effective processing cost only; eligibility and other quoted costs matter.
Gravity explicitly says integrated payments and transactions where the customer is absent may not qualify for that rate. It also offers custom pricing. A merchant choosing online checkout should therefore obtain an online quote, rather than apply the countertop number to a different business.
Hardware is another line in the arithmetic. The device list includes a $115 Clover Go Gen 3, a $600 PAX A920 Pro and a Clover Flex Gen 4 starting at $750. Rentals are available by inquiry. The sensible comparison includes equipment, software, applicable account fees and the particular mix of transactions.
04 The card reader is only the beginning
Gravity acquired Boise-based Charge-it-Pro in 2017, then brought the brands together. Charge-it-Pro specialized in payment integrations for point-of-sale companies. The acquisition helps explain why a business associated with card processing also speaks the language of developers and software partners.
Its cloud integration product, emergepay, offers several ways to put payments into an application: a modal form, an embedded form, custom hosted fields and checkout. Apple Pay and Google Pay support sit alongside the card options. The company offers in-house development assistance and relationship managers for partners. This is useful when the business wants payments inside an existing application rather than a separate task at another screen.
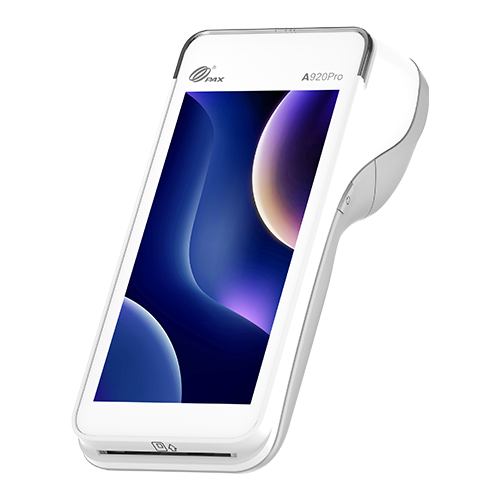
Gravity Dashboard handles the more everyday work: viewing transactions, checking batches and using a virtual terminal. The company describes that browser terminal as a way to keep accepting card payments if a physical reader goes down. It is a fallback worth understanding before the moment anyone needs it.
Payment links offer a different shortcut. The documentation distinguishes single-use links for a particular customer from reusable links that can be shared on a website or social account. A business can collect a payment without making every request into a new storefront project. Recurring billing and stored-payment features extend the same idea: fewer repeated chores between doing the work and getting paid.
05 The money arrives early; the repayment follows sales
Gravity Capital adds funding to the merchant relationship. The company describes a purchase of future receivables, with a fixed total payback and a percentage withheld from daily card sales. Its published illustration advances $10,000, adds a $2,000 financing fee and collects 10% of sales until $12,000 is repaid.
On a day with $500 in card sales, the illustration directs $50 to repayment and deposits $450. Actual terms depend on underwriting. The repayment amount moves with sales, which simplifies collection; the fee still has a cost, and the holdback still reduces cash reaching the merchant. Flexibility deserves arithmetic as much as enthusiasm.
06 What another owner can borrow
The most portable lesson is to examine the expensive little failures. How often do staff retype payment information? How long does reconciliation take? What happens when a terminal fails? Can the quoted rate survive comparison with a month of actual transactions? Gravity’s offerings are useful to the extent that they improve those answers.
The employment lesson also needs conditions. A company with little spare cash, no large executive salary to redirect and highly volatile revenue cannot assume that the same wage floor will finance itself. Gravity’s story supports asking better questions about pay and retention. It does not supply another owner’s budget.
For a merchant, the decision can stay pleasantly practical. Bring a processing statement, describe the software and the checkout, request a complete quote and test the support. The famous salary number explains why people remember Gravity. The next successful payment explains why a customer might stay.