There are easier businesses to explain at dinner. Duck Creek Technologies makes the software that helps an insurer decide what a risk costs, turn that decision into a policy, send the bill, collect the money and handle the claim when the roof meets the hailstone. Nobody applauds the policy-administration system when it works. When it cannot change a rate, absorb a catastrophe or explain a payment, everybody notices.
That obscurity is useful. It has allowed Duck Creek to spend 26 years accumulating the sort of domain knowledge that looks dull on a pitch deck and expensive in a replacement project. The company now offers an interconnected cloud suite for rating, policy, billing, payments, claims, distribution, customer service, data, reinsurance and loss control. In 2026 it added governed software agents and acquired Send Technology Solutions, an underwriting workbench for commercial and specialty insurance. The ambition is no longer merely to record insurance work. It is to help decide and route it.
The creek before the cloud
The origin is unusually literal. In 2000, Andy Yohn joined Doug, John and Becky Roller, Kerrick Tweedy, Barry Tate, Ken Toler and recent high-school graduate Devon Clasby in Missouri. They built a low-code rating engine for property-and-casualty insurers. The name came from a nearby creek. The important bit was not the bird. It was the bet that business specialists should be able to alter rates and product rules without waiting for engineers to rewrite the machine.
That problem grows nastier with scale. A carrier may sell personal auto in dozens of states, commercial packages to thousands of business types and specialty coverage whose details do not fit a standard template. Every jurisdiction brings forms, rates and rules. Every product change touches underwriting, billing, documents, distribution and reporting. A generic database can store the answer. It does not know the question.
Accenture bought the company in 2011 and expanded it into a wider insurance suite. Five years later, Apax Partners made an unsolicited approach and carved Duck Creek back out. Apax held 60 percent, Accenture kept 40 percent, about 1,000 Accenture employees moved with the business, and digital-distribution company Agencyport was folded in. Data specialist Yodil followed. What changed Duck Creek’s mind was not a single disaster. It was the market’s movement from homegrown and installed systems toward cloud services - and the realization that configurability did not help enough if every upgrade still became a project.
What $2.6 billion actually bought
Vista’s price is the cleanest public answer to “what did it cost?” The 2023 deal valued Duck Creek at roughly $2.6 billion. Shareholders received $19 in cash, a 46 percent premium to the last unaffected closing price and about 64 percent above the prior 30-day volume-weighted average. Earlier, the 2016 carve-out had delivered $196.2 million in net cash consideration to Accenture plus its retained stake. A $230 million private investment arrived in June 2020, followed by the IPO two months later.
The buyer got a business that reported $302.9 million in fiscal 2022 revenue and $169.3 million in SaaS annual recurring revenue, up 25 percent that year. It also got the unreported asset behind those figures: product definitions, regulatory content, integration patterns, implementation partners and the accumulated edge cases of real carriers. This is why insurance core software is hard to attack with a handsome interface. The interface is the lobby. The building is rules.
One core, many expensive moments
Duck Creek’s products can be bought separately, but the pitch strengthens when they share a model. Rating calculates the price. Policy creates and services the contract. Billing manages invoices, collections and commissions. Claims handles first notice of loss through settlement. Distribution manages agents and producers. Policyholder gives customers self-service access. Clarity joins core and external data on Snowflake. Reinsurance tracks what the carrier itself has insured away.
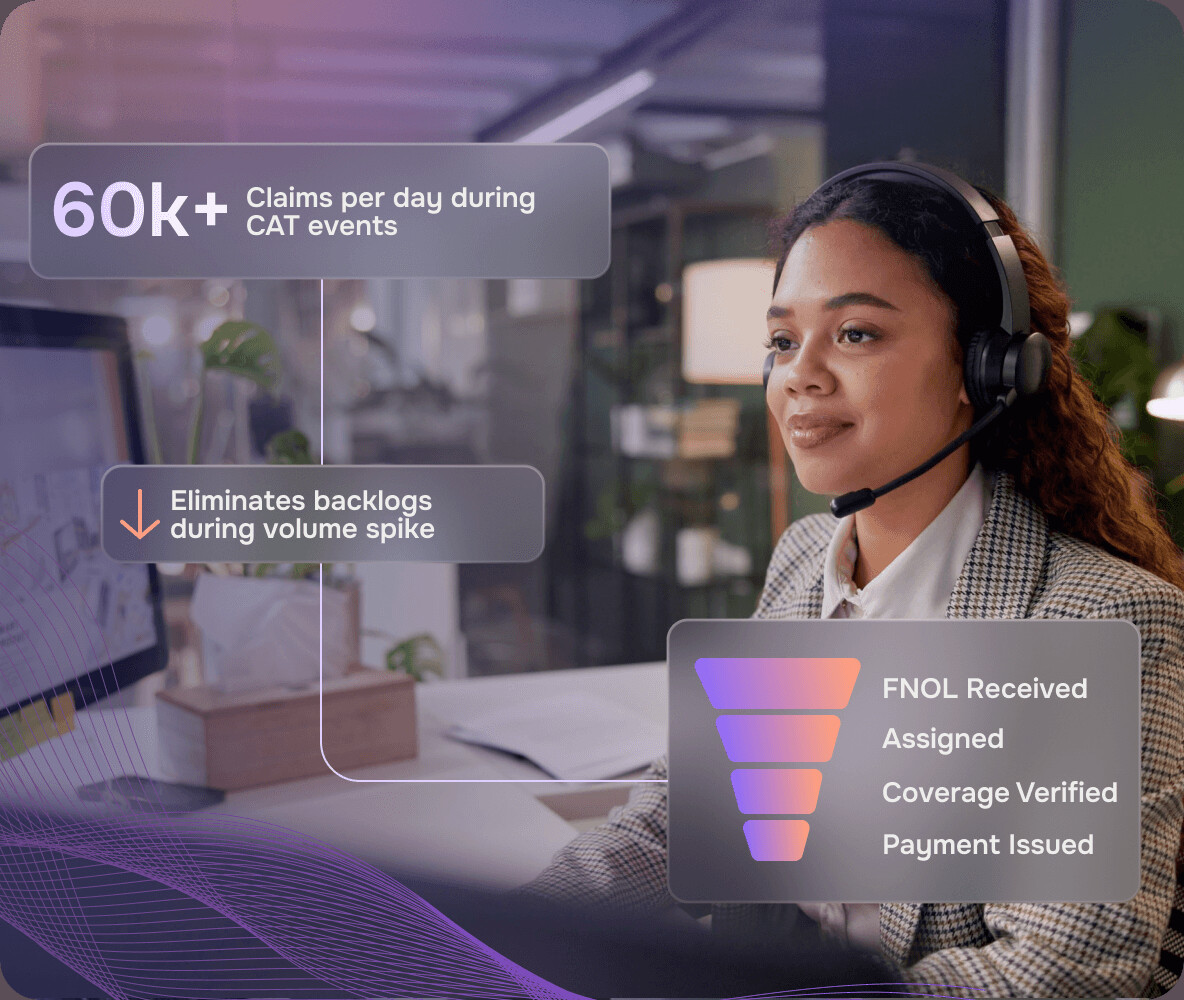
The cloud version, OnDemand, changes who carries the operational burden. Duck Creek manages delivery on Microsoft Azure and pushes toward an “evergreen” model rather than periodic, laborious upgrades. Its public product figures give a sense of the workload: more than 30 million claims processed through OnDemand, over 750,000 quotes a day through Rating, more than 100 electronic-funds-transfer payments a second in Billing, and over 60,000 claims in one day during a catastrophe event. These are company-reported measures, not universal customer outcomes, but they identify the job clearly: stay standing when ordinary work becomes extraordinary.
What failed first was the cadence
Legacy core systems do not always fail with a crash. More often, the first failure is organizational. A rate revision waits in an IT queue. A new state becomes a release plan. A product launch collects custom code until the next upgrade threatens to break it. Duck Creek’s answer was low-code configuration, reusable inheritance and packaged bureau content. The SaaS pivot added continuous delivery. The partner ecosystem added capacity for implementation.
That combination explains the company’s position against Guidewire, its closest broad rival, and suites from Sapiens, Majesco, EIS, Socotra, Fadata and OneShield. Duck Creek leans hard on product configurability, open APIs and packaged insurance content. Guidewire brings its own scale, installed base and cloud platform. Point solutions can go deeper in one workflow. A homegrown system offers control, at the price of maintaining every peculiar decision forever. The competition is not a beauty contest. It is a choice about which constraints an insurer wants to own.
Illustrative comparison of end-to-end platform breadth, not market share.
AI enters through the audit trail
Hardeep Gulati arrived as chief executive in October 2025 after a decade scaling education-software company PowerSchool. Longtime CEO Mike Jackowski moved to vice chair. By Formation 2026, Duck Creek was describing itself as an “intelligent core” and launching agents for underwriting, first notice of loss and product configuration. Its September 10 release was scheduled to add claims-document summaries with citations and natural-language analytics, all described as opt-in and auditable.
The restraint matters. Insurance decisions carry regulatory, financial and human consequences. A model that invents a coverage fact is not charming. It is a dispute. Duck Creek is therefore selling orchestration and governance as much as intelligence: agents receive insurance context, operate inside defined workflows and preserve human oversight. Its July purchase of Send closes another gap by connecting commercial-underwriting intake and triage to policy-core execution. Send remains available with other core systems, a pragmatic concession to carriers that will not replace everything at once.
What readers can copy
Start with a costly rule-changing bottleneck. Encode the domain logic. Make pieces adoptable on their own. Use partners for the services you cannot scale. Change delivery before the installed base turns into an anchor.
Where the playbook breaks
It struggles when the buyer lacks clean data, executive patience, process owners or implementation discipline. Low-code can still create a thicket of configuration. SaaS cannot rescue a transformation whose operating model stays untouched.
A useful company, under specific conditions
Duck Creek fits carriers that need enterprise controls but cannot freeze their products in enterprise time. Its sweet spot is a P&C or general insurer with multiple lines, regulatory variation, meaningful transaction volume and a willingness to standardize around a platform. The customer list ranges from regional mutuals to HDFC ERGO, Hagerty, QBE, Suncorp, GAINSCO and PURE. Duck Creek says more than half of the top 20 global P&C carriers use its software.
It will not work equally well everywhere. A tiny insurer may find the program too heavy. A carrier determined to preserve every legacy customization may reproduce the old core inside the new one. A digital startup with a narrow product and simple geography may move faster with a lighter platform. And no amount of agentic vocabulary fixes disputed data ownership, contradictory rules or a transformation led only by the technology department.
Duck Creek’s playbook, minus the private-equity bill
- Choose a narrow problem where domain rules change often and mistakes cost real money.
- Separate configurable business logic from the stable transaction engine.
- Broaden adjacently: rating to policy, policy to billing and claims, records to data and AI.
- Let customers adopt modules, but reward them when the modules share one foundation.
- Treat governance as a product feature, especially when automation starts making decisions.
The amusing thing about Duck Creek is how little the founding idea needed to change. The company around it changed repeatedly: independent startup, Accenture unit, private-equity carve-out, public company, Vista portfolio company. Delivery shifted from installed releases to cloud subscriptions. The product widened from rating to an operating layer. Now agents are being invited into the workflow. Yet the proposition remains recognizably Missouri circa 2000: insurance rules will change, so the software had better bend first.