A sofa has two prices. There is the number beside the photograph. And there is the number a buyer can fit into next month’s budget. For an online furniture retailer, the distance between those figures can be the distance between admiration and an order. Bread built its business inside that gap.
- The product: financing woven into a retailer’s shopping experience.
- The bet: answer the payment question before the customer reaches checkout.
- The twist: Alliance Data bought Bread for about $450 million, then adopted its name.
Consider Apt2B, the Los Angeles furniture seller. In a November 2021 case study, Bread Financial reported that Apt2B’s average order value was 28 percent higher with Bread Pay than with its previous financing provider. Customers could prequalify at several points along the shopping journey. Financing had become something the store could discuss while the shopper was still choosing the furniture.
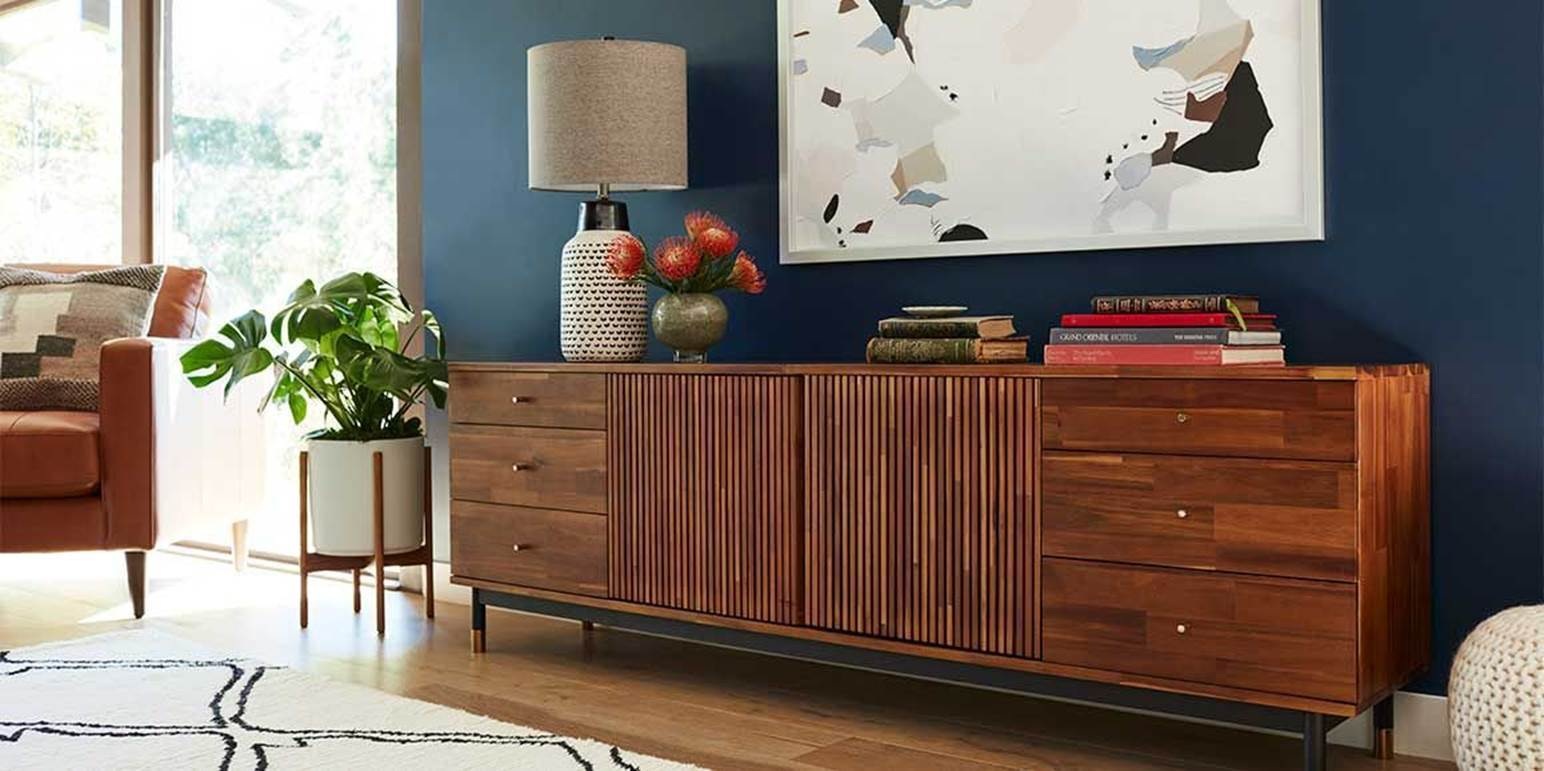
The button was the ending
Founded in New York in 2014 by Josh Abramowitz and Daniel Simon, Bread entered a market with a familiar proposition: buy something now, pay over time. Retailers had offered credit for generations. Bread’s opening was in the experience surrounding the loan. A website could show a payment option alongside the merchandise, with financing tailored to the merchant.
“Current private-label options were built for an offline world,” Abramowitz said in Bread’s 2017 funding announcement. That was the diagnosis. The product was a customizable digital financing system: different payment plans, different placements, and a shopping experience that could retain the retailer’s identity. Bread called it white-label technology. The merchant could call it keeping the customer.
Investor Menlo Ventures described this merchant-first approach as central to Bread’s product development, support and culture. The company wanted long relationships with retailers. Its pitch offered a useful distinction in a crowded payments market: a merchant could add lending capability while keeping its own brand at the center of the experience.
The other customer at the table
Bread therefore had two audiences. The retailer wanted completed orders and larger baskets. The shopper wanted a manageable payment schedule. Making those interests meet required more than attractive interface design. Someone had to assess the borrower, originate the loan, collect repayments and absorb losses when customers could not pay.
For the retailer, the expertise being purchased is a combination of software and credit operations. A furniture store can know everything about fabric and delivery without wanting to become a lender. Bread’s proposition puts those responsibilities into a payment relationship. The appealing customer experience depends on less visible work: integration, underwriting and servicing all have to function after the order arrives.
In Bread’s earlier years, its announcements identified Cross River Bank as the lender. Today, Bread Pay disclosures identify Comenity Capital Bank, a Bread Financial company. The technology sits at the point of purchase; banking sits behind it. Interest on applicable loans and merchant fees help support the economics, alongside the costs of funding, servicing and credit losses.
The parent’s 2024 annual report described installment loans typically running from three to 48 months. Its SplitPay product used four equal payments: one at purchase, followed by three at two-week intervals. Those are different commitments for different purchases. Approval and actual terms depend on the offer. A monthly figure becomes useful only when the buyer understands the full repayment obligation.
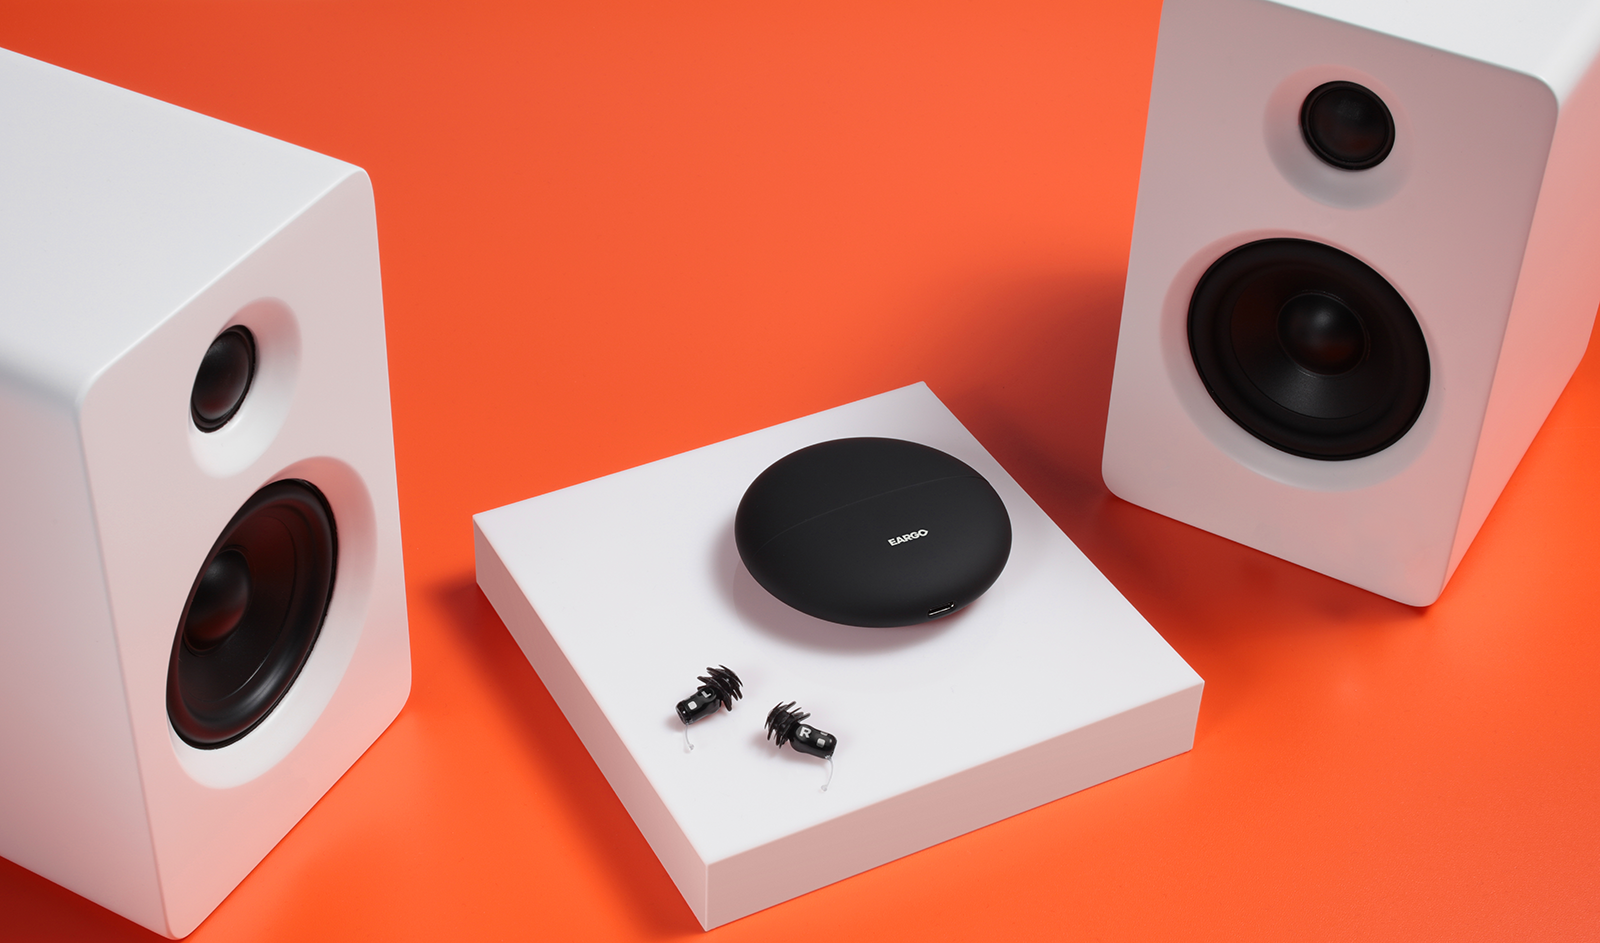
Eargo, the direct-to-consumer hearing-aid company, shows how far this model travels beyond sofas. A June 2020 company case study reported that 41 percent of Eargo sales used Bread financing. It also described using a zero-interest offer to promote a higher-priced product. Payment design was participating in the product launch itself.
A funding headline needs a second look
Building a lender takes capital of more than one kind. Bread announced $126 million in financing in August 2017, combining an equity round led by Menlo Ventures with a debt facility from Victory Park Capital. Calling all of that venture equity would miss an essential feature of lending: the company needs money to build software and money to support the lending business.
A September 2018 announcement added $60 million in equity, led by Kinnevik, taking total equity investment above $100 million. Bread said it would extend its capabilities across shopping channels and enter new verticals. That was an expansion of the original online proposition, following retailers as their customers moved between digital and physical shopping.
The merchant could call it keeping the customer.THE WHITE-LABEL BET
Then the incumbent bought the challenger. Alliance Data completed its acquisition in December 2020, bringing approximately 200 Bread employees and more than 400 existing clients into the group. Consideration had been valued at approximately $450 million at signing. The buyer gained digital installment technology to offer alongside its established retail-credit business.
When the buyer takes your name
In March 2022, Alliance Data became Bread Financial. Chief executive Ralph Andretta presented the change as part of a broader simplification around payments, lending and savings. He also pointed to the pandemic’s acceleration of digital shopping as validation of the company’s technology investment. The acquired startup’s name became the identity of the larger enterprise.
That history matters when reading today’s numbers. Bread the New York fintech and Bread Financial the Columbus-based parent are different scopes of business. The parent sells credit cards and savings products too. Bread Pay is the purchase-financing line. Its 2024 annual report described more than 1,300 small and midsize retailer and merchant relationships.
A bigger basket, measured carefully.
Average order value indexed to the previous provider = 100. Reported lift: 28%. One merchant’s comparison, not a guaranteed result.
Copy the placement. Check the economics.
The approach remains visible. An August 2026 Ari Bikes case study reported 19 percent higher average order value on financed purchases, using loan activity from June 2025 through June 2026. These are company-reported comparisons, not randomized experiments. Financing users may differ from other shoppers. Larger orders alone cannot establish how much extra profit financing created.
A sensible test would ask whether earlier financing messages change purchasing behavior, then compare the resulting margin after costs. It would also separate promotional offers from ordinary terms and financed orders from the overall business. That distinction protects against a tempting mistake: treating the customers who chose financing as though they were interchangeable with everyone who visited the site. A larger basket is a clue, not the whole answer.
The practical lesson is to make the payment conversation available while the buying decision is forming. Merchants can test placements, preserve a coherent experience and measure completed orders alongside costs. The approach is less useful when fees consume the margin or repayment stretches the buyer too far. Bread found a valuable question hiding beside the product photograph: how will you pay for it?