In November 2016, Bank of North Carolina announced a new look. Its cardinal would appear in flight, and its branches would gather under one name: BNC Bank. A company that had spent years buying other banks was finally putting a single identity over the doors. Less than three months later, it agreed to a deal that would replace those signs again.
That little collision of branding and banking gets to the interesting part of BNC. The name was negotiable. The relationship between a banker and a customer was supposed to survive. By September 2017, when the Pinnacle signs went up, nearly all BNC leadership had remained in the same or similar roles, according to the acquiring company.
- BNC served businesses and individuals across the Carolinas and Virginia.
- Acquisitions supplied scale; local bankers supplied the customer relationship.
- Pinnacle’s roughly $1.9 billion all-stock deal ended BNC’s independence in 2017.
A regional bank, one conversation at a time
Bank of North Carolina opened in Thomasville on December 3, 1991. Swope Montgomery and Rick Callicutt helped start it; Montgomery became its longtime chief executive, while Callicutt worked through lending and operating roles before succeeding him in 2013. The later corporate headquarters was in High Point. BNC Bancorp, formed in 2002, owned the operating bank.
Its customers were individuals and businesses, including small and middle-market companies. They needed places to keep operating cash, finance property, borrow for business and buy homes. The deposit menu was familiar: checking, savings, money-market accounts and certificates of deposit. This was banking’s everyday machinery, with consequential decisions attached.
The distinction BNC emphasized was access to people with local knowledge. Its financial statements described a strategy built around local affiliations and increasingly sophisticated delivery. Against national banks and other regional lenders, the pitch was personal attention backed by enough institutional capacity to handle a growing customer’s needs.
Consider what that means for a business owner. A deposit account can be compared on price. A lending relationship also depends on whether the banker understands the business and can get a decision made. BNC’s proposition connected the two. The analytical appeal is straightforward: familiarity might help retain a customer whose borrowing needs become larger and more complicated.
The acquisition machine needed fuel
After 2010, BNC became a persistent buyer. Its November 2016 brand announcement counted more than fifteen acquisitions since that year. Buying institutions brought offices, deposits, loans and entry into markets. It also brought the decidedly unromantic work of combining computer systems, managing credit and deciding which locations justified their expense.
One revealing number comes from 2012. BNC reported approximately $629 million in asset growth, yet its branch network increased by only one office. Alongside acquisitions, it closed unproductive offices and converted multiple acquired banks onto its core systems. The growth story included subtraction.
Year-end consolidated assets. Assets measure the balance sheet, not sales or the bank’s price tag.
Expansion required capital. Aquiline Capital Partners invested $35 million in 2010. In June 2012, BNC announced a $72.5 million capital raise led by Aquiline with eighteen other new and existing investors. The money was intended to support expansion and make use of infrastructure already built.
There was a less obvious financing choice, too. In 2012, Montgomery told American Banker that BNC intended to retain its government-program capital despite obtaining private investment. He regarded it as relatively inexpensive funding for growth. The strategy depended on the cost and regulatory treatment of the money, not merely its availability.
“We consider it fairly inexpensive capital that still counts as Tier 1.”Swope Montgomery · June 2012
Permission was part of the product
The engine did encounter friction. In 2016, pending acquisitions drew challenges over minority-lending practices. The Federal Reserve’s High Point Bank review considered public objections, fair-lending compliance and community needs. Its order described a compliance plan and an acceptable supplement, alongside offerings intended to reach unbanked and underbanked customers.
Those included a New Beginnings deposit account and an affordable mortgage product. The Board approved the High Point transaction in October. These details matter because a bank cannot expand simply by finding a seller and agreeing a price. Its treatment of the communities it serves is part of the permission to grow.
The underlying economics also imposed limits. BNC earned primarily from the difference between interest received on loans and securities and interest paid for funding, supplemented by fees. Loan losses, expensive deposits or weak real estate could consume that spread. Acquisition skill did not remove credit risk. The practical lesson is to budget for compliance and integration alongside the purchase itself.
The buyer became the next chapter
By late 2016, BNC had become a plausible partner for another acquisitive lender: Nashville-based Pinnacle. The merger filing records an introductory meeting between executives in September. Their discussions covered management philosophy and the possible benefits of combining. This was a deliberate strategic process, rather than a rescue announced after a sudden collapse.
The agreement announced in January 2017 valued BNC at approximately $1.9 billion in stock. That figure was an acquisition value, distinct from both the bank’s assets and its earlier capital raises. The merger closed June 16. Bank of North Carolina merged into Pinnacle Bank; Callicutt became chairman of the Carolinas and Virginia region.
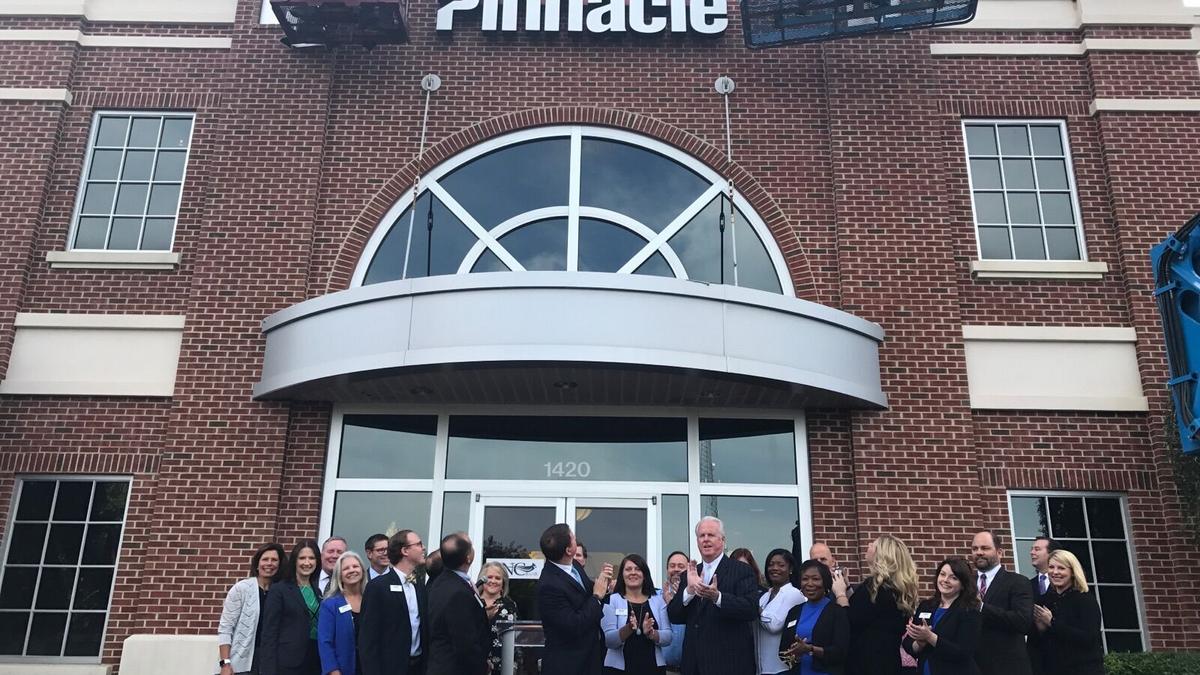
Callicutt publicly identified continued local authority as a reason the combination made sense. Pinnacle wanted BNC’s markets, while promising that regional bankers could keep running their offices with local knowledge. By September 25, the name had changed. Systems and operational conversions continued through the year.
For anyone studying how companies grow, the transferable idea is precise: identify which decisions customers value locally before centralizing the business around them. It requires capable people, capital and discipline. If acquisitions drive away those people or overwhelm the systems supporting them, the logic weakens. BNC’s history leaves that useful question behind every fresh bank sign: who still has the authority to help?