Bill Barhydt’s first encounter with Bitcoin did not produce instant devotion. He read the white paper, doubted that its proposal could work, and put it aside. Other people on a mailing list prodded him to look again. The idea kept bothering him: a network of computers might solve a problem that had frustrated earlier attempts at digital cash. Skepticism, in this case, was a fairly productive opening position.
He was already working on cross-border payments. Money had an annoying habit of encountering obstacles that information could sail past. A message could travel around the world while a transfer waited for permission, an intermediary or a convenient opening hour. For someone whose working life had passed through cryptography, Wall Street and Netscape, that discrepancy was difficult to leave alone.
Abra grew out of that irritation. Founded in 2014, it would change shape repeatedly, from a remittance proposition to a broader cryptocurrency business and then toward wealth management. The route includes a public debut at a startup competition, regulatory settlements and a proposed stock-market transaction. Barhydt has spent years arguing that financial infrastructure can change. His own company supplies a rather demanding test of that proposition.
A computer before a career
Barhydt was born in the Bronx, into a family with Italian immigrant roots. His father brought home a TRS-80 and taught him BASIC when he was 11. He went on to teach himself other programming languages. The machine gave a mathematically inclined child something unusually satisfying: instructions could become actions, and a sufficiently patient person could work out how.
He graduated from Stevens Institute of Technology in 1990. His early career included research work at the CIA and NASA’s Ames Research Center, followed by fixed-income work at Goldman Sachs. Each institution dealt with a different version of a familiar difficulty: how to make complicated systems behave reliably when the consequences matter.
In a later interview, he described secure-messaging cryptography work at the CIA and a period of study at Stanford while working at Ames. He said he left Stanford before finishing and went to Goldman. His biography resists the tidy educational shorthand sometimes applied to technology founders. There were several rooms, several kinds of work, and a willingness to walk into the next one.
When the browser met the bank
At Netscape, Barhydt worked on the infrastructure and commercial relationships of the early internet, including banking and telecommunications. These were years when putting a bank online was a substantial undertaking. Encryption and certificate systems helped make a browser a place where people could transact, rather than merely look around.
His subsequent ventures included WebSentric, Sennari and Boom Financial. The subjects ranged from online collaboration to mobile entertainment and mobile money. The list can look restless on a résumé. In practice, it traces the expansion of what a connected device could do: communicate, play, transact.
By the time he was running m-Via, the mobile-money business associated with Boom, the intended customer was often a migrant worker sending funds to family. A U.S. State Department speaker biography described that mission in practical terms: mobile transfers and financial inclusion. The grand question about the future of money had a smaller, more immediate counterpart. Could someone get paid, send something home and leave enough intact to make the effort worthwhile?
Different jobs. A recurring interest in the network.
- ResearchCIA / NASA
- MarketsGoldman Sachs
- InternetNetscape
- MoneyBoom / Abra
The cryptocurrency you were not meant to notice
Barhydt spoke about Bitcoin at TED University in 2012. The recording, later released by TED Archive, explored a decentralized currency and the possibility of monetary stability outside the usual arrangements. In 2022, he recalled that the talk had fallen on his birthday. Some people mark the occasion with dinner; his anniversary post revisited a monetary experiment.
Abra’s early consumer proposition tried to spare users a course in cryptography. A person would see familiar currencies while Bitcoin helped do the work underneath. In a 2017 interview, Barhydt described the experience this way: “Think of it like Venmo but cross-border.” An international ambition had acquired a description short enough to survive a conversation.
The early model also included tellers who could help people exchange cash and digital value. A teller was a human connection between the application and the world where notes still changed hands. That detail matters. Software could alter the route, but getting money into someone’s pocket remained an earthly business.
Abra won the 2015 Launch Festival competition, with a $250,000 investment from the Launch Fund attached to the award. On a stage, a money-transfer app could be demonstrated in minutes. Beyond the stage, adoption required habits, trust and access. Those are less cooperative materials than a presentation remote.
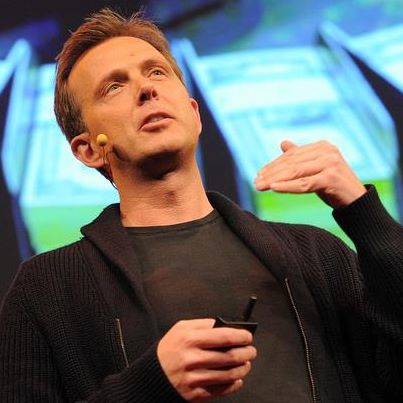
Speaking photo published with his 2017 Reason interview. Photo: Abra.
“Think of it like Venmo but cross-border.”Bill Barhydt, describing Abra in 2017
The part no demonstration can settle
The later Abra story includes a harder chapter. In June 2024, 25 state financial regulators announced a settlement with Abra entities and Barhydt over unlicensed money-transmission activity. The settlement required the return of remaining virtual assets to affected U.S. Trade customers, with up to $82.1 million to be returned under its terms.
Barhydt also accepted a five-year restriction on participating in the affairs of money transmitters or money-services businesses licensed, or required to be licensed, in the settling states, apart from passive investment. That is a specific restriction on a specific kind of business. The Texas consent order expressly says the provision is not intended to disqualify him from investment-adviser or certain other securities registrations.
A separate federal case concerned Abra Earn, the retail crypto-lending product. In January 2025, a court ordered Plutus Lending, doing business as Abra, to pay a $1.65 million civil penalty. The company had settled the SEC’s allegations without admitting or denying them. The judgment also imposed a permanent injunction.
These events change how the earlier promises must be read. A smoother transfer or an elegant application cannot, by itself, establish that the business around it meets its obligations. For customers, the legal structure is part of the product. The fine print has a habit of becoming the main text.
Multistate money-transmission settlement involving Abra entities and Barhydt.
$1.65 million civil penalty against Plutus Lending in the SEC’s Abra Earn case.
A different room, with different questions
Abra now presents itself as a digital-asset wealth-management platform serving institutions, advisers and private clients. Its offerings include custody, trading, lending and investment strategies. Abra Capital Management operates as an SEC-registered investment adviser; registration does not imply SEC endorsement. The company’s present language places considerable weight on account separation and the custody of client assets.
By September 2026, Abra had announced an expanded Fireblocks relationship intended to place eligible strategy tokens into qualified custody at Fireblocks Trust Company. In August, it announced Kiln infrastructure for Solana staking. Both developments concern the machinery beneath a managed portfolio: who operates it, where assets sit and how clients can see what is happening.
The customer conversation has changed with the business. In a March 2026 discussion with Anthony Pompliano, Barhydt described advisers who once needed an elementary explanation of Bitcoin now asking about clients borrowing against holdings. His example captures a useful shift in attention. Curiosity about an unfamiliar asset becomes a question about how to handle it.
He also chairs the board of Algorand Foundation US, Inc. That role puts him alongside people working on another part of blockchain infrastructure. Across his public appearances, the recurring interests are access, settlement, custody and the movement of conventional assets onto digital networks. The market-price conversation is loud; the operational conversation has more paperwork.
- 2014Founded around a new approach to money transfer
- 2015Launch Festival win
- 2024Multistate regulatory settlement
- 2026Wealth management, custody partnerships and a proposed public combination
A listing is another beginning
On March 16, 2026, Abra announced an agreement to combine with New Providence Acquisition Corp. III. The proposed transaction used a $750 million pre-money equity valuation for Abra and contemplated a Nasdaq listing under ABRX. It described up to $300 million in trust cash, subject to shareholder redemptions. Those are announced deal terms, rather than cash already delivered or a completed listing.
The intended audience included institutions, family offices, registered investment advisers and wealthy individual investors. Barhydt framed the ambition around bringing digital-asset services to investors worldwide within a regulated framework. The distance from the original remittance pitch is substantial. The recurring hope is still that a different technical foundation can change who gets access to financial services.
His enthusiasm for new tools extends inside the business. In the March conversation, he described using AI to prototype features, test messaging and run analysis, including an internal assistant he called Jarvis. He also said AI did not touch client money at Abra at that time. Even a founder pleased with faster development had drawn a line around what the tools were handling.
On October 8, 2026, Abra listed another Pompliano interview, this time under a headline asking whether Bitcoin was headed to $300,000. Price predictions attract an audience. They also tend to obscure the more revealing biographical question: what has someone kept trying to build while the price changed?
For Barhydt, the answer stretches from a home computer to browser security, from migrant remittances to managed digital assets. The record contains inventions, reinventions and consequential regulatory failures. It gives his present ambitions both a history and a burden of proof.
The childhood programmer learned that instructions could make a machine do something useful. Finance adds people who need their money back, rules that vary by jurisdiction and trust that cannot be installed with an update. Barhydt is still working on the gap between what a network can technically carry and what a person can safely use. That gap has kept him occupied for a long time.
Abra’s announced pre-money equity valuation.
A proposed transaction, subject to closing conditions.