Tom Broughton’s first job involved rolling pennies at his grandfather’s bank in Andalusia, Alabama. He was eleven. It is an admirably literal beginning for a banker: before there could be a balance sheet, somebody had to count the money. Decades later, after helping build one Birmingham bank and working inside the company that bought it, he would start another. The second venture gave him a chance to decide which parts of banking deserved to come along.
That venture was ServisFirst, opened in May 2005 with $35 million in capital. Its founder had already enjoyed the sort of career that might reasonably end with a comfortable chair. Instead, he chose another beginning. There is a particular restlessness in that decision. Experience had given him a position, but it had also given him ideas about how the work could be done.
Today, Thomas Ashford Broughton III is chairman, president and chief executive of the bank and its holding company. Around Birmingham, the shorter version is Tom. The formal name suits a prospectus. The familiar one suits a business in which a customer would rather know whom to call.
Pennies before the prospectus
Broughton grew up in Andalusia, in southern Alabama, with banking already part of the family vocabulary. His father, grandfather and uncle were bankers. As a schoolboy, he said he wanted to be a banker while classmates named the occupations children usually prefer. His early work in the family bank extended through afternoons and summers. Banking arrived as something people did, long before it became a title.
He went on to study finance at the University of Alabama and earned an MBA at Northwestern University’s Kellogg graduate management school. The education took him beyond Alabama; his professional banking career remained based in the Birmingham area. That continuity is a feature of his story. He has changed institutions and responsibilities without changing the city around which his working life is organized.
A childhood in a bank does not explain every later decision. It does, however, give the subsequent career an unusually long introduction. By the time he was responsible for raising capital and recruiting colleagues, the industry had been familiar for years. Starting a bank meant revisiting a business he knew from the smallest denominations upward.
The first bank was an education of its own
In 1985, Broughton helped establish First Commercial Bank and became its president. Synovus acquired the institution in 1992. He stayed as president and became its chief executive, then moved into regional leadership at Synovus. In 1998, his responsibilities included Alabama and Florida; in 2001, the region shifted to Alabama, Tennessee and parts of Georgia.
He left Synovus in August 2004. ServisFirst followed the next year. The interval gives retirement a rather elastic definition. More seriously, it marks a founder’s opportunity to apply lessons accumulated inside both a smaller bank and a larger organization. A second attempt can begin with fewer illusions about where the difficult work lives.
One finding helped focus his thinking. During his Synovus years, a customer revenue analysis showed that 4% of customers accounted for 90% of revenue. That historical analysis was about the operation he was examining then. Its importance to ServisFirst lies in the question it raised: what would a bank look like if it organized more deliberately around those productive business relationships?
The appeal of a fresh charter was practical. Broughton could choose the customer focus, the people and the operating habits together. A familiar industry still offered room for a different arrangement. The second bank began with the advantage, and the burden, of knowing what he wanted to improve.
The useful discipline of a smaller menu
ServisFirst concentrated on business banking and experienced bankers, with a limited branch footprint. The logic was that a business owner needed access to capable people and useful services, while routine transactions could happen remotely. An imposing lobby might be pleasant. It could not answer a lending question on its own.
“We don’t try to be all things to all people.”
Tom Broughton
There is an operational commitment inside that short sentence. Every additional activity needs people, systems and attention. Choosing a customer group gives the bank a way to judge what belongs in its offering. It also makes the proposition easier for a banker to explain across a desk. Simplicity has to survive the temptation to add just one more thing.
The focus did permit a related expansion. ServisFirst introduced correspondent banking in March 2011, providing services to other banks. By July 2025, that business served nearly 390 downstream banks in 30 states. Rodney Rushing helped develop it. Credit, payments and other services allowed smaller institutions to offer customers capabilities they might struggle to supply alone.
That extension followed the existing pattern: find a customer whose needs fit the organization’s expertise. The business customer and the community bank are different clients, but both may need a knowledgeable counterpart who can solve a specific problem. For Broughton, the discipline lies in keeping the reasons for an addition clear.
Local judgment, with a Birmingham backstop
A bank built around experienced people has to persuade them to join. Andy Kattos, who had known Broughton at First Commercial, recalled a recruiting breakfast in Birmingham in autumn 2005. Broughton arrived in shorts and flip-flops. The informality makes a pleasing footnote to a profession so generously supplied with ties. The conversation, however, concerned a serious change of employer and the prospects of a young bank.
Recruitment remained central to how ServisFirst entered markets. Broughton looked for bankers who could build local relationships. His public description of the approach left room for opportunity: “We’re going to look for opportunities.” The map followed available people and suitable markets, rather than requiring every opportunity to obey an elaborate expansion calendar.
Regional leaders receive authority to make lending decisions within limits. Larger requests can go to Birmingham, where senior credit leadership and Broughton or Rushing review them. The structure puts judgment near the customer while retaining a place for escalation. It gives the person who knows the relationship something useful to do with that knowledge.
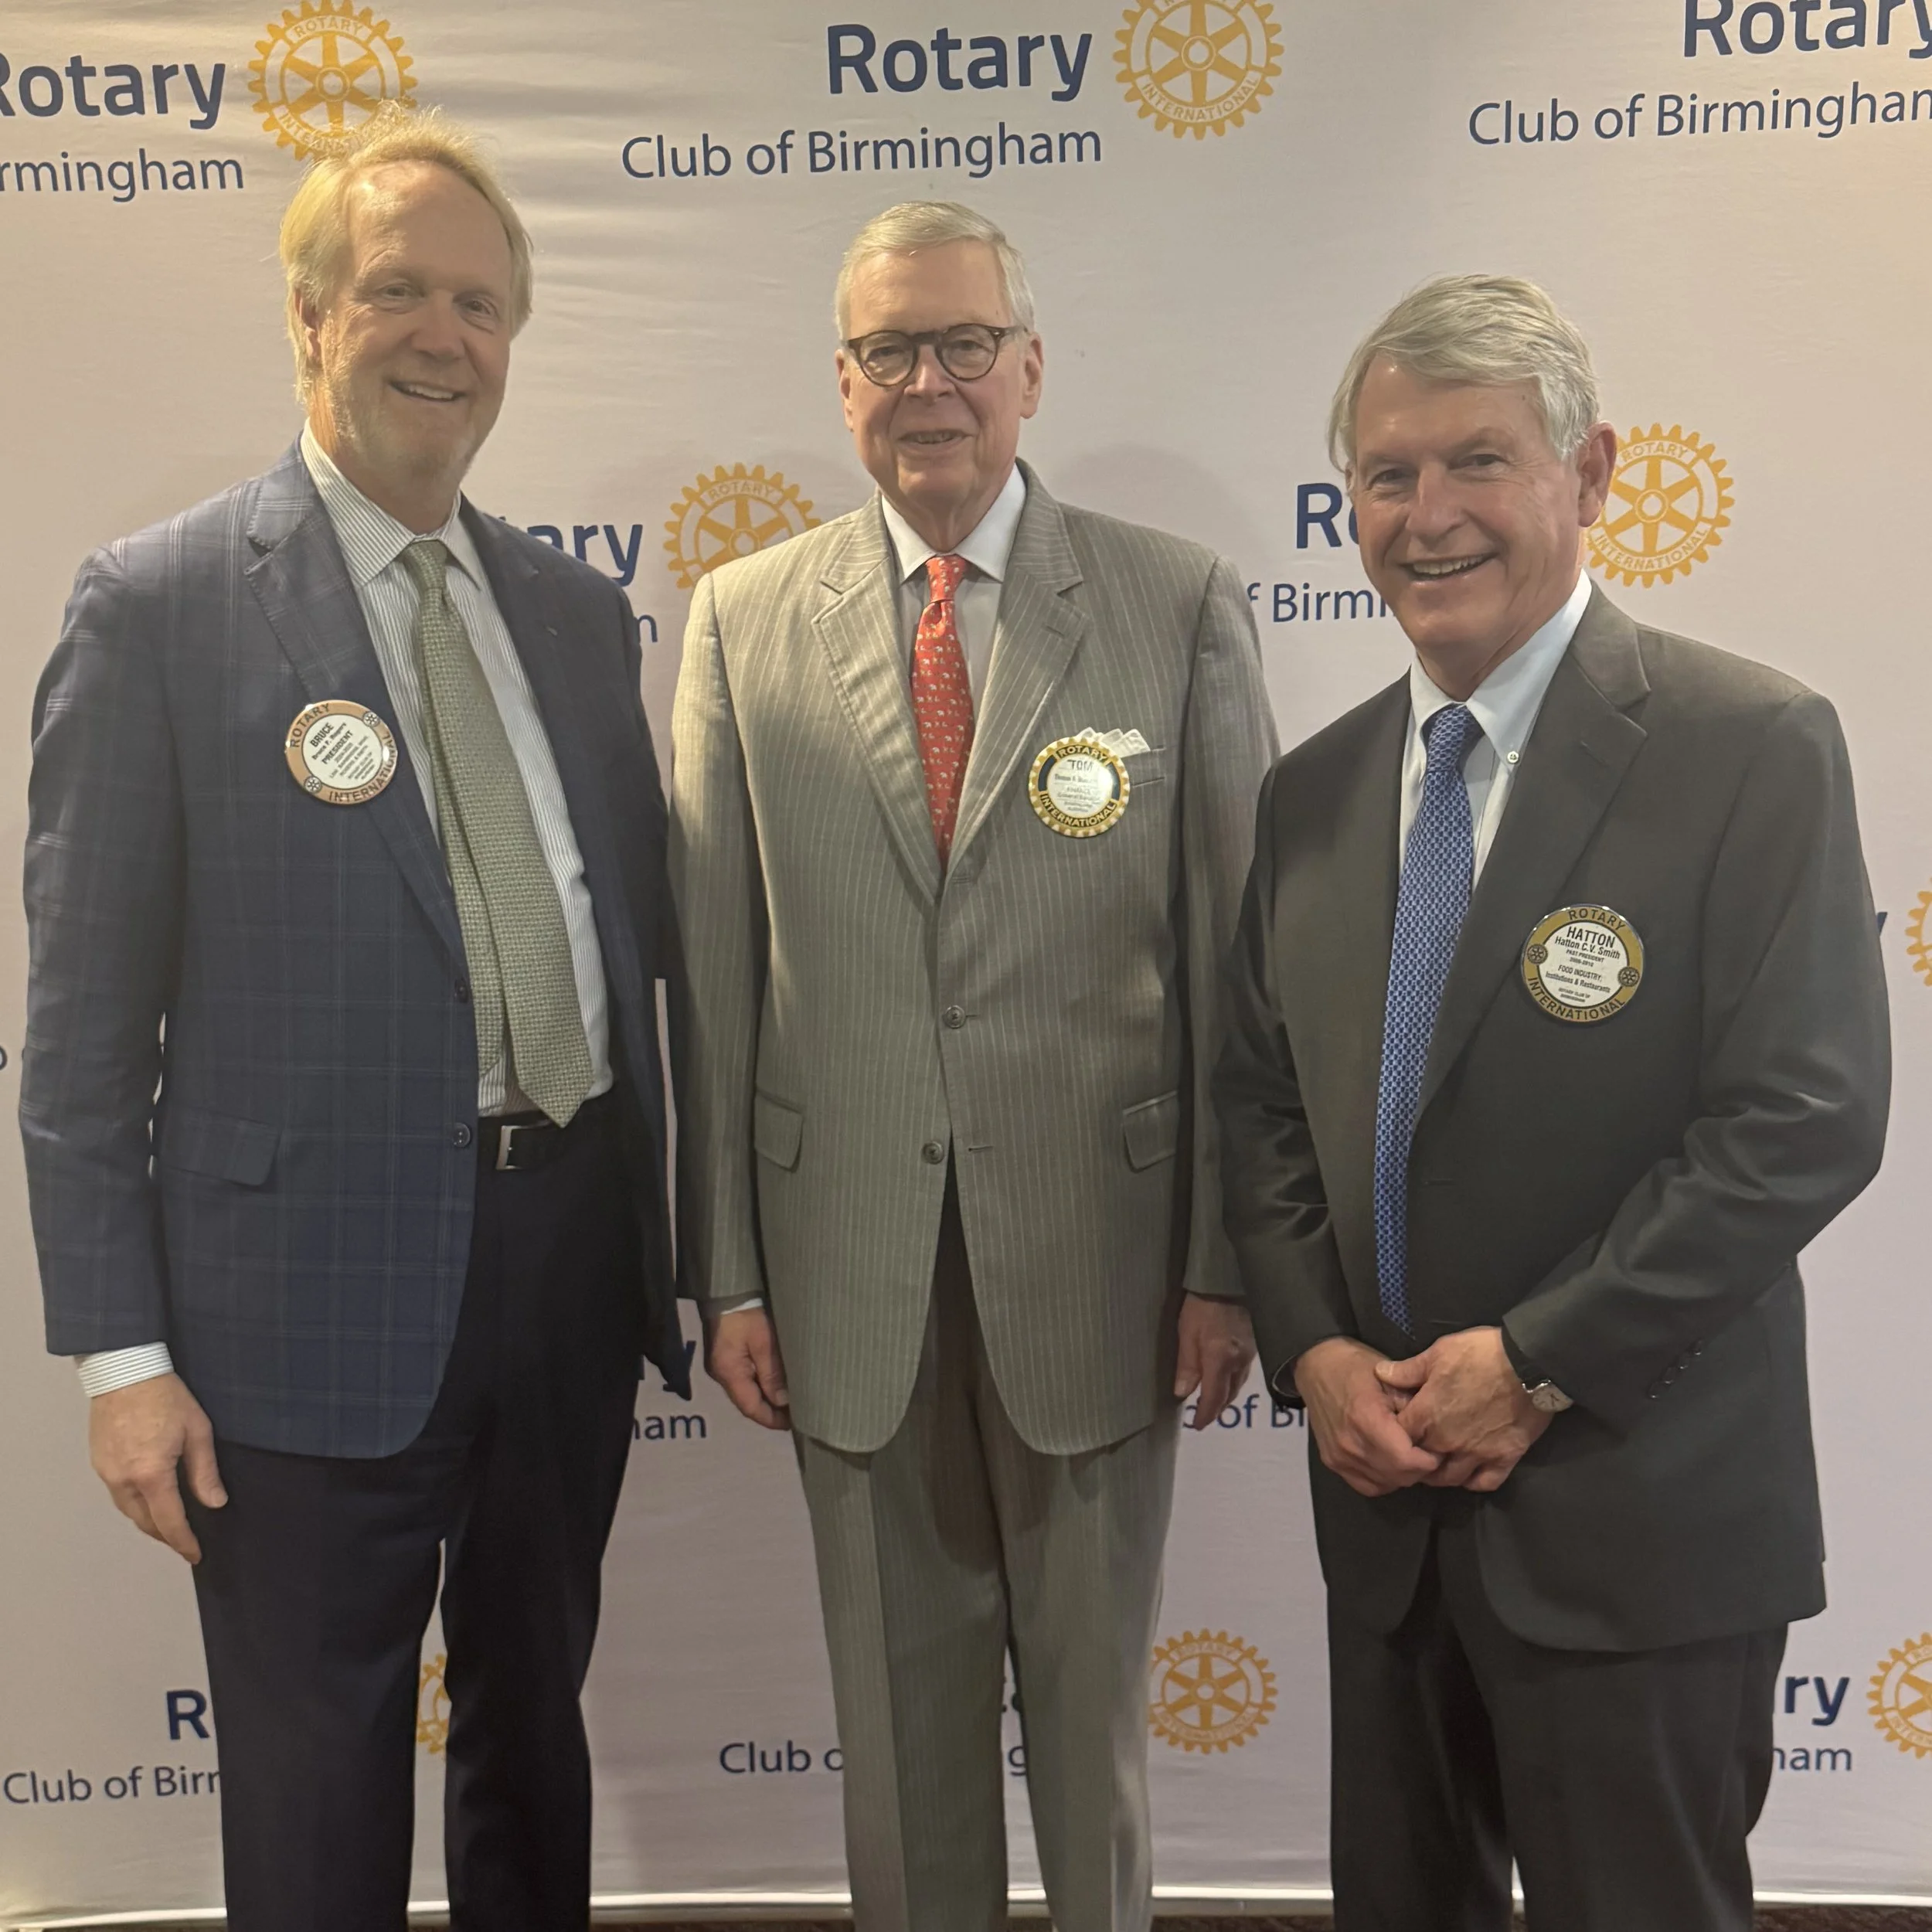
At the Rotary Club of Birmingham, Broughton has also explained the bank’s development to a local audience. Such appearances sit naturally beside his career’s geographical consistency. The bank has expanded beyond Alabama, while its founder continues to discuss the business in the city where he built it. A broader footprint need not erase the room in which a conversation began.
A public company keeps its home address
The holding company, ServisFirst Bancshares, was formed in 2007. The bank crossed $1 billion in assets in 2008, then reached $2 billion in 2011 and $3 billion in 2013. Those milestones measure assets, rather than the initial capital raised to open the doors. They describe successive stages of an operating bank, not a stack of founding investment growing by itself.
Broughton received American Banker’s Community Banker of the Year recognition in 2009. In May 2014, he led the holding company through its initial public offering. A bank that had begun with local capital now had the obligations and visibility of a listed company. The founding proposition had to work under the regular examination that comes with public financial results.
In October 2017, ServisFirst opened its new headquarters in Homewood, in the Birmingham area. The four-story building contained 100,000 square feet, with an adjoining parking deck. Broughton presented the move as a commitment to Birmingham and a way to support the bank’s work. A business that limits branches still needs somewhere for its own people to sit.
He became chairman of both the bank and holding company effective January 1, 2019, adding that responsibility to the president and CEO roles. By 2026, the company’s management biography listed offices in eight states, including Virginia and Texas. His own professional base remained Birmingham. The combination makes his story as much about extending a local way of working as about adding places to a map.
Still making the case for community banking
Broughton’s public appearances have taken the discussion beyond his home market. At the Milken Institute’s 2019 Global Conference, he joined a panel about alternatives to LIBOR, the interest-rate benchmark. In October 2025, he appeared at the Federal Reserve’s Community Bank Conference in Washington, alongside Chip Mahan and Scott Dueser, with Jim Cramer moderating.
At the Federal Reserve discussion, he described opportunities to recruit bankers whose institutions had been acquired and who preferred a more entrepreneurial culture. He also argued for the importance of profitability in assessing a bank’s ability to handle problems. These were the observations of someone who had worked through both sides of an acquisition and then returned to founding.
The current business provides fresh tests of the same operating questions. In September 2026, ServisFirst partnered with Covecta to introduce AI agents into operational workflows, initially focusing on manual work outside critical systems. The announced purpose was to save time and improve how teams worked. The tools were new; the concern with how work gets done was familiar.
On October 19, 2026, the holding company reported third-quarter net income of $87.3 million and total assets of $18.32 billion at September 30. Its efficiency ratio was 30.20%, compared with 35.22% a year earlier. Deposits were $14.09 billion, down 0.1% over the year. Growth, as ever in banking, arrived with several columns to read.
Broughton described an improving loan pipeline. The numbers are a dated snapshot, but the continuing question is personal as well as commercial: can a founder keep a growing organization attentive to the customer who needs an answer? He has spent decades arranging people and authority around that task. The boy who rolled pennies eventually found a much larger counting exercise. He kept the work in Birmingham.