In February 1952, John Schiff crossed Mill Creek to sell burglary insurance to Moore’s Men’s Shop in Cincinnati’s Price Hill neighborhood. It was his young company’s first commercial policy. A clothing shop is a useful place to begin an insurance story: inventory, a front door, a proprietor with something to lose. The problem had an address. So did the person selling the solution.
- Cincinnati sells through independent agents who know their customers.
- Its tools make complex coverage easier to assemble and service.
- Local knowledge still needs sound pricing and protection against large losses.
Schiff and three fellow agents had founded The Cincinnati Insurance Company in 1950 with $200,000. Their bet was practical: build the carrier they wanted to represent. The resulting group now sits within Cincinnati Financial Corporation, whose 2025 revenue reached $12.631 billion. The interesting question is how much of that original, neighborhood-sized idea can survive at this scale.
The agent gets the good chair
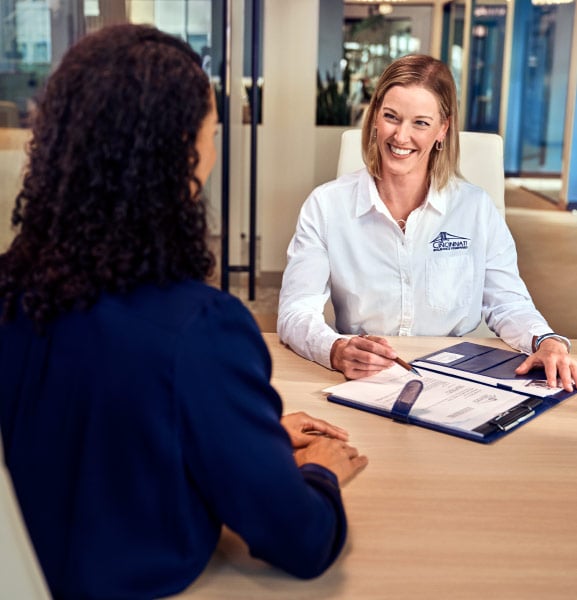
Independent agents can offer policies from multiple insurers. They have choices, which means Cincinnati has to earn its place on their desks. The company organizes around that reality, pairing agency relationships with local underwriting and field claims service. Its domestic personal, commercial and life products are sold exclusively through independent agents.
“The agent is the sun, the moon and the stars.”
Robert B. Morgan, former president
For a customer, the appeal is continuity. An agent can help adjust coverage as a business adds vehicles or a family acquires valuable possessions. Cincinnati’s emphasis is on an ongoing adviser who can explain the policy and assist when a claim arrives. That proposition is especially relevant when the thing being insured refuses to fit neatly into a short online form.
Eight policies, one useful idea
In the mid-1950s, Ohio’s insurance rules blocked multiple-line policies. When the law changed in 1955, Cincinnati was ready. Schiff had obtained a California insurer’s homeowner package; general manager Robert Cosbey adapted it for Ohio. Cincinnati also introduced a commercial Dealer’s Policy that could replace as many as eight separate policies.
The company’s history records an agent joking that he knew nobody who stole houses, apparently unimpressed by theft protection in a homeowner package. Buyers were more receptive. Gross premiums rose 58% in 1956, helped by new products, more agents and geographic expansion. Bundling reduced the work of buying protection. Cincinnati had spotted something useful elsewhere and made it fit its customers.
Put the software behind the conversation
Today, that impulse appears in Cinergy, the agent-facing small-business quoting and issuance platform. Launched in six states in 2022, it uses features including third-party data and client-data recall to reduce repeated entry. An agent can assemble eligible businessowners, auto, workers’ compensation and umbrella coverage without turning every conversation into a transcription exercise.
The small-business program approached $100 million in written premium in 2025. Eligibility expanded to contractors, dentists, veterinarians and optometrists; the platform also gained nonprofit management-liability policies. A dedicated underwriting team supports it. If a business does not qualify, information can pass to a field marketing representative for standard-lines evaluation.
agent
eligibility
further review
Qualifying businesses can obtain three-year package policies in most states for many coverages. The distinction matters: rates may stay unchanged during the term while premium dollars rise if rating exposures change. A growing payroll, for example, can alter the bill. Buyers should ask an agent to explain which parts of their particular policy remain stable.
The broader menu reaches well beyond Main Street. Commercial customers can buy property, liability, cyber and other protections. Cincinnati Private Client serves households with high-value homes, collector cars and valuables. Life insurance and fixed annuities come through Cincinnati Life. Business loss-control consultation is included at no additional charge, giving customers a reason to talk to their insurer before anything breaks.
For a shop owner, the buying exercise starts with consequences: damaged stock, an injured visitor, or income lost during a covered shutdown. A businessowners’ policy combines property, business income and general liability protection. That package does not settle every question. Vehicles, employees and professional services bring additional exposures that an agent can help identify.
The weather gets a vote
Relationships do not set the weather. California’s January 2025 wildfires produced what management described as the company’s worst catastrophe loss. Personal lines finished the year with a 103.6% combined ratio. That measure compares claims and underwriting expenses with earned premiums; above 100% means an underwriting loss before investment income.
Claims + underwriting expenses. Below $100 leaves an underwriting profit; investment income is separate.
The whole property-casualty group nevertheless recorded a profitable 94.9% ratio for 2025. Diversification helped make the group’s result different from its personal-lines result. Cincinnati also buys reinsurance. A July 2025 treaty expansion added a $300 million layer for estimated annual ceded premiums below $5 million, while Cincinnati retained 57.2% of losses in that layer. Protection has both a price and a boundary.
The arithmetic tightened again in the second quarter of 2026: the group’s ratio reached 100.8%, with elevated catastrophe losses. Investment income supported profits. That is the insurer’s two-engine business model: charge enough to cover risk and expenses, then earn returns on invested assets. A profitable income statement deserves a look underneath.
A local idea, with limits
Cincinnati’s reach now includes assumed reinsurance through Cincinnati Re and London specialty underwriting through Cincinnati Global’s Lloyd’s Syndicate 318. Its standard-market property-casualty group markets in 46 states. Yet a prospective customer still starts with an independent agent, a particular risk and an underwriting decision. Product availability is specific, even when the company is large.
Its expertise therefore spans two jobs: understanding a customer’s operations and deciding which risks the insurer can afford to accept. Loss-control consultants work with businesses on prevention; underwriters assess and price coverage; claims representatives handle the promise after a covered loss. Technology supports those decisions, including property-level wildfire analytics documented in a partnership with ZestyAI.
In the market, Cincinnati belongs beside established commercial and personal insurers. Travelers, The Hartford and Chubb are relevant alternatives depending on the account. The useful comparison is specific: policy wording, limits, deductibles, service and price for the same exposure. Cincinnati’s local-service proposition deserves that scrutiny. An adviser adds value when the advice makes the contract easier to understand.
The useful lesson is to improve the tools of someone the customer already trusts. It takes capable partners, patient capital and prices that withstand claims. Buyers who prize immediate self-service may prefer another route. For a complicated business, though, having someone nearby who can translate the paperwork remains a service worth comparing. The final test is whether that help earns its place in the premium.