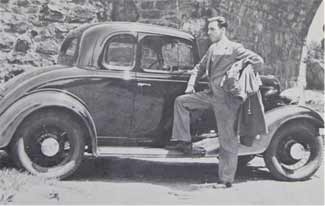
The horse ran away. The carriage was wrecked. Daniel L.B. Smith, a New Jersey shopkeeper who had lent both to a friend, declined repayment. When that friend, a banker and insurance agent, later left the area, he handed Smith some insurance policy declarations. An agency appeared in the general-store window. Eventually, Smith decided the distant carriers serving his rural customers could do better. In 1926, he and several colleagues put up $20,000 and started an insurer.
- The proposition: business and household insurance sold through independent agents.
- The operating bet: local judgment, supported by shared technology.
- The tension: knowing a customer does not guarantee knowing the eventual cost of a claim.
It is an entertaining origin for Selective Insurance, partly because the precipitating event was exactly the sort of everyday calamity the company would spend a century pricing. Smith’s reported ambition for claims service was wonderfully concrete: get a representative there “before sundown.” The interesting question is what happens when that neighborhood promise becomes a business writing roughly $4.9 billion in annual net premiums.
Put the expert within reach
Selective sells property and casualty insurance. That means the damaged building, the injured employee, the lawsuit, the business vehicle. Its customers include contractors, manufacturers, schools, public entities, nonprofits and households. Standard commercial coverage sits alongside personal insurance, specialty commercial coverage through its excess and surplus business, and flood insurance through the federal National Flood Insurance Program’s Write Your Own arrangement.
These are different problems with different underwriting questions. A contractor needs someone to understand the work being done; a school has another set of exposures. Selective’s field model puts underwriting and claims expertise close to agents and customers. The independent agent supplies a relationship and helps arrange coverage. The carrier supplies the financial promise, subject to the policy’s terms.
There is nothing exclusive about using independent agents. Travelers, The Hartford and Cincinnati Insurance are among the alternatives buyers may encounter. Selective’s competitive proposition is the combination: local access to people who understand risks, backed by systems that handle the paperwork. Its description, “high-tech, high-touch,” is corporate language for an operational choice. Technology supports the intermediary instead of making the intermediary disappear.
For the buyer, the practical move is to start with an appointed agent and describe the operation in detail. Ask about exclusions, limits, deductibles and claims handling. Price follows the risk and the coverage. A single advertised premium would tell a school administrator very little about what a manufacturer should pay.
The price of yesterday’s promises
Insurance has an awkward clock. Money comes in before the final cost is known. Claims from an earlier policy year can become more expensive long after the policy was sold. A friendly agent cannot shorten that clock. Nor can a good year of sales prove that the original price was adequate.
In 2024, Selective’s GAAP combined ratio reached 103.0%. This measure adds claims and underwriting expenses relative to earned premiums. Above 100 means an underwriting loss. The year included 7.1 percentage points of unfavorable prior-year casualty reserve development, primarily reflecting higher-than-expected general liability severity. In plain language, estimates for older claims needed more money. Catastrophes added another 6.5 points.
The first thing exposed here was the adequacy of earlier loss estimates. Selective’s 2024 report says reserve reviews inform pricing goals and underwriting actions. That is the documented feedback loop: reassess losses, adjust estimates, change the business being written. It is also the limit of the local-knowledge argument. Familiarity with a customer cannot neutralize rising litigation costs or unexpectedly severe claims.
In 2025, the combined ratio improved to 97.2%, while renewal pure price increases across the portfolio averaged 9.5%. Selective reported $421.2 million in after-tax net investment income as well. These are separate engines. Underwriting makes money when premiums exceed covered losses and expenses; invested assets can produce income while claims are waiting to be paid.
Knowing the customer is useful. Knowing what the promise will cost is indispensable.
A smartphone at the loading dock
The more intriguing product may be the claim that never happens. Through TuMeke Ergonomics, eligible Selective business customers with workers compensation coverage can obtain an AI-assisted assessment at no additional cost. The process begins with a consenting employee being recorded doing a task on a smartphone.
A risk management specialist uses the platform to examine risky movements and postures, then sends an assessment with a risk score and suggestions. Customers can request a follow-up discussion. No futuristic headset is required. The useful output is a conversation about how someone lifts, reaches or repeats a movement during an ordinary working day.
Another partner, Praesidium, provides abuse-prevention resources, including training and model policies; some background-screening services carry discounted charges. MySelective handles more familiar chores: payments, claims reporting, documents and certificates of insurance. Its listed app features exclude flood policies, and replacement auto ID cards are unavailable through it in New York. Convenience has boundaries worth checking before trouble arrives.
A new address, the same question
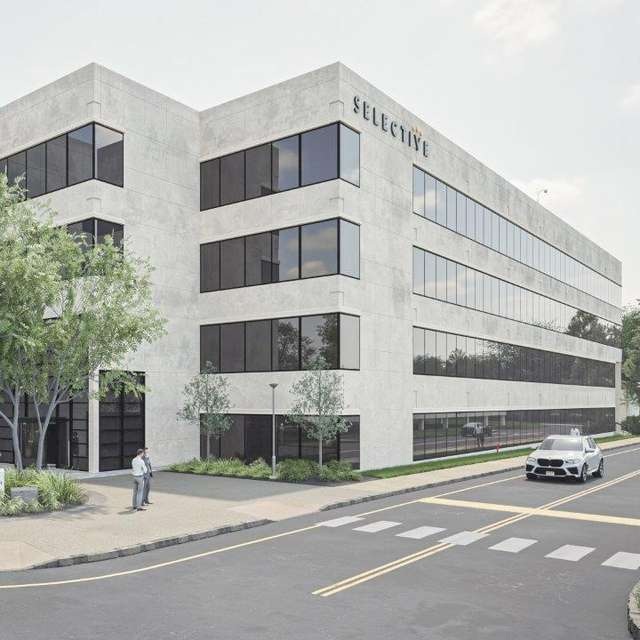
Selective’s corporate contact page now lists Short Hills, New Jersey. Branchville remains an insurance administrative office as the company undertakes a phased transition. Its new headquarters lease covers 122,525 square feet. The stated rationale includes transport access, collaboration and employee well-being. Even a relationship business has to consider where people can conveniently meet.
Recent results preserve the tension: in the second quarter of 2026, net premiums written fell 5%, while the combined ratio improved to 98.0% from 100.2% a year earlier. Growth and underwriting performance can travel in different directions. In October, Selective appointed Vaibhav Kalia chief investment officer, putting a permanent leader over the other earnings engine.
The transferable idea is modest and demanding: place expertise near the customer, give it useful tools, and keep revisiting the assumptions behind the price. Customers can copy the first step themselves. Bring the agent the awkward details of the business, then ask what would change the coverage decision. The horse is optional.