Kevin Tobin’s retirement cake came decorated with blue raindrops. There he was, in a baseball cap, smiling behind a message in icing: “Happy Retirement Kevin. We will miss you!” After a career that included leading a flood insurance technology business, even dessert had acquired a weather system.
The photograph, shared after Torrent Exchange 2025, offers a cheerful end to one chapter. Tobin was retiring from Torrent Technologies after more than 35 years in the industry. Mark Damico would succeed him at the end of July. By January 2026, Tobin was listed as vice chair of ACORD’s board, serving as an outside director. The operating job had ended; his place in the industry’s conversations continued.
Much of his later work concerned a less cheerful picture: property owners discovering, after water arrived, how little financial protection they had arranged beforehand. Tobin approached that problem through distribution, technology and the everyday work of agents. His career becomes interesting at the point where those rather corporate nouns meet a very ordinary question. How does someone actually get covered?
A detour through the auto parts aisle
Tobin’s route to that question did not run entirely through insurance. His education included the University of Iowa’s Tippie College of Business, which he attended from 1983 to 1987. Between 1987 and 2008, he worked at Allstate and HSBC, holding leadership roles concerned with analytics, technology, customer satisfaction and commercial partnerships.
Then came a departure from financial services. In 2008, he joined Advance Auto Parts in Roanoke, Virginia, as general manager of its $4 billion consumer business. His remit included changing the customer proposition, redirecting marketing investment and reshaping the organization’s leadership and culture. The $4 billion described the business he was managing, rather than a growth figure or a personal accomplishment.
He later moved to Fair Isaac Corporation, better known as FICO, working on its business distribution model through the credit bureaus Experian, Equifax and TransUnion. Insurance, replacement car parts and credit analytics make an unusual set of office doors. Across those assignments, however, the recurring business problem was recognizable: reaching customers through systems and intermediaries that could make an offer useful.
That continuity is a reading of his career, rather than an explanation Tobin has supplied for every move. It helps account for why the next stage involved both insurance operations and the customer relationship. By the time he became chief operating officer of Marsh’s Insurance Services Businesses, operations and technology were explicitly his responsibility.
The client, the broker and the machinery between
On August 1, 2013, Tobin became CEO of Marsh Private Client Services, succeeding Lisa Lindsay. The business served wealthy individuals and families. His appointment put someone with an operational background in charge of a service whose purpose depended on understanding particular clients and their possessions, exposures and expectations.
The movement from COO to client business leader matters. Improving an internal process can look impressive on a management presentation while doing very little for the person at the other end. Leading a client business makes that distance harder to ignore. Tobin’s appointment joined the two responsibilities in a career already spent moving between customer propositions and the systems supporting them.
In 2015, he appeared at the Family Office Exchange Wealth Advisor Forum on a panel about applying industry trends to advisor service. The other panelists included John Benevides, Glen Johnson and Dennis Wright. The setting placed insurance alongside the broader work of advising families, rather than treating it as an isolated purchase made once and filed away.
His subsequent Marsh responsibilities reached into different channels. In 2016, Rich Drab joined as CEO of Dovetail Insurance and reported to Tobin, then president of Marsh’s Insurance Services Group. Dovetail’s platform allowed independent agents serving small businesses to obtain quotes from multiple insurers and bind coverage online in real time.
Tobin also led Marsh Sponsored Programs on an interim basis before Michael Westwood arrived as president in 2017. That business supplied insurance through associations, franchises and other networks. In 2019, Anita Sathe became global leader of the Bluestream digital broker platform and leader of Marsh’s US affinity business, reporting to Tobin. Different customers, different entry points, the same practical territory: how coverage reaches the buyer.
When speed becomes personal
Flood insurance gave those distribution questions an urgent consequence. When FEMA selected Torrent as a direct service provider for the National Flood Insurance Program in 2017, the technology discussion concerned applications and claims payments. Tobin put the desired outcome plainly: people needed to be paid “quickly and accurately so they can restore their lives and their property.”
That is a more demanding brief than simply putting an existing form on a screen. The customer’s problem continues after the policy is issued. A system has to support the moment when the promise is called upon, as well as the moment when it is sold. Tobin linked Torrent’s technology investment to both ends of that relationship.
In an April 2018 video interview, he discussed combining flood protection products with data analysis to reduce flooding’s impact on consumers and businesses. The subject was the danger beyond designated hazard areas. The work required looking past a convenient boundary on a map and considering the risk a property could actually face.
A product announcement in September 2019 showed how that approach could become an agent’s workflow. Torrent introduced FloodPlus Commercial, underwritten by Hiscox through Johnson & Johnson. At launch, it offered up to $2.5 million in coverage for small commercial properties, including buildings, business personal property and business interruption risks.
The announcement also described the operational details: no elevation certificate requirement, no 30-day waiting period and the ability to quote, bind and issue policies in real time. Those were features of that offering at its launch. They reveal what “easier” meant in practice: fewer steps between an agent recognizing an exposure and a customer obtaining protection.
- UnderstandRecognize the property’s flood exposure.
- ArrangeHelp an agent turn that risk into suitable coverage.
- RecoverMake the claims process work when water arrives.
The policy nobody asks for
By 2020, Tobin was explaining why adding insurance products did not automatically create more insured property owners. People struggled to understand flood exposure. Agents could find the subject complicated, sell it infrequently and face a cumbersome quoting process. A buyer who needed proof of coverage for a mortgage might get attention; voluntary demand was a harder proposition.
His diagnosis was specific enough to be useful. The obstacle could sit with the customer, the agent or the process connecting them. Improving only one part left the others in place. A better risk model still needed someone able to explain the result and turn it into an accurate policy.
He also argued for cooperation between government and private insurance, including longer-term reform of the National Flood Insurance Program. That position treated the public program as part of a larger system of protection. The practical ambition was to bring more property owners into coverage through complementary options and a process people could use.
In 2021, he returned to the importance of an agent’s guidance, warning that “homeowners may fail to realize or underestimate their flood insurance risk.” The sentence contains an awkward commercial truth: a useful product can remain unsold because the customer does not recognize the need. The sales conversation begins before anyone discusses a premium.
“Homeowners may fail to realize or underestimate their flood insurance risk.”Kevin Tobin, 2021
His 2022 introduction to Torrent’s State of Flood Report organized the challenge around education, products, access and affordability. Each represented a possible point of failure. Knowing the danger did not guarantee a suitable policy; a suitable policy did not guarantee an affordable one. The argument gave technology a supporting role within a wider effort to make protection reachable.
A cake, a handover, another board meeting
The emphasis continued in Tobin’s introduction to the 2025 State of Flood Report. He focused on attracting more uninsured property owners, the role of public and private collaboration, and recovery after flooding. It was a demand problem as much as a product problem, carried forward into his final year leading Torrent.
Then came the handover. Victor announced on July 9, 2025, that Damico would become Torrent’s president and chief operating officer effective July 31. Damico had been COO since 2018. Victor CEO Charles Williamson thanked Tobin for leading the business through technological advancement and a period of complex change.
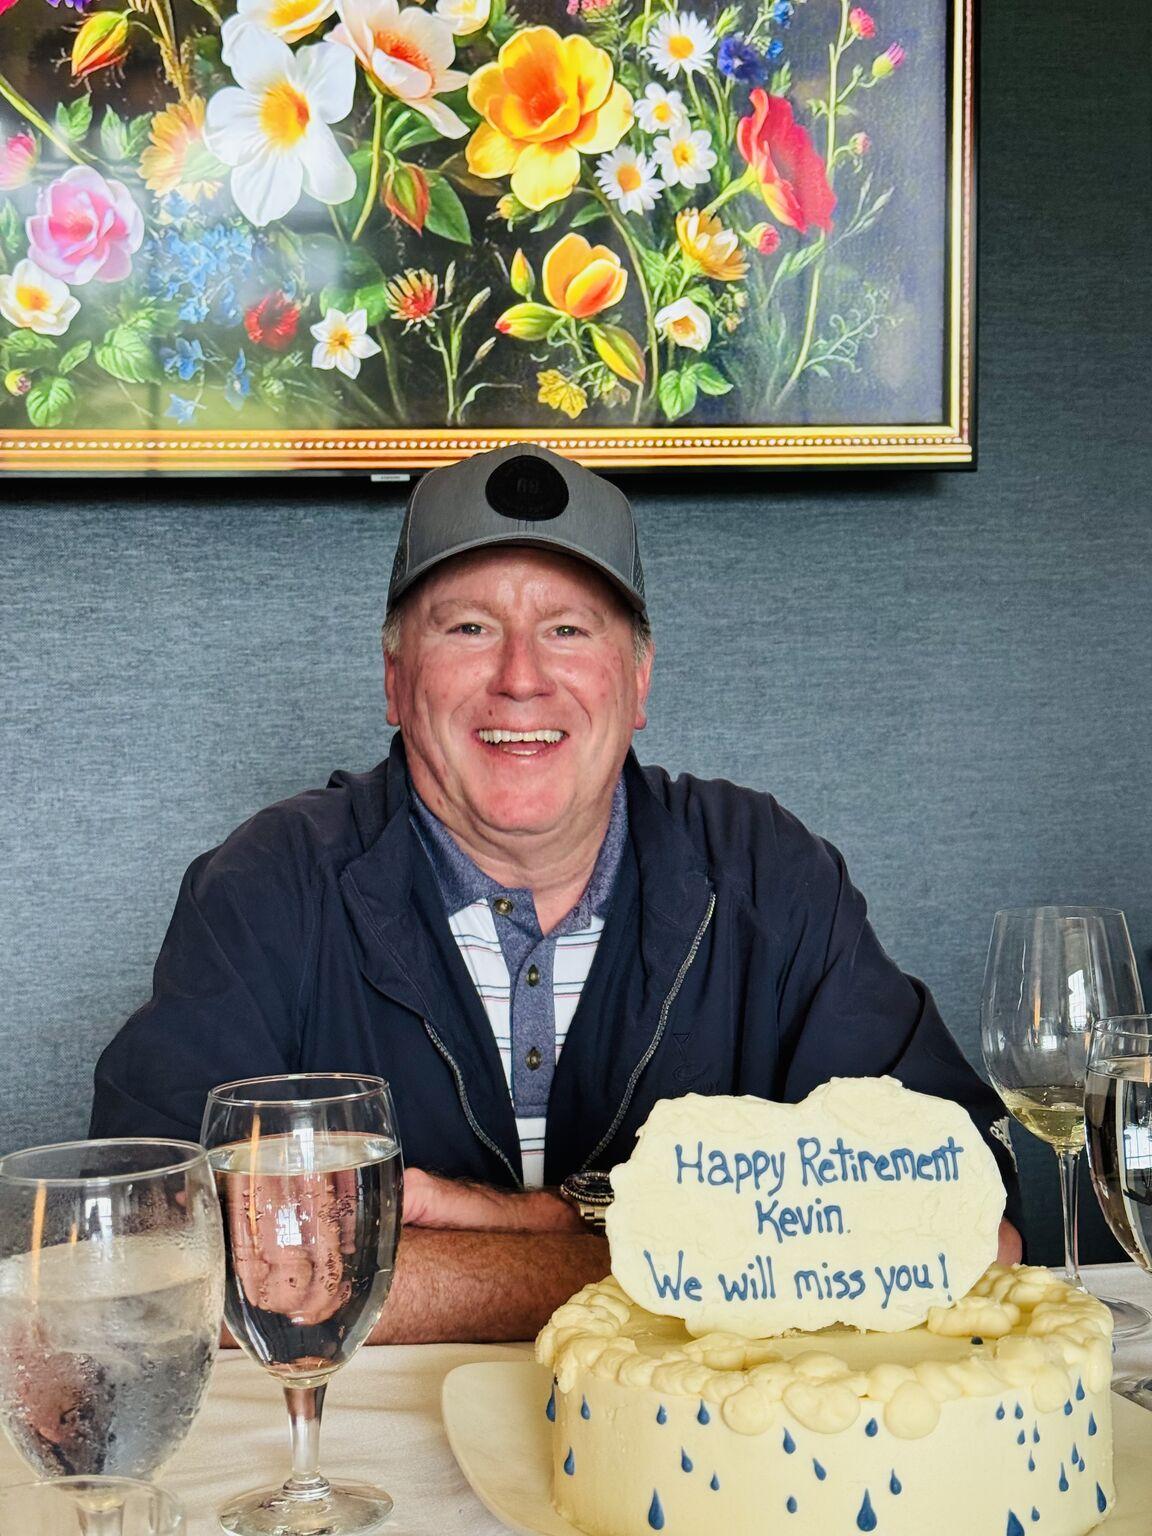
At Torrent Exchange that year, Daniel Kaniewski discussed disaster resilience and recognized Tobin’s retirement. His photographs included the cake and a relaxed picture of the two colleagues on the water. They give the transition a human scale: a leadership change also means people saying goodbye to someone they have worked alongside.
ACORD’s January 2026 board announcement supplied the next professional marker. Tobin remained vice chair, now identified as an outside director. He had also served as vice chair in 2022, when he was listed with his Marsh Insurance Services Group title. The standards organization works on data exchange, forms and workflows across insurance, familiar territory for an executive whose assignments repeatedly involved the machinery behind a transaction.
The interesting measure of that career lies in the small moments those systems are supposed to improve. An agent completes a quote. A customer understands an exposure. A claim moves toward payment. Tobin’s work kept returning to the distance between an insurance promise and its delivery. The retirement cake could afford to make light of rain. His professional attention had been on what happened after it fell.