The farmers had noticed something peculiar about the price of a country road. In 1926, Ohio farmers were paying auto insurance rates that failed to recognize their lower accident experience. Their roads were quieter. Their bills did not adequately reflect it. Through the Ohio Farm Bureau, they helped establish a mutual insurer with a $10,000 capital fund. The first policy was sold on April 14. The company eventually became Nationwide.
- A better risk pool: farmers built coverage around a difference other insurers overlooked.
- A wider business: insurance now sits alongside retirement plans, annuities and employer benefits.
- A harder promise: mutual ownership still leaves difficult decisions about price, protection and renewal.
It is a useful origin because it begins with an observation anyone can borrow. A category called “drivers” contained people whose risks differed. The farmers organized around that difference. Volunteers went from neighbor to neighbor selling policies. Distribution, trust and underwriting began within the same community.
01 A pool that learned to branch out
Today, the Columbus company sells auto, home, farm, commercial, pet and life insurance. Its financial businesses offer annuities, mutual funds and retirement plans. A household can insure its car; an employer can arrange a retirement plan; a farmer can protect buildings and equipment. The problems differ, but each involves moving financial uncertainty away from someone who would struggle to carry it alone.
The expansion started early. Life insurance and annuities arrived through an acquisition in 1935. A mutual fund business followed in 1952. The Nationwide name arrived in 1955. Seen together, those dates describe a company discovering that customers who needed protection against an accident also needed help financing a much longer life.
Nationwide is a mutual, owned by policyholders rather than public stockholders. Premiums, investment earnings and income from financial products support the enterprise; claims, operating expenses and future obligations consume its resources. Mutual ownership changes whom management serves. It does not make capital optional.
Sales and premiums, USD. Bars start at zero. These figures are not accounting revenue.
For 2025, Nationwide reported $73.2 billion in sales and premiums, $4.3 billion in net operating income and $32.8 billion in total adjusted capital. Those are three different measurements. Sales describe activity; operating income describes earnings; capital supports the promises still outstanding. The company paid more than $20.2 billion in claims and benefits that year.
02 The agent gets a choice
A century-old insurer can sound fixed in its ways. Consider what happened to Nationwide’s agents. In July 2020, the company completed a two-year transition to independent agency distribution. Its announcement said agents wanted greater flexibility and customers wanted more options. Rather than keep the exclusive arrangement, Nationwide accepted a channel in which an agent could offer competing carriers.
The company reported that 99% of its formerly captive agents transitioned and continued partnering with it. That is a specific answer to what changed management’s mind: the preferences of the people selling and buying coverage. For a business owner, the transferable idea is to make a partner’s freedom compatible with your own growth.
“Our capital position reflects strong performance and disciplined use of capital across our business portfolio.”
Tim Frommeyer · Chief Financial Officer · April 2026
Nationwide occupies several markets at once. State Farm, Progressive and GEICO are familiar alternatives for motorists; retirement buyers encounter another set of providers. Nationwide’s distinction is the combination of mutual ownership, agricultural relationships and a broad protection-and-retirement portfolio. Its case for consideration changes with the customer. Breadth alone cannot settle a comparison of price, exclusions or service.
03 The expensive part of keeping a promise
In July 2025, Nationwide paid $1.25 billion for Allstate’s employer stop loss business. Stop loss protects employers that fund their own employee health plans against excess losses. It takes the familiar insurance problem up a level: the customer carrying medical risk is now the employer. This is how the company grows beyond the household policy without abandoning the underlying work.
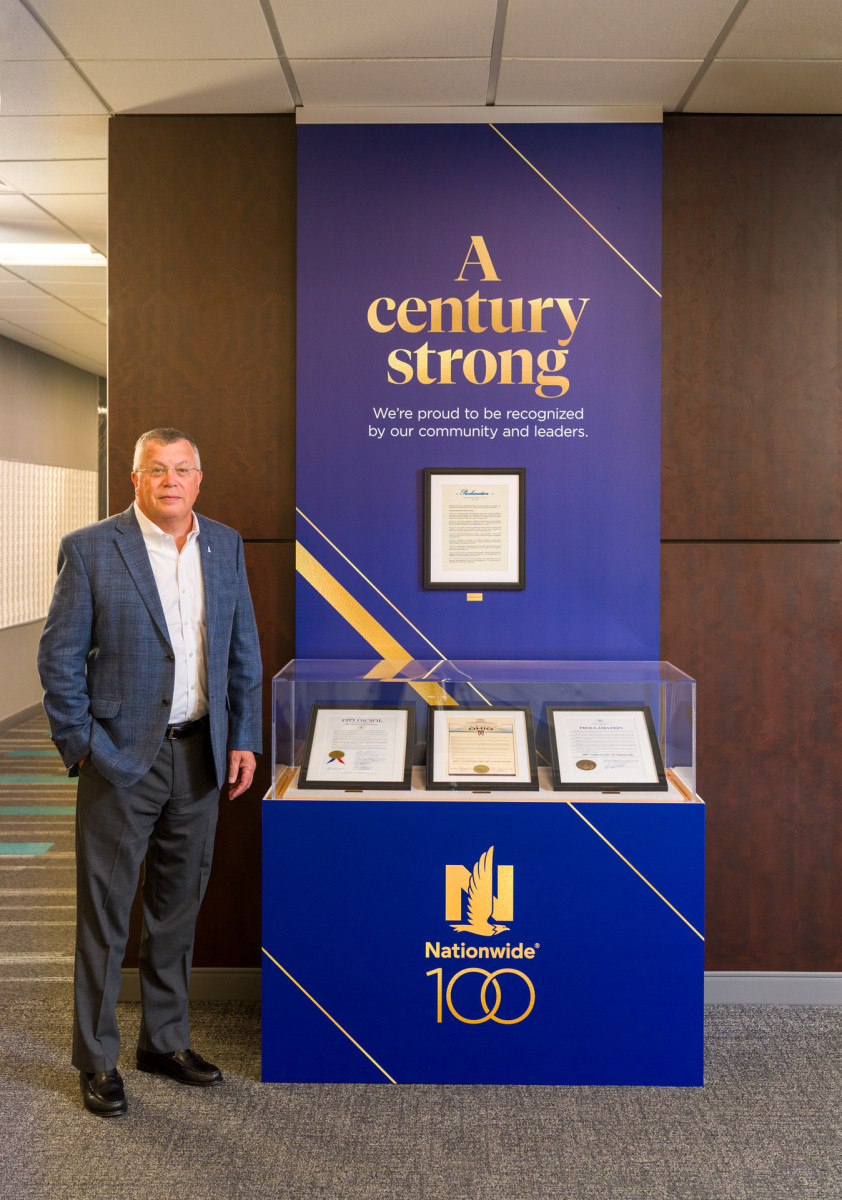
CEO Kirt Walker beside proclamations honoring Nationwide’s 2026 centennial. A company born around farm cars now carries a much wider set of promises.
Photo: NationwideYet the difficult counterexample is a pet. In 2024, Nationwide announced that it would not renew roughly 100,000 pet policies through summer 2025. It cited rising veterinary costs and other factors, saying changes were necessary for the business’s financial sustainability. Owners facing replacement coverage worried about conditions that another policy might treat as pre-existing.
Here, the strain showed up in the economics of the coverage. Protecting the pool’s future meant withdrawing some existing products. Policyholders experienced that decision individually, with an animal already in their care. The episode belongs beside the growth figures because it shows the limits of treating ownership structure as a guarantee of an uninterrupted relationship.
04 Catch the leak before the claim
Nationwide’s more appealing calculation is the loss that never happens. Its prevention programs include Ting electrical monitoring and LeakBot water-leak detection. Its AgTech Innovation Hub collaboration with Ohio State and Ohio Farm Bureau works on agricultural climate risk. The logic is practical: earlier information can give someone time to act before damage becomes a bill.
A sensor needs an installed device, a received alert and a response. Each step matters.
SmartMiles offers another version of the founding observation. It combines a base premium with a variable charge tied to miles driven, making it worth comparing for low-mileage drivers. More driving changes that calculation. State availability and vehicle eligibility also matter. A familiar brand cannot answer those questions for a particular household.
The next chapter includes a stated $1.5 billion technology investment through 2028, including $100 million annually for AI. The company also reports filling 61.5% of its 2025 job openings through internal moves. Both commitments concern an institution learning new habits. The customer’s test remains wonderfully concrete: understand the promise, compare its terms, and see whether it fits the risk you actually have.
Follow the risk
Explore coverage, product explainers and the company’s latest work.