A warehouse is an odd place to look for an investment thesis. There is no download button. Nobody gets excited about its next software release. Yet in 2013, Tano Capital committed ₹80 crore to Shree Shubham Logistics, an Indian agricultural logistics company. The business stored things people needed to eat. More consumption required more capacity. For an investor interested in India's expanding domestic economy, a warehouse could be a remarkably direct expression of an idea.
- Tano turns broad themes into investments in individual businesses, from Indian warehouses to biometric devices.
- Its India funds raised $100 million and $111.3 million in successive vintages.
- The hard part arrives after the cheque: manufacturing, expansion and finding a way out.
This is the useful way into Tano: follow the capital into the machinery. Founded in 2004 by Charles E. “Chuck” Johnson, formerly co-president of Franklin Templeton Investments and CEO of Templeton Worldwide, the San Mateo firm built an alternative investment business around emerging markets and hard assets. Its stated interest in domestic consumption in India and China sounds expansive. Its transactions make that ambition tangible.
A big idea, purchased one business at a time
Consider what the firm was selling to investors. Its first India private equity fund, a 2006 vintage, had $100 million. In January 2012, Tano announced the final close of its second at $111.3 million. The intended hunting ground was India's growing middle market, across manufacturing, financial services, healthcare and consumer discretionary businesses. That is a portfolio of different ways an economy might develop.
The people interpreting that economy mattered. The India advisory affiliate was co-founded by Hetal Gandhi and Carlton Pereira. Gandhi brought experience building the private equity business at IL&FS; Pereira had led corporate finance for KPMG in India, the Middle East and South Asia. Local financial experience gave the international thesis people who could investigate a balance sheet, assess an entrepreneur and negotiate a transaction.
Johnson's comments at the second fund's close also complicate the familiar growth story. He welcomed falling valuations amid uncertainty around Europe and China. Growing economies were one attraction; a lower entry price was another. The distinction matters. A good business can become an expensive investment, even when the economic forecast proves right.
“Globally, valuations have been coming down along with P/E ratios”
Chuck Johnson, January 2012 fund announcement
₹80 crore buys a very physical experiment
Shree Shubham offered a concrete test. At the announcement, it operated and managed 90 owned and leased warehouses, with storage capacity of roughly 1.1 million metric tonnes. The proposed expansion reached Maharashtra, Madhya Pradesh and Rajasthan. The cheque supported capacity, rather than merely buying exposure to the word “India.” A subsequent CARE Ratings report confirmed receipt of the investment in May 2013 and its use for ongoing expansion expenditure.
The financing had a structure. Reporting on the company's later IPO proposal described ₹35.1 crore of equity and ₹44.9 crore of compulsorily convertible debentures. That distinction is worth pausing over: private investment is also the design of ownership, conversion and eventual liquidity. The headline cheque tells only part of the story.
₹35.1 crEquity
₹44.9 crConvertible debentures
In 2019, Kalpataru agreed to acquire Tano's 19.94% stake for ₹64.65 crore through a share swap, with approximately 1.255 million Kalpataru shares allotted to the fund. These are entry and transaction values, not a complete investment return. Still, the change in form is revealing: a stake in a private warehousing business became shares in its listed parent. An exit can change what an investor owns before it produces cash.
The awkward quantity is one thousand
Tano's portfolio also reached beyond Indian growth equity. It backed Tascent, a California biometric identity company, and co-led its $19.5 million Series B with NEC in 2018. Min Aik Technology participated. Tascent combined face, iris and fingerprint capabilities for identity applications. The financing was intended to expand its products and international footprint. The announced round total was shared among investors; it was not Tano's cheque alone.
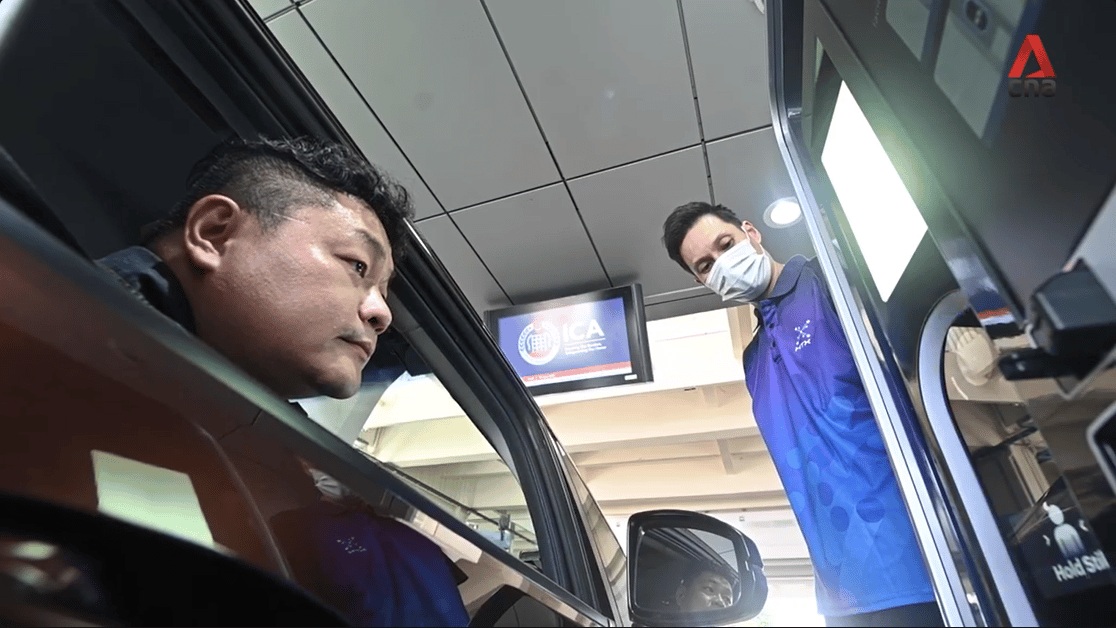
By March 2023, Biometric Update reported that Tascent had closed. Its co-founder Alastair Partington published a reflection that month about the problems of building a hardware startup. One was beautifully specific: obtaining components in quantities between prototypes and mass production. A handful is manageable. A hundred thousand gets a supplier's attention. Hundreds or a few thousand can leave a young company stranded between the two.
Partington called such a buyer a “distraction with promise.” He urged founders to find suppliers prepared for that transition, accept limited discounts and remain flexible about components. He also wished he had sought independent advice earlier and acted more ruthlessly on focus. These are his lessons from the experience, rather than evidence that Tano changed its investment policy. They expose a practical constraint beneath the forecast: demand needs a working supply chain.
Two customers on either side of the cheque
Tano serves investors through privately placed funds and separately managed accounts; portfolio businesses receive the investment capital. Those roles differ. An entrepreneur wants resources to expand. A fund investor wants an appropriate return, with compensation, risk and access governed by the investment documents. Tano's March 2026 regulatory filing reported about $138 million in discretionary regulatory assets across two accounts. Assets managed measure neither the firm's revenue nor the value of the firm itself.
Its market position sits between investors allocating money and businesses seeking growth capital. Other India-focused growth funds compete for similar opportunities; public equity funds offer a different route into the same economy. Tano's distinctive combination is its Franklin Templeton lineage, India advisory expertise and history spanning physical infrastructure and technology. The combination is useful only when individual investments justify it.
Follow the bottleneck
The transferable idea is to translate a market forecast into an operational question. More consumption: where is storage capacity missing? More identity checks: who can deliver reliable devices at commercial volumes? Then examine the purchase price and the exit route with equal care. Tano's history makes those questions concrete. An expanding market can support a company, but it cannot manufacture its components, negotiate its contracts or buy an investor's shares.