Imagine opening a bank account on your phone, getting stuck, and calling for help. The person who answers asks you to begin again. The bank has remembered your balance but forgotten your afternoon. Somewhere between its website, contact center and back office, the request has become somebody else’s problem. Savana’s proposition begins with that handoff: give the institution a way to keep the work, and its context, together.
- Keep the core. Savana coordinates work above existing banking systems.
- Connect the people. Customer self-service and banker assistance share processes.
- Finish the request. Its next AI ambition concerns governed execution.
01The employee in the middle
In an August 2026 account of an interview with FinAi News, Savana President and COO Emily Steele offered a useful diagnosis.
“A banker has become the integration layer at a financial institution.”
Emily Steele / President & COO
It is a wonderfully unromantic description of a familiar job. The employee becomes the person who translates between systems, checks what happened elsewhere and carries the unfinished task across the gap.
Savana builds software for banks, credit unions and fintech companies. Its platform sits above the core, the system of record underneath banking operations. APIs connect that foundation to other tools and channels; workflows coordinate what happens next. The company says one Savana instance can operate across multiple cores. That makes its proposition relevant to an institution changing its machinery while continuing to serve customers.
The distinction matters. Displaying an account balance and completing a service request are different achievements. Savana’s bet is that the process deserves its own architecture. A bank can retain its underlying systems while creating a shared way for people and software to act on them. The customer, ideally, encounters less of the institution’s internal geography.
Mobile · online
Branch · contact center
02140 workflows and a very ordinary ambition
The staff-facing product, Banker Experience, gathers account information, cards, communications and servicing history into one view. It includes case management, document storage and assisted account opening. Savana advertises more than 140 preconfigured workflows, which banks can modify. The number is less interesting than the implication: institutions can start with encoded banking processes instead of drawing every route on a blank sheet.
Customer Experience supplies online and mobile banking alongside account opening for personal and business customers. Savana describes a single code base, source-code access and bank control over branding and journeys. Multiple brands can share an operational model. For a bank running distinct propositions, the appealing economy is maintaining different shop windows without inventing a separate stockroom for each.
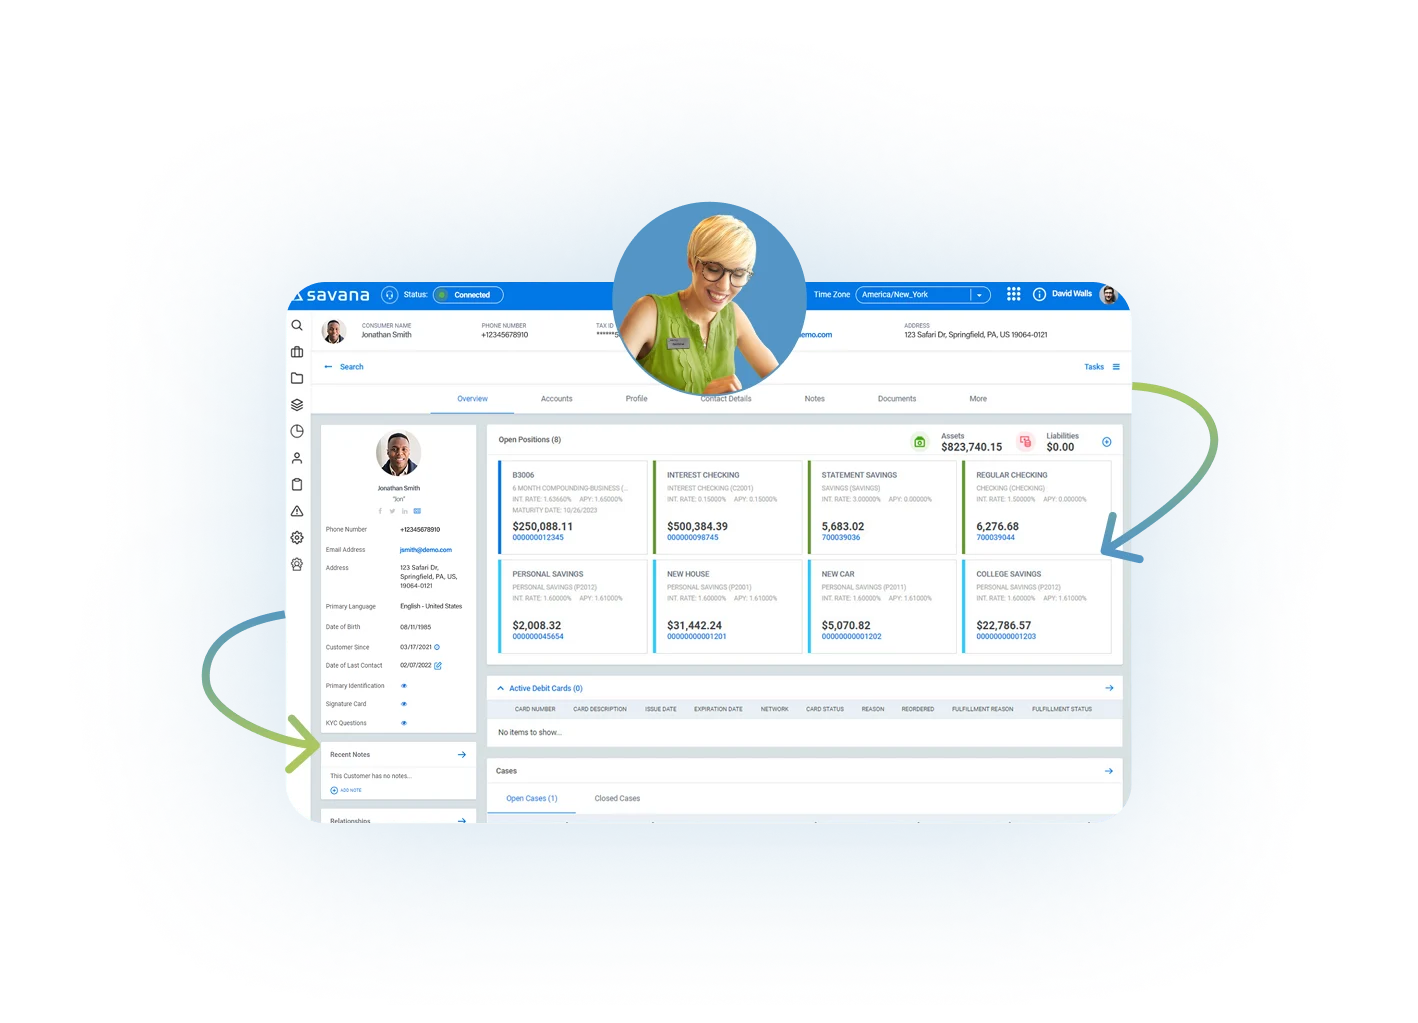
These features place Savana where digital banking, banking CRM and business-process software overlap. Its competition includes the institution’s own assembled integrations. Backbase also markets coordinated banking work and shared customer context above existing systems. Savana therefore has to earn its place through the fit of its workflows and implementation, rather than the mere discovery that bank technology is fragmented.
03Two banks, two routes through the machinery
Primis supplies a concrete example. In December 2022, Savana announced that the bank had launched an all-digital consumer offering, initially focused on retail deposits. Savana coordinated processes between the Finxact core and customer channels. The arrangement shows how a newer core and an orchestration platform can do different jobs within the same bank.
Woodforest’s selection, announced in May 2023, illustrates another route. The bank was undertaking a full technology-stack conversion. It chose Savana to connect departments and service channels around its “universal banker” approach. The announcement described a bank with more than 760 branches across 17 states. Those were deployment ambitions and bank-scale figures at the time, rather than a measured account of savings achieved.
The comparison is instructive. Primis wanted a digital offering brought into operation; Woodforest wanted consistent servicing through a wider conversion. Both needed work to cross technical boundaries. Neither example proves that buying orchestration software automatically improves a bank. Each does establish a specific reason an institution might want it.
04Capital, distribution and the cost of change
Savana was founded in 2009 by Michael Sanchez. By 2017, its public descriptions covered mortgage automation as well as banking servicing. That background helps explain the present emphasis on what happens after a customer makes a request. In a March 2023 interview, CEO Mike Wolfel described working with early adopters to bring the platform into production and continue building its architecture.
The 2022 financing announcement put the headline at $45 million; reporting separated $35 million of Series A equity from $10 million of debt. Georgian led the round, and Fiserv participated while expanding an existing reseller agreement. The combination supplied capital and a distribution relationship. A November 2022 partnership with Capco added transformation consulting to the proposition.
It is an enterprise software business sold to institutions, directly and through partners. For a prospective buyer, the useful cost question concerns the complete project: integration, workflow configuration, testing and staff adoption. The sensible buying exercise is to choose one service journey and establish how it will be completed, who owns exceptions and what improvement would justify expanding the deployment.
There is a practical way to interrogate the pitch. Ask for a demonstration in which an application begins online, encounters an exception and moves to a banker. Watch whether the employee receives the existing information and can complete the next step. Then ask what happens when a connected system is unavailable or a request exceeds that employee’s authority. Measure completion time, repeat contacts and manual intervention against the bank’s current process. These are suggested evaluation criteria, not reported Savana results. They turn a pleasant interface demonstration into an examination of whether the institution has actually changed how it works, and whether its customers will notice in their everyday banking.
05Teach the machine who may do what
The August 2026 update brings the argument into AI. Savana described nearly 18 months of research and development around operational AI, with capabilities being demonstrated to banking partners. The proposed approach draws on an institution’s policies and procedures and restricts execution through banker permissions. Relationship management, fraud detection and customer service were the first use cases identified.
The useful lesson is portable: map the work before adding intelligence. Define the routing, permissions and escalation points. An institution unwilling to settle those questions can automate confusion with remarkable speed. Savana’s promise depends on banks giving their systems coherent instructions. For the customer calling about that unfinished account, success would be much smaller and more satisfying: the next person already knows where to begin.