Imagine a customer moving money on a Tuesday afternoon. The password works. The device looks familiar. The transfer is within the account’s limit. Each detail, considered alone, offers reassurance. The interesting question is what they mean together. For a bank, that question can arrive just before the money leaves.
Plus Technologies & Innovations, usually called PLUS TI, makes software for precisely this sort of decision. Its Monitor Plus portfolio monitors financial and non-financial transactions, combining machine learning with expert models. The phrase “non-financial” matters: a session or a change to sensitive information can tell a story before a payment appears.
- The buyer: banks and other institutions that need to detect financial crime.
- The approach: real-time analysis informed by both models and banking expertise.
- The practical choice: run the model yourself or buy a service that manages it.
The innocent payment problem
Fraud software has an awkward social obligation. It must suspect people without making suspicion the default customer experience. A blocked criminal transaction is a useful result. A blocked legitimate transaction creates another job: somebody must explain, investigate or undo it. A system can be very busy and still be rather poor company.
PLUS TI’s published customer stories make that trade-off tangible. At an unnamed Peruvian institution, Monitor Plus Connect linked digital channels and automated alert handling. The company describes lower operating costs and fewer unnecessary blocks. The claim concerns the work surrounding a decision as much as the detection itself.
At Banco BICE in Chile, the company describes a shift from manual control to predictive monitoring using Monitor Plus ACRM+. At Banco Bolivariano in Ecuador, its case summary describes combining device and behavioral analysis through DBFD and Device Fingerprint. These accounts show what customers changed: workflows, signals and response timing. They are company-published accounts, not promises about every deployment.
In 41 countries, according to PLUS TI’s published company overview. Adoption measures reach; it does not measure the effectiveness of a particular bank’s controls.
An algorithm with a bank specialist beside it
The company’s distinguishing proposition is the combination of expert judgment and machine learning. Monitor Plus offers proprietary detection technology alongside support for the ONNX model ecosystem. Its technology materials also describe an environment for testing models before production.
For a buyer, the attraction is understandable. A statistical model may recognize a pattern. A specialist understands the bank’s products, exceptions and appetite for intervention. PLUS TI describes its financial crime models as “white box,” open to the expert user. That makes inspection and adaptation part of the proposition.
“minimising dependency”
Jorge Domingo Samayoa, founder and CEO, on the system’s design.
That short phrase reveals a useful priority. The institution should have room to evolve its controls. Our reading of the design is that autonomy becomes valuable when a team needs to change a decision rule without treating the software as an oracle. The point is operational control, with human expertise retained inside the process.
A login is only the first clue
Monitor Plus DBFD, the Digital Banking Fraud Detector, is aimed at web and mobile banking. Its published capabilities span device and network conditions, behavior during a session, transaction habits and authentication challenges. The product considers several stages of the customer journey rather than waiting for a completed payment.
That breadth gives the opening example its substance. A transaction has an amount and a destination, but it also has a surrounding session. DBFD can interact with an institution’s authorizer in real time, recommending whether a transaction should proceed and supporting stronger authentication for higher-risk activity.
- 01ObserveDevice, network and session signals
- 02EvaluateBehavior, transaction and expert models
- 03RespondAuthorization, authentication or investigation
It is a system for institutions, with responsibilities on both sides of the connection. The bank’s authorization infrastructure and response policies still matter. An alert acquires practical value when somebody, or an approved automated routine, can act on it.
Compliance has a different clock
The product family extends into anti-money laundering and counter-terrorist financing. Its AML platform brings together specialized monitoring, compliance risk management, funds transfer controls, anti-corruption and bribery analysis, and FATCA/CRS reporting tools. Those are related institutional concerns, but they do not all call for the same response to a single transaction.
A fraud team may be trying to intervene before an immediate loss. A compliance team has monitoring and reporting work that continues across customer relationships and transaction histories. PLUS TI’s portfolio places tools for both inside a broader banking software business. That breadth is part of where it fits in the market: an enterprise financial crime and operations supplier.
Bank buyers can also consider Acoru and NetGuardians, which CB Insights lists among PLUS TI’s alternatives. The useful comparison is specific: which channels are covered, which signals can be integrated and who can alter the controls. PLUS TI’s case rests on its combined expert and machine learning approach, the breadth of its banking portfolio and its options for model ownership.
Two less theatrical products deserve attention. Monitor Plus DQA checks data against accuracy, consistency, completeness and validity criteria. Its materials discuss avoiding errors and duplication. Continuous Auditing, meanwhile, applies ongoing analysis to operations and internal controls, looking for exceptions and process deviations.
Our practical inference is simple: a clever detector cannot repair every weakness upstream. Incomplete customer information gives a model less to work with; poor process ownership leaves findings waiting for an owner. The data and auditing tools address work that an AI demonstration can easily make look incidental.
Intertrade Plus serves another part of the bank. The international operations suite supports foreign exchange, correspondent banking and trade finance. Its published functions include interpreting SWIFT messages and automating transfer-related accounting. The unifying concern is the handling of institutional operations, where an error can become expensive paperwork with an impressive passport.
Who gets the keys to the model?
The cloud offering makes PLUS TI’s business model unusually easy to examine. It sells software access, infrastructure and support in different combinations. The consequential distinction is who manages the model, and where the infrastructure lives.
| Service | Responsibility |
|---|---|
| SaaS | Infrastructure and licensing included; the client controls model management and security. |
| Monitor as a Service | PLUS TI provides licensing, support and full management, including the model. |
| Software subscription | The client provides infrastructure and its model; PLUS TI supplies licensing and support. |
These choices turn the purchase into a staffing and governance decision as well as a software decision. A bank with experienced specialists may value autonomy. Another institution may prefer managed monitoring. Either way, infrastructure, integration, model maintenance and investigation capacity belong in the cost discussion. This is our purchasing interpretation of the service descriptions.
The lesson a reader can copy is to assign those responsibilities before buying. Ask who changes thresholds, who tests a revised model and who handles the result. An attractive dashboard cannot settle an argument between an operations team and a compliance team about whose queue an alert belongs in.
A price attached to the upkeep
A public Banjercito contract supplies a concrete example of the money involved. For services running through 2021, the Mexican bank contracted with Plus Holding International Limited for support of its fraud and money laundering prevention solution. The agreement set a minimum of US$153,971.11 and a maximum of US$384,927.78.
The itemized schedule covered technical support, maintenance, a bank of service hours and knowledge transfer. These are contract limits for a particular support arrangement, rather than a record of the amount ultimately paid or a general Monitor Plus license price. They underline the work around enterprise software: keeping it running and teaching people to use it.
The people behind the parameters
PLUS TI identifies Jorge Domingo Samayoa as its founder and CEO. Company profiles give 2003 as its founding year, while the business describes its roots in Latin America. Its present identity combines that regional banking background with an international institutional customer base.
There is evidence of the customer community beyond the vendor’s own testimonials. Banco de Costa Rica reported winning the Monitor Plus User Challenge in 2020. The bank’s account connected the award to monitoring, analysis and prevention rules, pairing the system with employees’ knowledge of fraud patterns and customer behavior.
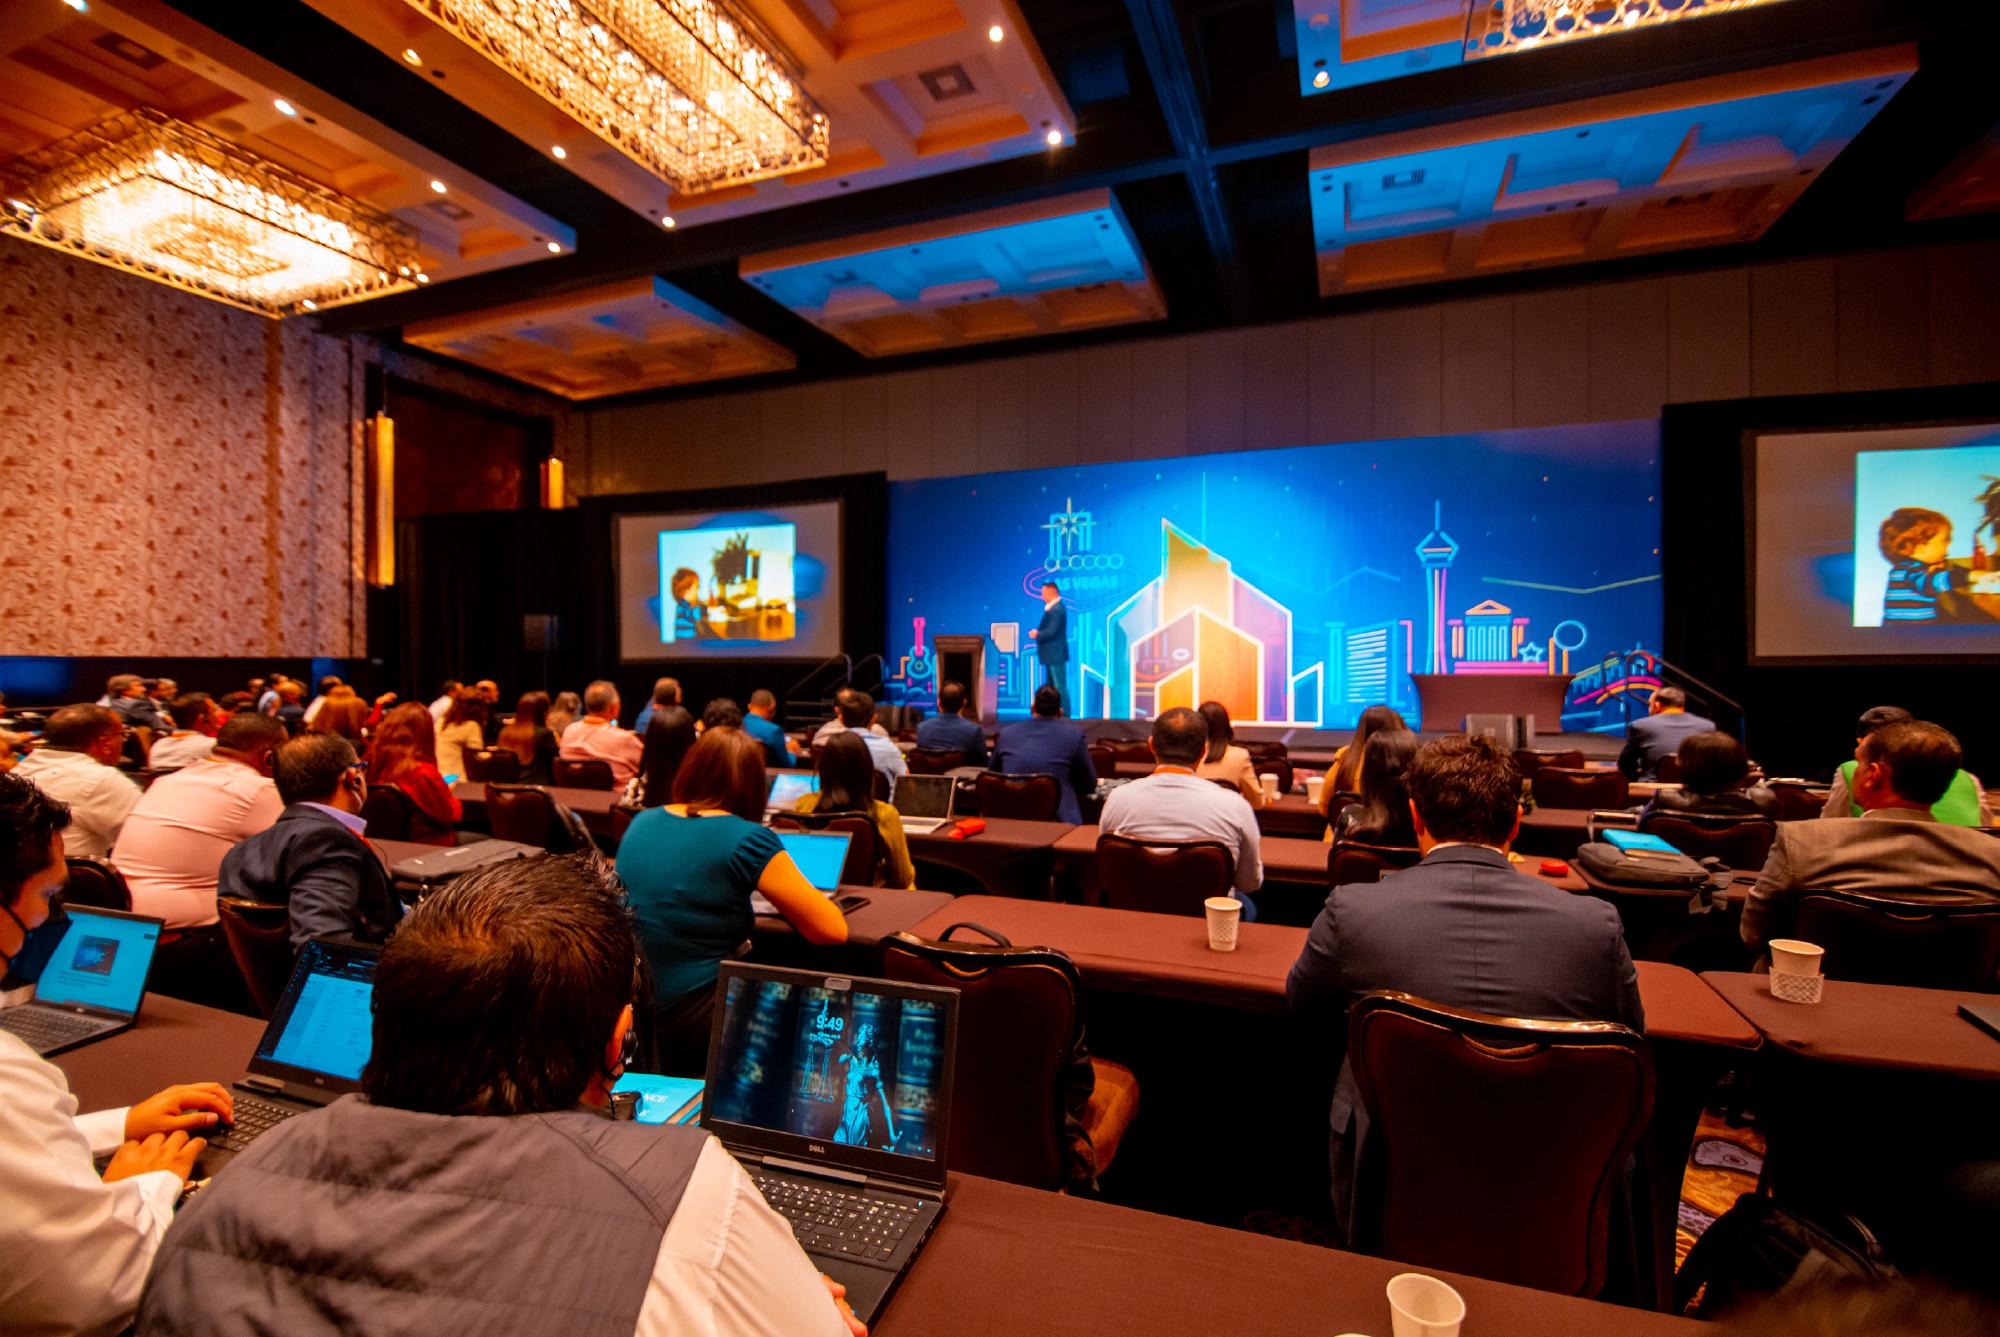
The company also publishes educational material and convenes users. Its July 15-16, 2026 conference in Guatemala City put augmented intelligence on the agenda, with sessions spanning fraud, compliance and innovation. The event advertised 11 FIBA credits. Training sits naturally beside a product whose usefulness depends on people knowing what to ask of it.
That is the most transferable idea in this company’s story. Connect the clues. Give experts access to the controls. Test a decision before allowing it to operate at speed. Then judge the outcome by what happens to real transactions and real customers. The elegance of a fraud system is partly visible in the trouble it catches, and partly in the ordinary afternoon it allows to continue.