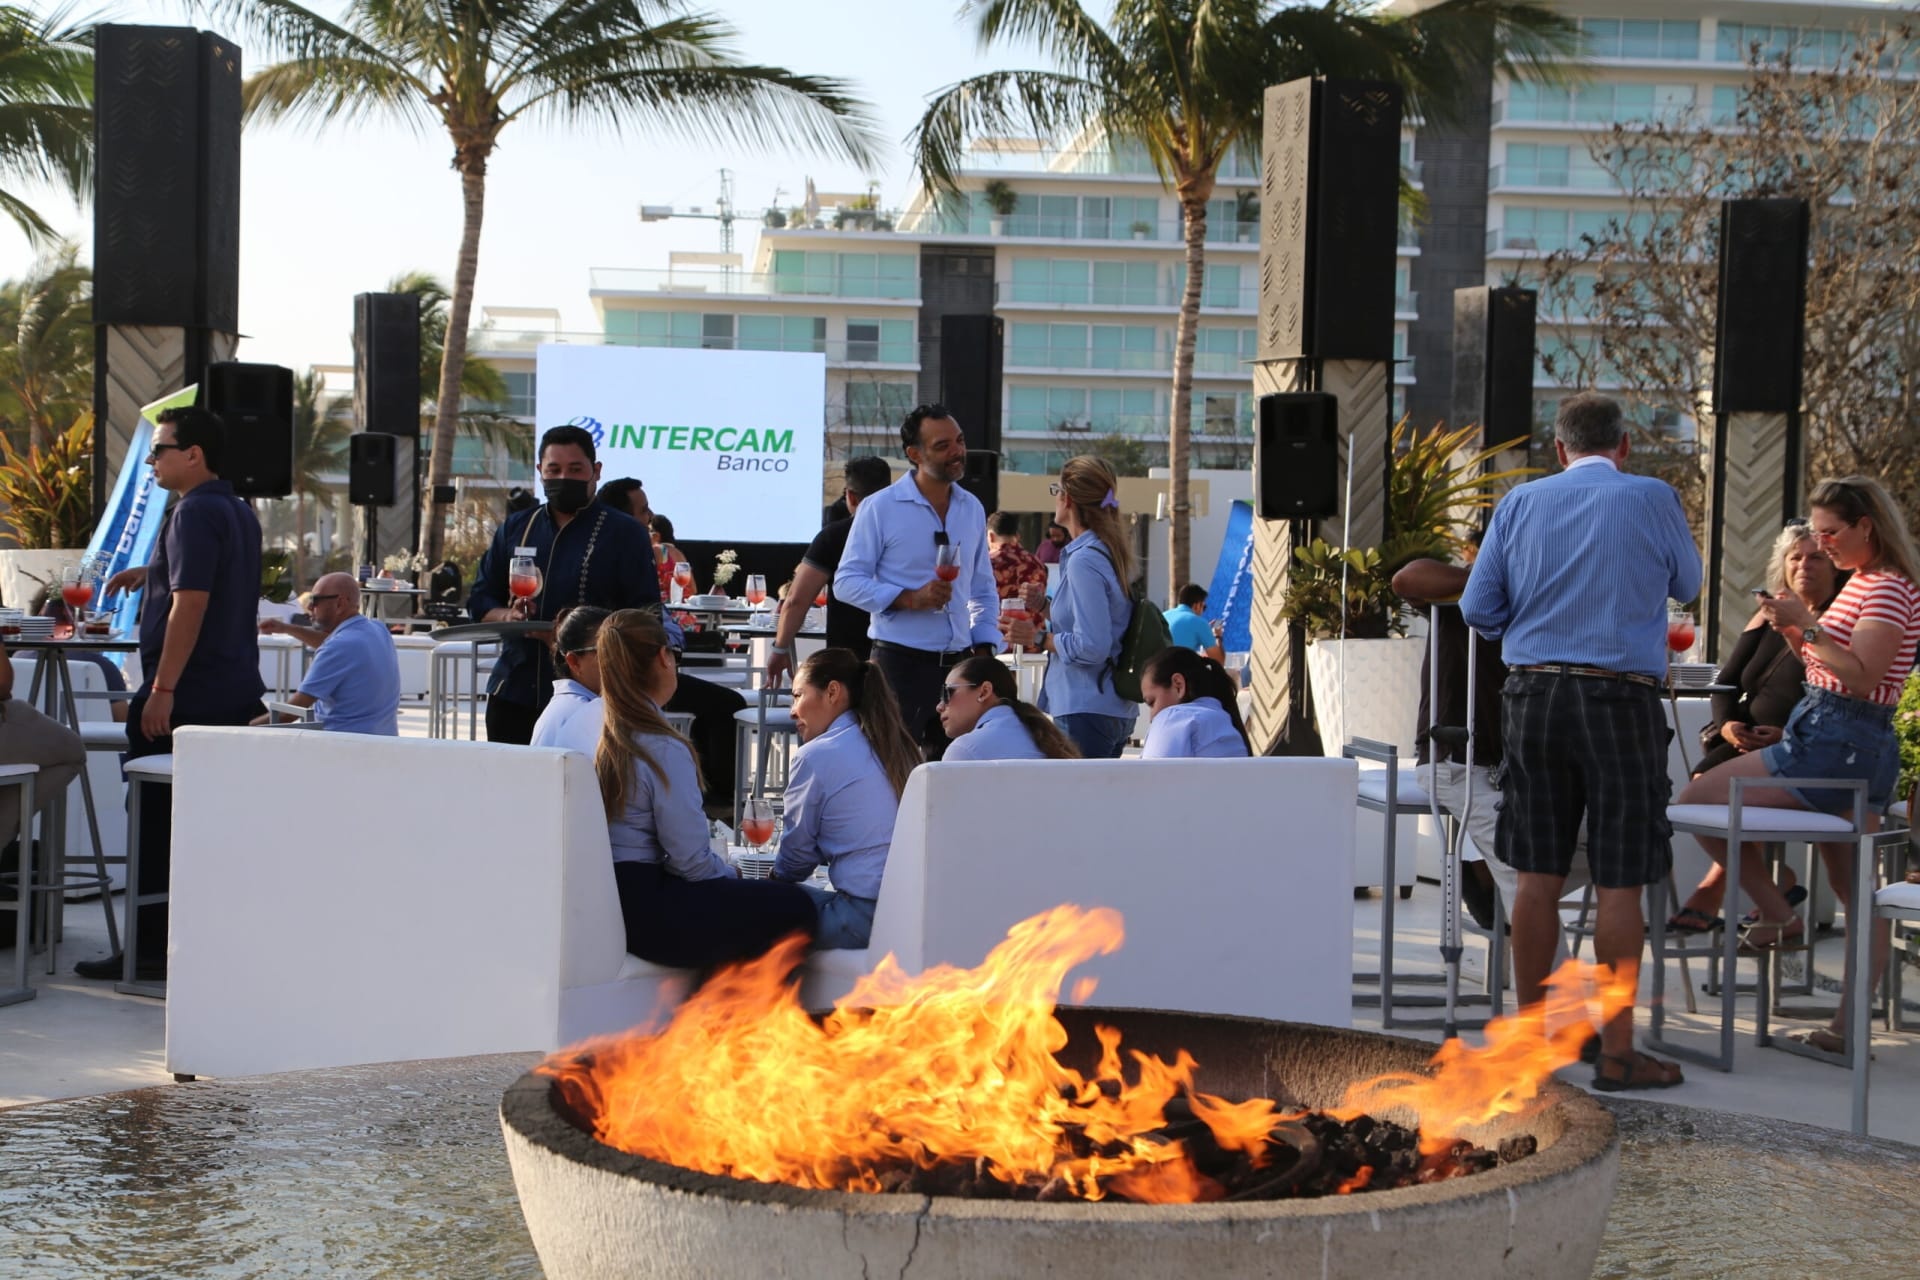
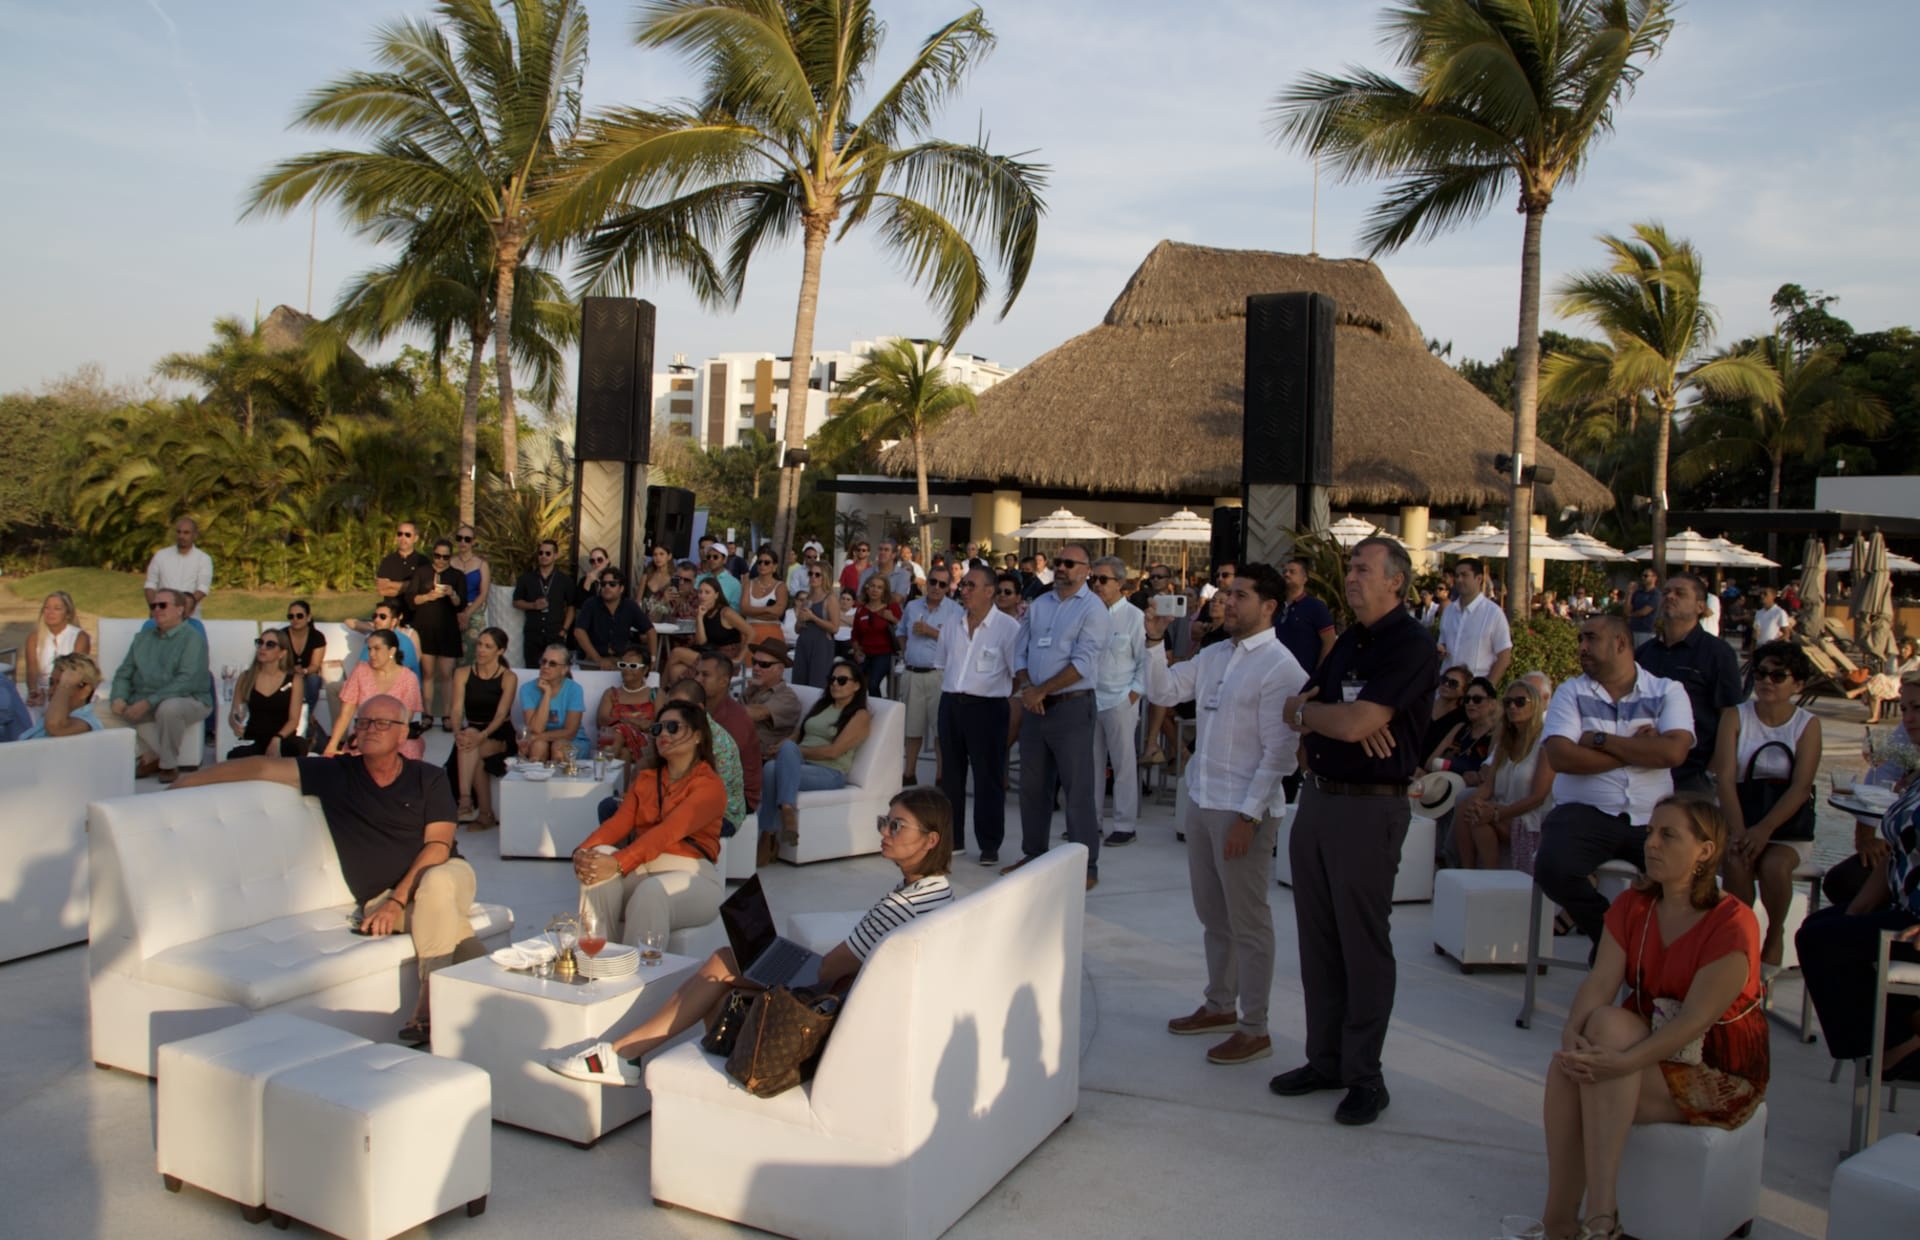
A bank launch at a beach club is an agreeable way to disguise a meeting about paperwork. On May 6, 2022, Ruben De La Mora joined Intercam colleagues at Mozzamare in Nuevo Vallarta to present a mortgage product for Americans and Canadians buying homes in Mexico. The setting offered palm trees. The proposition involved escrow accounts, trusts, payments, foreign exchange and a loan. Paradise, it turned out, came with several departments.
De La Mora was there as CEO of Intercam Banco, alongside group leader Eduardo García Lecuona, Puerto Vallarta branch director Jason Lavender and mortgage director Arnulfo Cordero. The product was called Dream Loan. Behind that cheerful name sat a practical attempt to bring several financial tasks into one banking relationship. A property purchase crosses boundaries that a holiday brochure can conveniently ignore.
Eleven years earlier, De La Mora had been explaining another sort of financial coordination in India. There, the customers included salaried workers, small business owners and rural borrowers. The challenge was to keep lending while repairing a business damaged by the financial crisis. Taken together, these episodes offer an unusually useful view of a banking executive: his work becomes visible in the arrangements around the customer.
An education in different customers
De La Mora graduated in business administration from the Instituto Tecnológico Autónomo de México. His documented career includes a period directing Banamex’s wealth franchise from June 2005 to December 2006, followed by the chief executive role at Crédito Familiar from December 2006 to April 2008. The change put two distinct financial audiences on the same résumé: people managing wealth and people seeking consumer credit.
In February 2008, he was also named director general of Grupo Financiero Associates in a corporate reorganisation involving Banamex and Citigroup entities. Banking careers often look tidier in a short biography than they do in practice. Groups, operating companies and financial products have separate names, and the executive’s responsibilities sit somewhere among them. In De La Mora’s case, the recurring field was financial services, with leadership posts spanning different parts of that field.
He moved into Fullerton’s organisation in 2008. In late 2009, he took charge of Fullerton India, succeeding G. S. Sundararajan. The Indian company belonged to the Fullerton network backed by Singapore’s Temasek. De La Mora had moved from Mexican financial institutions into a business whose branches served customers across Indian towns and cities. The job brought a new geography and an existing operation to repair.
The branch door that served two queues
The timing was awkward. Fullerton India had expanded rapidly before the crisis, building a large branch network for retail lending. When liquidity tightened and credit losses rose, that model came under pressure. Staff reductions and branch closures were already part of the company’s response during 2009. De La Mora arrived in the middle of a contraction, rather than at the beginning of an easy growth story.
One earlier arrangement separated branches for salaried customers from those serving the self-employed. By June 2011, he described a combined model: a single location could serve both groups. His explanation was operational, almost stubbornly ordinary. Running parallel premises had costs. Bringing customers into the same branch allowed the business to use its distribution network more efficiently. The consequential change was in how a branch worked.
In that interview, he called the model “customer-centric, relationship-based”. The phrase can sound pleasantly frictionless. His accompanying account was more demanding: lending continued through the crisis, while the company reorganised operations and credit processes. He said it had more than a million customers. Keeping a relationship useful at that scale meant making decisions about distribution, products and costs that could be repeated across many locations.
The company’s 2010-11 results put numbers beside the restructuring. Gross non-performing assets fell from 11.25% to 4.53%. De La Mora reported that the business broke even in August 2010 and remained profitable afterwards. The same account described a workforce reduction of nearly 35% associated with branch consolidation. Recovery had an employment cost, even as productivity improved. A fair account of the turnaround has to hold both facts together.
The leadership was shared. Shantanu Mitra, then deputy CEO, worked alongside De La Mora, while chairman Francis Andrew Rozario credited the senior management team for the recovery. That matters because a lending operation contains many kinds of judgement. Sales, underwriting, collections, funding and administration all affect the result. A chief executive can set direction; colleagues must make the arrangements function beyond the meeting room.
There was ambition beyond the repaired urban network. De La Mora spoke about expanding financial services for rural customers and small enterprises. The rural business used the Gramshakti name. In his June 2011 interview, he described 84 rural branches across six states, reaching more than 8,000 small towns and villages. His intended product range included business lending and vehicle finance, with additional services for smaller enterprises.
A two-wheeler loan and a business loan can share a branch without sharing a purpose. That was the attraction of a wider product range: the lender could remain useful as a customer’s requirements changed. De La Mora’s public account of the business kept returning to existing relationships and a distribution network already in place. The aspiration was to give that network more work worth doing.
Less trouble on the loan book
Gross non-performing assets, as reported in the 2010-11 chief executive’s statement. The bars share a zero baseline.
Back to Mexico, with a banking licence
Fullerton India’s next annual report records De La Mora’s tenure as CEO and president ending on July 31, 2011. By September, he had joined Intercam Banco as executive vice president. The transition was quick enough to give his career a clear hinge: the India chapter closed that summer, and the Mexican banking chapter began that autumn. He would become publicly identified with Intercam’s bank leadership for years.
Intercam’s corporate development brought its own changes in names and structure. A 2014 authorisation addressed De La Mora as director general of Inter Banco, part of Intercam Grupo Financiero. The bank subsequently operated under the Intercam Banco name. These distinctions matter in understanding his role. He led the banking entity within a broader financial organisation whose activities also included brokerage and investment funds.
By 2016, his signature appeared on the bank’s financial statements as executive vice president of the banking division. In the 2017 annual report, he was listed among the directors general, the proprietary board members and the executive committee. His remit therefore extended across management and governance. The same name appeared in the places where operating responsibility and formal corporate accountability met.
The institution’s direction during those years included adding banking services to existing international-payment relationships. Its customers encompassed importing and exporting businesses, savers, investors and foreigners living in Mexico. There was a recognisable opportunity in that mix: someone who already needed to move money across a border might also need a checking account, financing or help managing investments.
In 2017, Intercam Banco’s loan portfolio grew 38%, closing at 8,560 million pesos, while traditional deposit funding increased 45%. Those were bank results, produced across the organisation. They give the scale of the business De La Mora was helping lead. They also show why a bank’s customers cannot be considered separately from its funding: loans and deposits appear on opposite sides of the same operation.
“We have stood by our loyal customers”
Ruben De La Mora, June 2011
A mortgage with company
The 2022 launch in Nuevo Vallarta made that broad banking proposition concrete. One-Stop Banking brought together escrow, trusts, payments, currencies, investments and Dream Loan. For an American or Canadian buying in Mexico, the services were being presented as connected pieces of a transaction. A mortgage was the most visible addition, but the surrounding financial tasks were part of the pitch.
The choice of venue gave the presentation a social dimension. The gathering included executives responsible for the group, the bank, the local branch and the mortgage business. That combination of roles was itself informative. Senior leadership could introduce the offer, while the local and specialist teams would be closer to the prospective customer’s questions. A beach club may improve attendance; somebody still has to understand the application.
Intercam’s approach to international customers also emphasised personal attention and a designated relationship manager. Language and local assistance were part of the offering. The intended convenience lay in having someone accompany the customer through several services, rather than treating each task as a separate introduction. De La Mora’s presence at the launch placed him within that effort to extend the bank’s relationship with its foreign clientele.
The scene is far removed from the Indian restructuring in its outward appearance. Yet there is a connection in the business arrangements: several needs gathered around one customer relationship. In India, that appeared in a branch serving different borrower groups. In Mexico, it appeared in a banking offer connecting a home purchase to payments and other services. The resemblance is an editorial reading of the two episodes, rather than a claim that the products or markets were alike.
The dates at the end of the nameplate
De La Mora was still named director general when the bank’s audited 2022 financial statements were authorised on March 27, 2023. He also appeared as a proprietary board member in Intercam Banco’s 2024 board listing. These later records extend the documented career beyond the launch photographs, into the less photogenic business of accounts and corporate oversight.
A further institutional chapter followed in 2025. On August 19, Mexico’s finance ministry announced an agreement for Kapital Bank to acquire a significant portion of Intercam Grupo Financiero’s operations, in the context of the temporary intervention that had begun in June. A separate group governance notice recorded the termination of the previous directors’ terms on August 28. De La Mora was among those listed.
His career is therefore best read with dates attached to its titles. The interesting thread runs through the work: wealth management, consumer lending, an Indian restructuring and a Mexican banking operation serving cross-border customers. Each setting demanded a different arrangement between institution and client. The useful question at the beach-club launch was the same one behind a reorganised branch: once the customer arrives, can the business actually serve the need that brought them there?