A money transfer has two customers. One is holding a phone. The other may be standing outside a bank. Make the first person’s experience effortless and the second person’s awkward, and you have solved only half the problem. Placid Express is interesting because its business stretches across that gap: the digital instruction to send money, and the very physical question of where someone can collect it.
- Send to bank accounts, participating cash-pickup locations and selected mobile wallets.
- Bangladesh is a particular strength, with a wider international payout network.
- Other remittance businesses can buy access to that network, too.
Founded in 1996 by Dr. Kamal U. Ahmed and Mohammed H. Rashid, the company grew around sending money home. Ahmed was a physician, an unusual starting point for a financial services founder. The founding premise was straightforward: transfers should be easy, affordable and safe. The interesting work lies in making those three promises coexist when the sender and recipient use different currencies, institutions and habits.
The three-day problem
When Placid introduced its digital service in 2014, the old business acquired a new complication. At a counter, cash gives the transmitter immediate certainty about the funding. Online, an instruction to debit a bank account is a different proposition. Before sending money onward, how confidently can the company establish that the account belongs to the sender and can fund the payment?
The historical choice was unattractive. Card payments could be quick but expensive. Bank-funded ACH transfers could be cheaper, while micro-deposit verification introduced a wait of three to five days. Placid first built its own fraud-detection system. Early approvals rose from 40% to 62%. Better, certainly. But a substantial share of customers still could not get an immediate approval.
Better information.
Earlier approvals.
The next move was to integrate Plaid’s Auth, Identity and Balance products: confirm account details, check ownership and inspect available balances. Plaid’s 2018 account reports instant ACH approval rates above 80% after integration. These are historical partner-reported results, not a promise about today’s transfers. Their significance is practical: better information helped Placid decide which payments it could release sooner.
“We can expedite transactions without waiting the three-day ACH confirmation period”
Ahsan Choudhury, then CTO / Plaid case study
That distinction matters. Faster verification does not magically make bank settlement instantaneous. It gives the transmitter a better basis for accepting risk. For anyone building a payment product, there is a useful lesson here: identify the uncertainty causing the delay, then improve the evidence behind the decision. A faster animation on the confirmation screen will not do that job.
The counter is part of the product
Now consider the receiving end. Placid’s spotCash! service lets a recipient collect from participating institutions without the sender having to choose one specific branch. The app’s Bangladesh listing names banks including Agrani, Islami Bank, Sonali and Janata. For a family organizing a collection, the benefit is wonderfully ordinary: a choice of counters rather than a single prescribed destination.
Cash is one option. The Bangladesh app also lists deposits to bank accounts and transfers to bKash, while its release history records Nagad support. Those alternatives serve different routines. An account deposit suits someone who wants money in the bank; a wallet transfer suits someone already using that wallet. The sensible starting question is what the recipient can use easily.
The network has a long paper trail. In November 2003, One Bank agreed to handle Bangladesh-bound Placid remittances from expatriates in the United States and Canada. Two decades later, Midland Bank described disbursements through its branches and agent banking centers. Shahjalal Islami Bank signed another agreement in September 2024. Each agreement makes the service more useful at its destination.
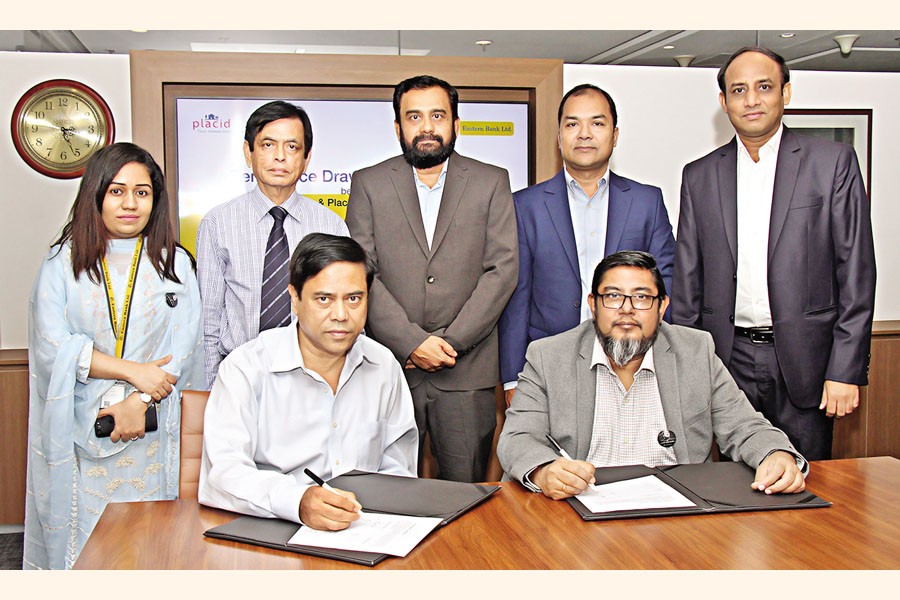
The relationships also connect different sending markets. An August 2023 report describes Eastern Bank’s agreement with Placid’s Malaysian subsidiary, signed by Rashid and Eastern Bank’s Mehdi Zaman. Earlier, a company announcement reported Bangladesh Bank recognition at an August 2015 ceremony in Dhaka. Together, those records show how closely the company’s history is tied to formal channels for Bangladeshi remittances, even as its service reaches other destinations.
There is more geography here than Bangladesh. Morocco’s Al Barid Bank describes Placid payouts across its own branches and Barid Cash locations, collected using a unique code. It also describes the company’s presence in more than 30 countries across four continents. That is a useful way to understand Placid’s position: international reach assembled from local institutions people can actually visit.
The fee is only one number
What does it cost? The spotCash app advertises fees starting at $1.99. That is a starting price, not a tariff for every transfer. Placid also states that it earns money when converting currencies. A sender comparing providers therefore needs two numbers together: the total paid and the amount the recipient receives. A small visible fee does not settle the comparison.
For a new sender, the published process begins with an account and identity verification. Then come the amount, recipient and delivery method; the quote shows what the recipient should receive. Placid lists debit cards and ACH bank payments as funding options. Before confirming, check that the recipient’s details match the required format and that the collection method fits their plans. The convenience depends on getting those ordinary details right.
Western Union, MoneyGram, Ria, Remitly, Xoom and Wise offer alternatives. Which works best depends on the route, live quote, payment method and receiving preference. Placid’s particular appeal is the combination of digital initiation and established payout relationships. That appeal weakens if the desired destination is unsupported, the preferred collection method is unavailable, or another provider delivers more usable money for the same outlay.
A network other companies can rent
There is another customer behind the individual sender. Placid’s public company description offers money transfer businesses a “Join the Network” service: access to its payout connections, with optional proprietary transfer software. Small businesses can also become agents and earn commissions. The infrastructure built for Placid’s own customers can consequently become something another company buys rather than recreates.
That is the detail worth carrying away. Placid competes on what happens after someone presses send: verifying the funding, reaching a partner institution and making collection practical. Its European governance page lists compliance, risk, audit and data-protection functions alongside leadership. The machinery is extensive because a simple transfer requires so many decisions. At the destination, all that work should feel like money arriving where it belongs.