At thirteen, Jonathan Steinberg had a subscription to Value Line. Some boys collected baseball cards; his chosen reading came with earnings figures. He later recalled the subscription in an interview. His teenage reading had required considerably more tables than most. The detail is small, but useful. Long before WisdomTree, before exchange-traded funds, before the present enthusiasm for putting investments on blockchains, there was a boy interested in how businesses worked.
Finance was hardly an exotic subject in the household. His father, Saul Steinberg, was a prominent financier. Jonathan, usually called Jono, grew up in New York with access to a world most aspiring investors encountered through the business pages. That beginning supplied proximity and expectations. It did not supply the finished enterprise. His own route would include a publishing business that closed its flagship magazine, years of index development, and a substantial change of occupation.
Today he runs WisdomTree, Inc., the parent company of WisdomTree Asset Management. The founder’s official tenure reaches back to 1988; the ETF business arrived in 2006. Between those dates lies the interesting part: an editor learning that a financial idea could travel inside something other than a sentence.
A magazine with a different ambition
Steinberg attended Wharton and left in 1986 to join Bear Stearns. There he worked in mergers and acquisitions until 1988. The next move took him into publishing. He bought the Penny Stock Journal, renamed it Individual Investor and broadened its editorial ambition. The title was practically an instruction: pay attention to the person making the investment.
By 1991 he had taken the business public. In 1996 its publishing interests expanded to include Ticker, aimed at brokers and investment advisers. He also published a book that year, Midas Investing. The classical reference was bold, although the practical purpose was straightforward: explain the stock market to ordinary investors. The publisher was Times Books, a division of Random House.
A 1999 interview captures a business already trying to travel beyond print. Individualinvestor.com had its own editorial and research staff; its material was syndicated through services including Yahoo! Finance and AOL Digital Cities. For Steinberg, financial information was something to distribute widely. The medium was negotiable. Readers were moving onto screens, and his company was following them.
He was also willing to have his stock selections judged in public. The 1999 interview described him as a six-time winner of The Wall Street Journal’s Dartboard Competition. That detail belongs to the publishing period, when a financial editor could make a reputation through individual picks. His later business would ask investors to evaluate an entire set of portfolio rules instead.
The editor discovers a new edition
In 1999, the magazine covered the Nasdaq-100 tracking shares familiar to traders as the QQQ. Steinberg’s attention settled on the ETF structure itself. Here was a package offering exchange trading, visible holdings and tax advantages. A magazine could explain a portfolio. An ETF could allow someone to buy one.
“I found ETFs first editorially.”
Jonathan Steinberg, 2016
The timing was awkward. Individual Investor closed in 2001 amid the technology downturn. Advertising and newsstand revenues had fallen. The subscriber list went to Kiplinger’s, and Steinberg continued with index development. Reinvention sounds rather jaunty when printed in a company history. In practice, this one involved a search for financial backing that lasted years.
Research director Luciano Siracusano worked with him on investment rules. The surviving project required investors, an argument and a product people could actually use. The magazine had given Steinberg experience in research and a circle of relationships. Neither could be deposited at a bank as revenue. Both would matter when he started assembling the next business.
Individual Investor
First 20 ETFs
WisdomTree Onchain
A professor, a financier and twenty funds
One relationship had begun on the printed page. Wharton professor Jeremy Siegel had been a columnist for Individual Investor. Steinberg approached him about indexes weighted by dividends rather than the stock-market value of companies. Siegel tested the proposition and became an adviser and investor. A former columnist had acquired a rather more involved assignment.
Michael Steinhardt, the hedge-fund investor, also examined the research and became a backer and chairman. The two relationships brought academic authority and financial support to an enterprise that needed both. They also gave the public something more tangible than another founder’s conviction. The investment rules could be inspected, argued over and put into products.
In June 2006, WisdomTree launched twenty ETFs. The initial family used dividend-weighted indexes and included international strategies alongside American ones. In conventional capitalization weighting, larger market values earn larger portfolio weights. WisdomTree’s approach gave a different role to the cash companies paid shareholders. The disagreement concerned the contents of the basket, down to the proportions.
There was a commercial argument tucked inside the investment argument. Widely available indexes invited fierce competition on price. Steinberg wanted proprietary rules that could distinguish his firm’s products. A small business entering a market occupied by much larger institutions needs an answer to the obvious question: why should anyone choose you? WisdomTree’s answer was built into the index.
The argument could be debated without becoming a referendum on whether Steinberg liked the stock market. In his own writing in 2014, he treated the boundary between active and passive investing as increasingly unhelpful. A fund could follow an index while the index embodied deliberate choices. Calling the result passive did not make those choices disappear. Financial labels occasionally behave like dinner guests: they stay after their usefulness has departed.
He also argued that the structure could accommodate a range of strategies. Investors might want dividend growth, currency hedging or different portfolio characteristics. The attraction was the flexibility to put those choices into a familiar trading format. This helps explain his preoccupation with wrappers: their practical features influence which ideas can reach a customer, and how easily that customer can use them.
A fund becomes a calling card
By April 2013, WisdomTree managed $24.3 billion and offered 47 ETFs. One original product had become particularly conspicuous: the Japan Hedged Equity ETF, DXJ. It combined Japanese equity exposure with currency hedging, addressing two decisions investors might otherwise have had to make separately.
At that point DXJ had attracted $3.5 billion since the beginning of the year and held $5.1 billion. For a company selling differentiation, the fund offered a legible example. Investors could understand the exposure, decide whether they wanted it and act. Product design had become a sales argument with a ticker symbol.
June 2006
April 2013
Successful funds create their own management questions. A prominent strategy can draw attention and assets while leaving the business dependent on its continuing appeal. The subsequent push to broaden WisdomTree’s offerings therefore belongs to Steinberg’s story as much as the launch does. Building the first product and building an enduring institution are different jobs, even when the same person occupies the office.
Room for people who like themselves
His public life has another connection to financial media. Steinberg married journalist Maria Bartiromo in 1999. His own career had already crossed reporting, research and finance; the marriage joined two people whose working lives revolved around making markets intelligible, though from different professional positions.
His management preferences supply a less formal detail. In a 2018 conversation, he described hiring people who were happy and comfortable with themselves. A sabbatical program for employees reaching ten years was another expression of how he wanted the company to work. In an industry accustomed to measuring retention in assets, retaining colleagues was part of the design.
Awards supplied an opportunity for dry humour. Discussing ETF.com’s lifetime achievement recognition in 2016, he wondered whether the wording suggested an ending. The subsequent years have made that interpretation difficult to sustain. By May 2022 he had joined the board of Fnality International, a financial technology company. In July 2025 he joined The Digital Chamber’s advisory board. His attention was moving deeper into financial infrastructure.
The wrapper changes again
By 2021, Steinberg was publicly discussing blockchain as another structure capable of changing financial services. The attraction followed a familiar pattern. He had once examined what ETFs allowed investors to do. Now he was examining how ownership, transfers and access might work when fund shares moved through blockchain infrastructure.
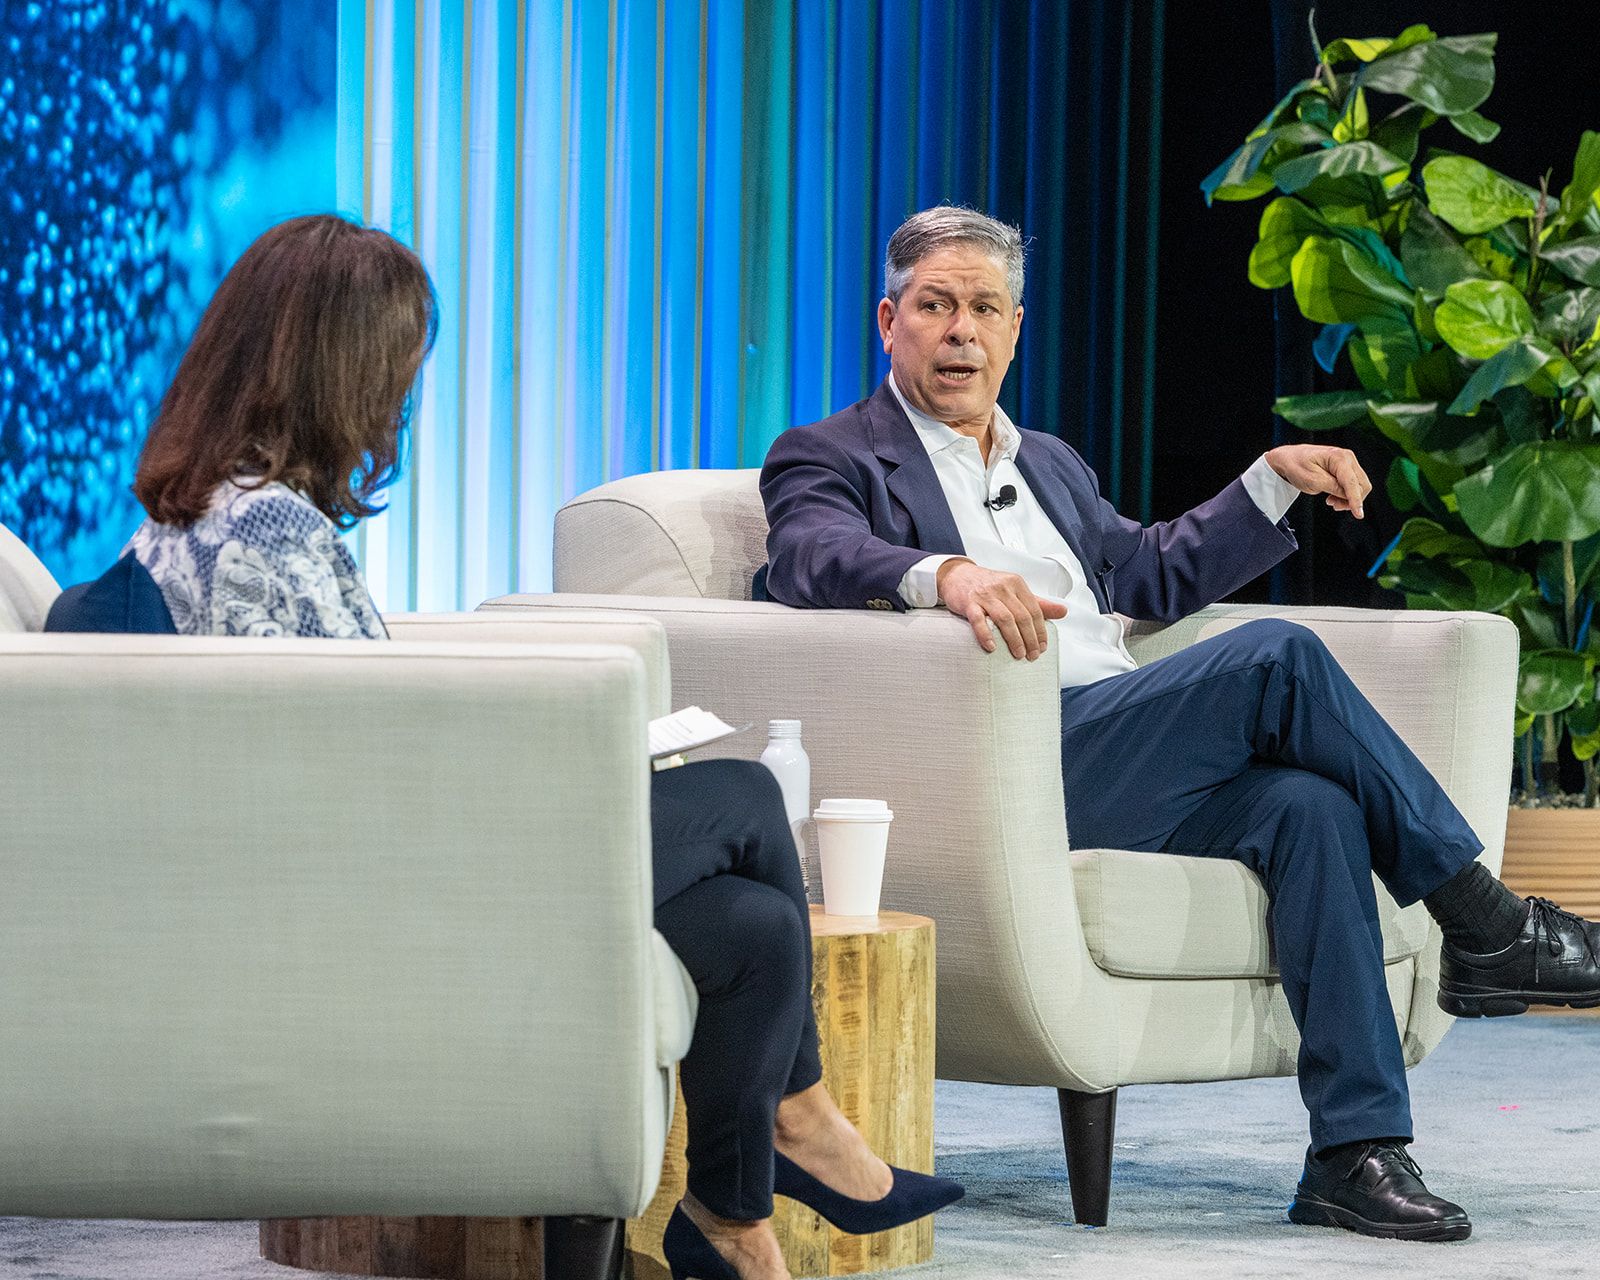
At INSITE26 in Denver in June 2026, he returned to the question behind the strategy: what could do to ETFs what ETFs had done to mutual funds? He described committing money to tokenization before the subject became a routine industry conversation. The decision, he said, had made him uncomfortable. An executive’s confidence can be interesting; the admission of discomfort tells us rather more about the decision.
On September 29, 2026, WisdomTree introduced WisdomTree Onchain, bringing its tokenized funds and related platforms under a common identity. It reported more than $1.2 billion in tokenized fund assets. That figure gives the latest chapter a measurable size, while leaving its eventual importance open. A company can have a working business and a much larger ambition at the same time.
WisdomTree’s reported tokenized fund assets
For Steinberg, the recurring subject is access. First came research someone could read. Then a fund someone could buy. Now comes infrastructure intended to change how investments are held and moved. Each version requires customers to find the change useful. The wrapper has changed repeatedly. The teenage reader of financial tables is still asking what belongs inside it, and how to get it into someone else’s hands.