John Kemper’s grandmother had a rule: no banking talk at the dinner table. In a family whose name had become part of Missouri’s financial history, that took some resolve. Mildred Kemper preferred the many other subjects the world had to offer. One suspects a discussion of loan growth would have had a short and unsuccessful evening.
Her grandson eventually chose banking anyway. Born in Kansas City, he moved to St. Louis at seven, when his father’s work brought the family across Missouri. He was the oldest of four children. His sisters Ellie and Carrie went into acting and writing; John’s professional life took a different direction. The family connection was unmistakable. The route into the job was less direct than the surname might suggest.
The consultant who stayed for the answer
Before Commerce, Kemper worked at McKinsey & Company. His assignments involved strategy and operations, and his work took him through the firm’s New York and Chicago offices. Consulting offered access to different businesses and their difficult questions. It also came with a familiar limitation: the adviser can recommend a course of action, then leave before the consequences arrive.
Kemper wanted the part that came after the recommendation. In 2018, he described wanting to see proposed solutions through to implementation. That is a rather practical career ambition. It makes room for the unglamorous work of persuading colleagues, changing processes and returning to a decision long after the presentation has been filed away.
A strategy assignment at Commerce brought him back to St. Louis in 2007. After eight months working as a consultant on the study, he joined the staff. There was a family business to consider, certainly, but there was also an operating business he had been able to examine at close range. His experience elsewhere gave him something against which to measure it.
“I wanted to carry the answers to problems through to their execution.”
John Kemper, 2018
A history student in the executive suite
Kemper’s education began with subjects that look backward before they prescribe anything: history and political science at Stanford, followed by economic history at the London School of Economics. He later earned an MBA at Northwestern’s Kellogg School of Management. His public LinkedIn profile places his Stanford years between 1996 and 2000.
That combination puts several kinds of inquiry on the same résumé. History asks how institutions arrived at their present arrangements. Political science examines how authority works. Economic history follows the relationship between money and events over time. The business degree adds the formal vocabulary of management. The sequence is an interesting preparation for a bank with a very long institutional memory.
His McKinsey work included financial services and airlines, businesses with quite different customers but considerable operational complexity. Commerce’s leadership biography also identifies his involvement with Visa’s executive client council and civic organizations around St. Louis. His professional world extends from payment networks to the city where he works, a useful range for someone responsible for both commercial capabilities and local relationships.
Eleven years before the handover
The early Commerce years involved more than a title in strategic planning. By the time the board promoted him in February 2013, Kemper had worked on strategy and acquisitions, overseen credit card businesses and chaired Capital for Business, the bank’s private equity subsidiary. As chief administrative officer, his responsibilities had also encompassed credit and other risks, legal matters, compliance and human resources.
Those functions expose different sides of the same institution. A card business needs customers to use its product. A risk function has to consider what happens when things go wrong. Legal and compliance teams set boundaries. Human resources deals with the people expected to make the whole arrangement work. His progression brought those concerns into the same career before the chief executive appointment.
The 2013 promotion made him president and chief operating officer of Commerce Bancshares, responsible for strategy and line operations alongside market and business leaders. He joined the board in September 2015. By then, his role had moved from studying the organization to sharing responsibility for its day-to-day direction and its governance.
- 2007Joins Commerce
- 2013President & COO
- 2015Board director
- 2018Chief executive
The succession announcement arrived on April 2, 2018, with the transfer taking effect on August 1. John became chief executive at forty. His father, David, remained executive chairman, working on strategy, customer relationships and other responsibilities. Lead director Andy Taylor described a succession process developed over several years. The change had a date; the preparation had occupied much longer.
The arrangement left two generations involved, with distinct responsibilities. It also placed John in charge of a publicly traded company, where family continuity sits alongside the obligations owed to outside shareholders. Commerce’s shares trade under CBSH. Its enduring family association is part of the story, but the institution’s performance has to appear in accounts that everyone else can read.
What a “super-community” bank has to deliver
Commerce describes its approach as a super-community bank model. The phrase is a compact statement of a demanding proposition: provide sophisticated financial products while preserving personal service in individual markets. The company’s annual filing identifies local knowledge, relationship banking and a broad product offering as central parts of that approach.
The geography matters. Commerce’s principal offices are in Kansas City and St. Louis, and its branch network is concentrated in the Midwest. Its commercial payments business serves customers nationwide. A local relationship can therefore sit beside a service that travels much farther. For Kemper, running the business means accommodating both scales within one organization.
That model is visible below the chief executive’s office. Southern Illinois market president Matthew Gomric described Commerce in 2019 as a community-oriented bank whose culture encouraged collaboration with colleagues and clients. He also pointed to investment in payments, wealth advice, data science and core banking systems. The mixture is revealing: personal attention requires people, while an increasingly complicated service requires substantial machinery behind them.
The machinery beneath the manners
Modernizing a bank involves work that customers may never see. Commerce has worked with Temenos on moving from legacy systems toward a modern platform for deposits and loans. The objectives included processing transactions in real time and giving employees a more complete view of a customer’s relationship with the bank.
A core banking system records and processes the daily activity of financial accounts. Changing it touches the foundations of the service, rather than simply refreshing the appearance of an app. For a bank selling dependability, the work has an additional test: the new capabilities must be introduced while customers continue using the existing business.
The customer argument for that investment is straightforward. A banker equipped with better information can spend less time navigating separate systems. Faster processing can make the service more useful. Technology and personal attention meet at the point where an employee is trying to answer a customer’s question. The infrastructure is remote from the conversation, yet it helps determine how well that conversation goes.
The acquisition that took years to reach
On the June 2025 call announcing the FineMark agreement, Kemper said Commerce had been building its relationship with FineMark’s team for almost five years. That is a long courtship by the standards of a press release. The discussion emphasized complementary capabilities: FineMark’s private banking and wealth relationships, alongside Commerce’s capital, operational resources and wider range of services.
The diligence was substantial too. Finance chief Charles Kim described a credit review that included outside participation and covered nearly ninety percent of FineMark’s commercial loan portfolio. In other words, the transaction involved getting to know both the people and the assets. The business case depended on more than compatible introductions.
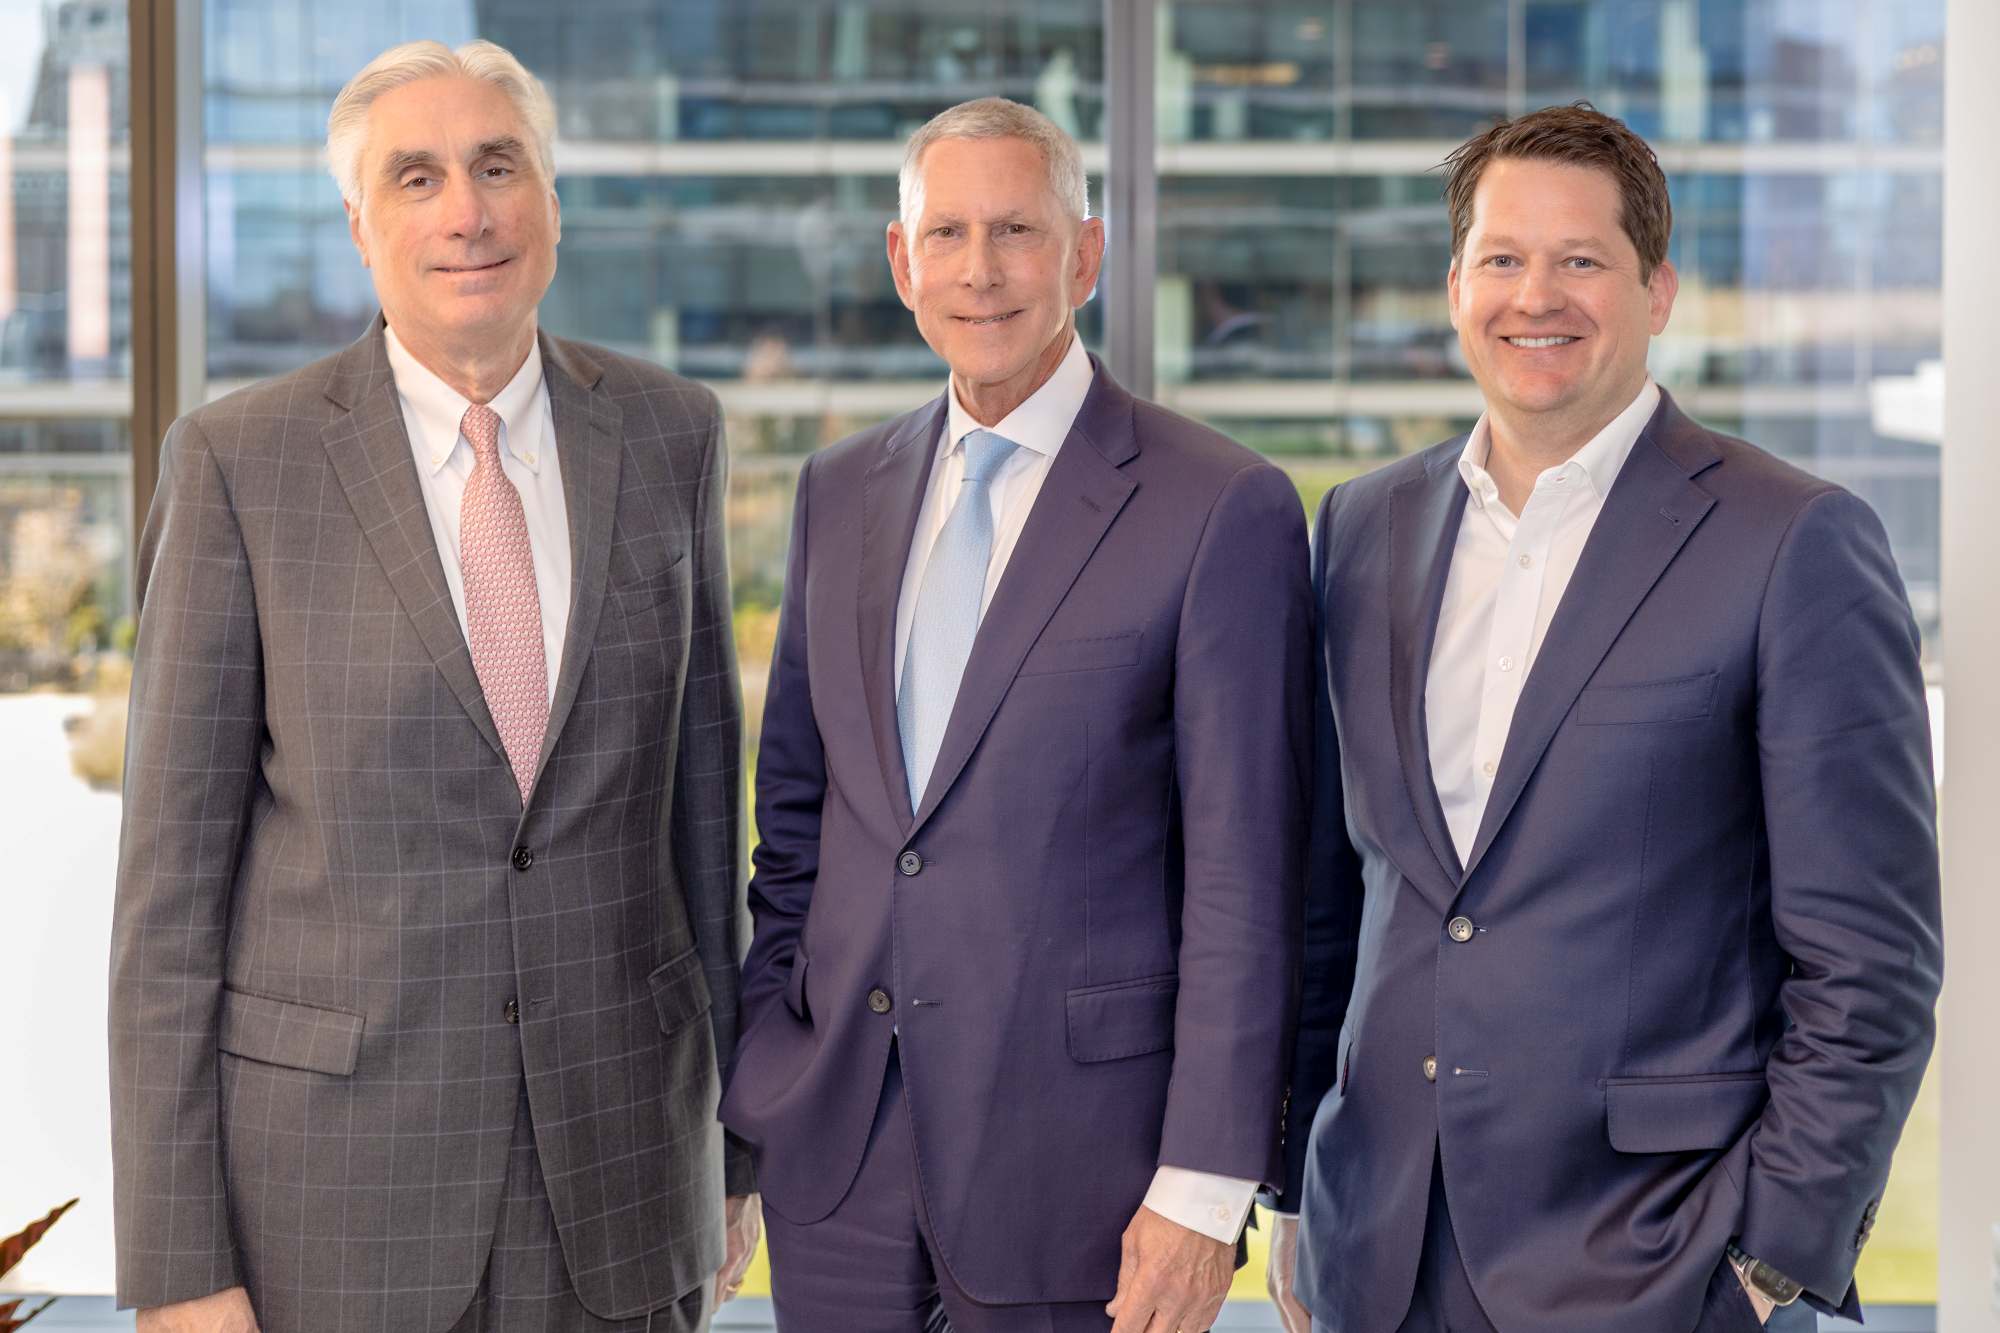
The acquisition closed on January 1, 2026. Commerce reported approximately $36 billion in assets and $90 billion in assets under administration at closing, with the latter describing assets administered for clients rather than the bank’s own balance sheet. FineMark expanded the wealth business in Florida and added locations in Arizona and South Carolina.
The structure also preserved recognizable relationships. FineMark continued as a division of Commerce Bank, with Joseph Catti leading that business and becoming chairman of Commerce Trust. For a transaction built around private banking, continuity in the people looking after clients was part of the announced plan. The larger organization was being assembled around relationships already in place.
A wider brief, and a very current scorecard
Another addition followed on October 1, 2026, when Commerce completed its acquisition of Nolan & Associates, the St. Louis investment banking firm. The deal added advice on acquisitions, raising capital and changes in business ownership. Nolan retained its leadership, employees and Brentwood office. The transaction’s financial terms were not disclosed.
For a commercial banking customer, those are consequential moments: buying another company, finding new capital, or arranging a sale. Adding the advisory business broadens the kinds of decisions Commerce can help a business owner address. Alongside FineMark, it shows the institution extending its capabilities in both business advice and private wealth.
For the three months ended September 30, 2026. Revenue mix calculated from reported figures.
Results released on October 20 put the third quarter’s net income at $155 million, compared with $141.5 million a year earlier. Diluted earnings were $1.08 a share. Non-interest income represented 37.5 percent of total revenue, illustrating how much of the business sits beyond the interest earned on loans and securities.
The same figures contain the ordinary friction of running a bank. Net interest income fell from the previous quarter, even as average loans increased. The accounts offer several measures at once, each describing a different part of the job. Kemper’s responsibility now extends from the judgment behind an acquisition to the accumulated decisions inside a quarterly result.
In his letter accompanying the 2025 annual report, he returned to the relationship between understanding a problem and acting on it. Commerce’s theme was “From Insight to Action.” Years after he left consulting, the concern is familiar. An answer is useful. Staying to put it into practice is the work he chose.