On July 22, 2009, John Gabbert took a screenshot of his company’s bank balance. PitchBook had $22,000 available and owed $100,000. A founder selling information about other people’s investments had acquired a painfully intimate understanding of his own.
The company was two years old. Its early office had no windows and measured about 200 square feet. At one point seven people worked inside it. For the first 20 months, Gabbert had stayed with friends in San Francisco while his wife and children were back in Seattle. The business was consuming money and time, including the kind of family time that never appears as an expense.
A screenshot preserves a moment without supplying an ending. Gabbert could see the balance; he could not yet see the company Morningstar would eventually buy. That uncertainty makes the image more interesting than the acquisition announcement. He had to decide what to do while the numbers still looked like this.
Two figures from the screenshot Gabbert saved. A rather uncomfortable souvenir.
An education in the unanswered phone
Gabbert’s preparation included a great deal of calling people who had not asked to hear from him. While studying at the University of Washington, he worked in telephone sales. After graduation, he held sales jobs at AT&T and John Hancock. Rejection arrived often enough to become familiar.
In 1998 he moved to San Francisco and joined VentureOne. Over nine years, his responsibilities ranged across operations, research and private markets. The jobs gave him a view of how financial information was collected, packaged and sold. They also put him close to customers who needed something the existing products did not provide.
His proposal was practical: combine information about investment providers with private equity deal information in a database. He spent years trying to get the idea approved internally. The answer kept coming back negative. In 2007, he founded PitchBook.
The distinction between wanting to be a founder and wanting to solve this particular problem mattered to him. In his own account, entrepreneurship followed the frustrated proposal. There was already a customer need he understood. Starting a company was the available way to pursue it, complete with all the duties that do not fit on a product sketch.
One call, several years
PitchBook arrived as the financial industry was entering a crisis. Its prospective customers had reasons to scrutinize spending. Its prospective backers had reasons to keep their money. Gabbert has described receiving more than 200 refusals while finding 18 investors willing to participate. Expertise in the investment business did not exempt him from asking repeatedly.
One of his calls went to Joe Mansueto, Morningstar’s founder. Morningstar invested $1.2 million in September 2009. The relationship would last well beyond the immediate financing problem. In January 2016, Morningstar added another $10 million.
That second investment came with a choice. Gabbert said PitchBook had received offers for larger amounts at higher valuations. He chose the existing partner, emphasizing their shared approach to information and culture. A financing decision was also a decision about whose company he would be keeping.
“PitchBook will never cease to be a work in progress.”
John Gabbert, 2016
In October 2016, Morningstar announced an agreement to acquire the rest of PitchBook. The transaction valued the company at $225 million. Morningstar already owned about a fifth and expected to pay approximately $180 million for the remaining interest. Those figures describe the company and the transaction; they are not a measure of Gabbert’s personal proceeds.
The progression had a patient rhythm: an initial investment, years of working together, another round and an acquisition. A cold call could open a conversation. The relationship still had to survive the ordinary work that followed it. Gabbert’s financing story is often told through the dramatic call, but the seven-year interval matters just as much. The buyer had time to get to know the business.
He would remain in charge. The founder who had spent years asking for capital was going to keep doing the operating work after the sale.
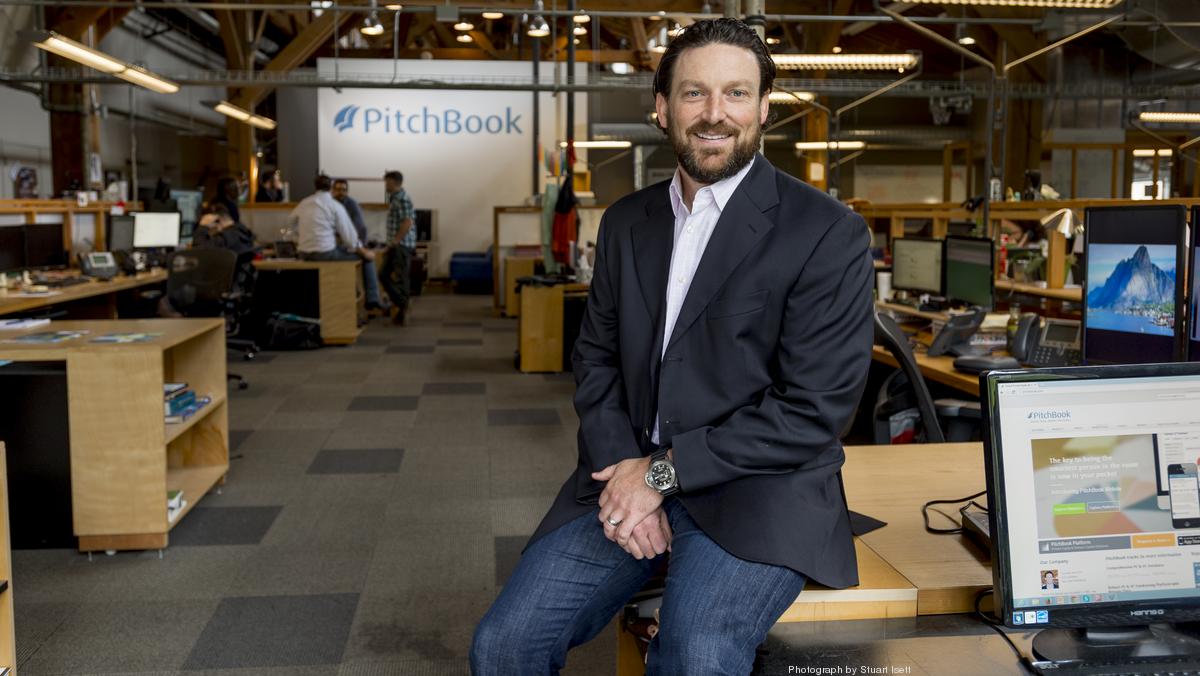
A database learns new jobs
The original proposition had room to grow because financial questions tend to arrive in company. Someone researching a deal may also need to understand the buyer, the investors behind a fund, or the companies that resemble a potential acquisition. Each answer makes another question possible.
PitchBook expanded from private equity into venture capital and other parts of the markets. It developed ways to investigate companies, investors and funds, then added research and tools for working with the information. The work involved collecting and checking financial details that were often difficult to obtain.
The scale was visible by 2016. An acquisition fact sheet listed coverage of roughly 718,000 companies, 35,000 funds and 1.17 million people. These were different kinds of records connected around the same financial activity. Their usefulness depended on helping a customer move between them.
Connected information → more questions answered
Getting information to customers required a working sales organization, too. Gabbert acknowledged an early mistake: salespeople scattered around the country were difficult to coordinate. PitchBook consolidated around teams in Seattle and New York and adopted a more consistent approach. A founder trained in selling still had to learn how to organize other people doing it.
For a data business, coordination reaches beyond sales. Someone has to decide what a record means, how to check it and how to make it useful beside another record. The customer sees a search result or a comparison. Behind that screen sits the less picturesque work of maintaining a shared method. Growth makes those decisions more numerous; it does not make them disappear.
That admission gives the growth story some texture. Understanding a market did not supply a finished organization. The company had to change its own methods while asking customers to adopt a new tool.
The bacon department
Gabbert had a peculiar vocabulary for financial discipline. PitchBook called becoming cash flow positive bringing home the bacon. New clients prompted internal bacon emails that explained the customer, recognized employees and reminded colleagues what their work was for. Revenue had acquired its own office correspondence.
The economy extended to the kitchen. In 2016 he described free coffee and beer, alongside an absence of free lunches and La Croix. There is something admirably specific about a founder who can discuss a corporate acquisition and still account for the sparkling water.
He coupled that thrift with spending on people, the product and service. In 2017 he described hiring for potential and teaching recruits the industry through PitchBook University, a two-week introduction to private markets. A finance background was not his universal admission ticket.
Team life included sailing, whirly ball and baseball outings. His writing repeatedly returned to the pleasure of working with people he liked. The persistence could sound stern; the workplace he described was supposed to have room for a laugh.
His business plan was another object he kept. He said the original called for $3.8 million to build PitchBook and that the team had done it for $3.7 million. The satisfaction was revealing: even after the acquisition, he cared about the difference between the promised expenditure and the actual one.
The years after the sale
Morningstar’s ownership left Gabbert with a longer operating chapter. The acquisition was completed in 2016; his departure was announced in 2024. The years between those dates belong in the story because they show what happened after the satisfying headline.
By 2023, PitchBook’s segment revenue had reached $551.9 million, and its platform served more than 100,000 users globally. In 2022, Morningstar acquired Leveraged Commentary & Data for $650 million and integrated it into PitchBook. The private equity information project now sat inside a broader business covering capital markets and credit.
- 2007PitchBook begins
Gabbert founds the company.
- 2016$225 million
Company valuation in Morningstar’s acquisition.
- 2023$551.9 million
Annual PitchBook segment revenue.
Valuation and revenue measure different things. They are shown as milestones, not a growth comparison.
Gabbert also returned to the University of Washington as the Edward V. Fritzky Endowed Chair in Leadership for the 2017-2018 academic year. The appointment involved sharing experience through lectures, mentorship and coaching. He had already participated in the school’s entrepreneurial community as a business plan competition judge.
For students, his career offered a useful complication to the tidy startup sequence. Knowing the customer, attracting an investor, building a team and managing growth overlap. A founder may be teaching one lesson in public while still learning another at work.
“Raising money is hard. It should be hard.”
John Gabbert, 2017
A different side of the table
On May 8, 2024, PitchBook announced Gabbert’s plans to step down. Seventeen years is long enough for a company to accumulate a history beyond its founder’s original ambitions. His farewell paid attention to colleagues, friendships and families, as well as the business.
He thanked his wife, Susan, and their four children. He also expressed trust in the people who would continue running PitchBook. Letting colleagues lead was part of the departure he described, a final operating decision after years of making them.
In 2025, Gabbert and former PitchBook executive Jasper Larsen launched ODIN + Co. Gabbert is its co-founder and managing partner. The private equity firm focuses on helping middle market businesses grow revenue, with an emphasis on B2B, IT and information services in the United States and Europe.
The connection to his earlier work is easy to see. He spent years organizing information for people buying, financing and building businesses. Now his firm aims to work directly on the growth of portfolio companies. Customer questions, operating decisions and the careful use of resources remain familiar territory.
That old screenshot belongs to a company whose future was still undecided. The next chapter carries a different responsibility: helping decide what other businesses might become.