In 2014, the people building HyperVerge wanted your phone to understand your photographs. Type a few words, find the right picture. Their app, Picsaur, had a name assembled from pictures and dinosaurs, partly because the domain was available. Then Google Photos arrived in 2015. There are unpleasant competitors, and then there is a company that already has a place on your phone. The interesting question became what else a machine that could interpret pictures might be paid to do.
- A photo-search detour led to enterprise identity checks.
- Customers buy document, face, liveness, and workflow tools.
- The useful metric: real people getting through safely.
Today, that question leads to a bank account application, a selfie, and a small but consequential pause. HyperVerge sells businesses the software that reads identity documents, compares faces, checks liveness, and helps detect fraud. Customers include lenders, banks, brokerages, insurers, and telecom operators. The person holding the phone may never learn its name. They will certainly notice if verification keeps failing.
First, the purchase order never came.
The first disappointment actually preceded the photo app. In a founder account, Kedar Kulkarni describes industrial automation projects that the team could solve technically in six to twelve weeks. Turning those prototypes into substantial enterprise orders was another matter. Working technology had arrived before a dependable business.
The team regrouped around photo organization. The IIT Madras Incubation Cell provided ₹500,000, described at the time as about $8,000, toward building the app. A $1 million seed round followed in August 2015, from NEA, Milliways Ventures, and Naya Ventures. The announcement still described organizing photographs across devices.
Google Photos helped puncture that ambition. YourStory places HyperVerge’s enterprise pivot in late 2017. A conversation with Zoho founder Sridhar Vembu helped redirect the team toward a sustainable business and long-term impact. The useful thing they carried forward was their expertise in computer vision. The original application for it could go.
A selfie has several jobs.
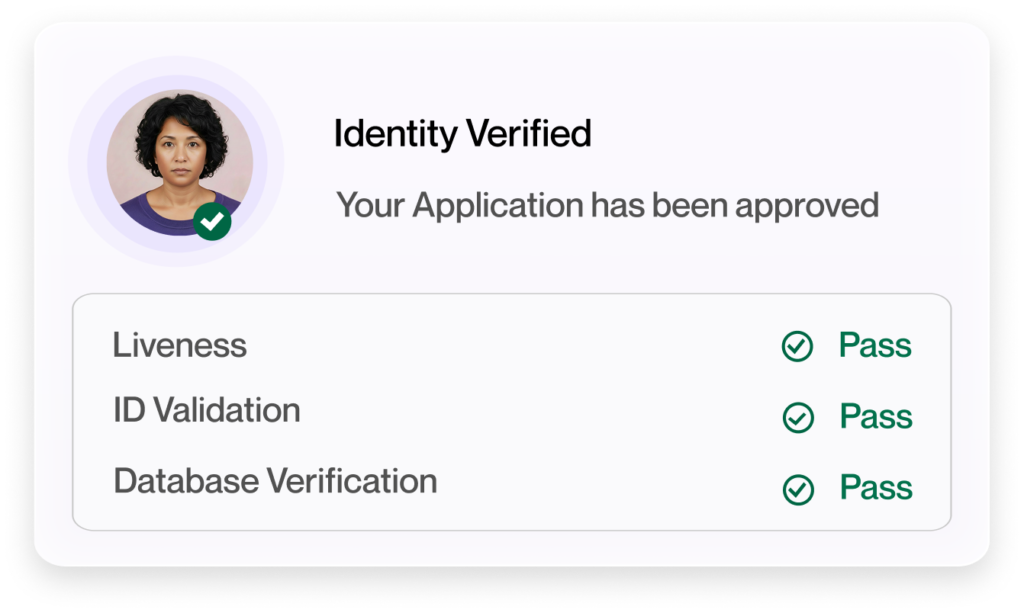
Consider what an identity check must establish. Reading a name off a document is one task. Deciding whether the document belongs to the applicant is another. Establishing that the camera is seeing a living person adds a third. Each answers a different question; passing one does not settle the others.
HyperVerge supplies these checks through APIs and software development kits. Its HyperVerge ONE platform connects checks into configurable onboarding journeys, with a no-code workflow builder and analytics for finding drop-offs. Business verification, sanctions and politically exposed person screening, video KYC, and document extraction extend the work beyond the selfie.
This puts HyperVerge in the identity verification market alongside providers such as Jumio and Onfido. Its practical pitch emphasizes combining the checks with workflow control, while supporting low-end phones and weak connections. That last detail matters: a beautifully designed verification process is useless to a customer whose connection cannot finish it.
The customer taught the product to grow.
At slice, the relationship began with document reading in 2017. Face matching and single-photo liveness came later, followed by central KYC. The adoption sequence is revealing. A customer can begin with one bottleneck, then add checks as the business and its requirements change.
Growth also changed how slice tested the system. Its published case study describes planning beyond optimistic volume forecasts and, in 2021, calling HyperVerge’s API at five to six times the expected onboarding rate. Teams checked latency, quality, and fraud prevention. A marketing campaign, after all, is a peculiar moment to discover that your entrance cannot handle a crowd.
Angel One describes a similar widening relationship: OCR first, then face match, selfie liveness, and bank account verification. Its expansion into smaller Indian cities made low bandwidth an explicit concern. Home Credit’s separate case study reports a 50% reduction in OCR error rates. These are customer-specific accounts published by the vendor, rather than promises about every deployment.
“When we’re doing a branding blitz, we test for 5X volume.”Mahima Garg · slice case study
The camera is now part of the argument.
In October 2026, BixeLab issued two relevant confirmation letters. One covered presentation attack detection, where an attacker presents a fake object to a camera. The other covered injection attacks, where manipulated imagery enters the verification process through a compromised capture path. A convincing face and a trustworthy camera feed are separate problems.
The presentation evaluation recorded no classification errors across 150 attack transactions, but two errors across 50 genuine transactions. Every genuine participant completed at least one successful attempt. That distinction matters to anybody who has ever been told to take the same selfie again.
The injection evaluation rejected all 630 tested injection transactions. BixeLab says this evaluation aligned with CEN/TS 18099 and was not an NVLAP-accredited outcome. Both letters concern particular software versions and test conditions. Buyers can copy the discipline here: examine the capture path, measure genuine-user rejection, and test on the devices their customers actually own.
A business built around the pause.
HyperVerge’s pricing follows volume tiers: higher volumes reduce the unit price. Its public plans offer a sandbox trial and customized enterprise arrangements. Procurement therefore involves more than comparing a face-match score. Teams need to price the whole journey, including retries, database checks, integration, and manual review.
The scope is widening again. At Global Fintech Fest 2026, the company announced three underwriting agents for financial analysis, video-based personal discussions, and background due diligence. These organize evidence for lenders; the company says the underwriter still decides. Identity is the opening question in lending, with repayment risk waiting behind it.
There is a second kind of access in the company’s story. HyperVerge Academy, established in 2020, provides free technology training and mentorship for people from under-resourced backgrounds. It gives the founders’ interest in opportunity a concrete outlet alongside the commercial business.
The lesson for a product team is fairly practical. Start with a costly point of friction, make the improvement measurable, and expand only as customers need more. This approach depends on reliable documents, suitable coverage, and a working review process. Weak records, unsupported identities, or an unexamined rejection threshold can still lock legitimate people out. Letting the right people in requires paying attention to who keeps getting left at the door.
Keep looking.
Explore the website, plans, customer stories, and company blog. Follow on LinkedIn, X, Instagram, Facebook, or GitHub.
Watch the Home Credit customer video and CTO Vignesh Krishnakumar’s interview. Read the Home Credit partnership feature, YourStory profile, and laboratory letters.