Consider an $18,000 roof. The contractor has priced the materials, the crew and the trouble of getting everything onto the house. The homeowner has heard a different number: the amount missing from the bank account. The roof may be perfectly reasonable. The check is another matter. Hearth has built its business in the pause between those two judgments.
- Hearth connects homeowners with lenders and sells contractors the software around the sale.
- Contractors pay a subscription, with no dealer fee on each financed loan.
- Harper, its AI assistant, handles calls, appointments and follow-up when the owner is busy doing the work.
The practical move is to show a monthly payment alongside the total price. A customer can explore borrowing without the contractor becoming a bank. Hearth supplies the link and the sales tools; third-party lenders decide whether to lend. The roof still costs $18,000. Interest can make the homeowner’s total bill larger. What changes is the timing of the expense.
01 / THE PRICE OF YESA fee hiding inside the winning bid
Some financing programs charge the contractor a percentage of the funded job. Hearth instead charges for membership. Its public financing guide advertises annual subscriptions of $1,499 to $4,999; other pages give broader typical spending ranges. The current plan page asks buyers to book a demo for a quote. There is no universal price to pencil into every contractor’s budget.
The distinction matters most when financing becomes routine. Imagine a program charging a 6% dealer fee on that $18,000 roof. The fee is $1,080. Repeat the exercise five times and it becomes $5,400. This is illustrative arithmetic, not a claim about a particular rival’s plan. A fixed subscription makes repeated financing easier to budget, provided the owner actually uses it.
For an owner who finances a couple of jobs a year, the calculation can go the other way. Wisetack publishes a 3.9% fee for interest-bearing options, with higher fees for certain promotional plans. Acorn Finance charges contractors no setup, platform or dealer fees and receives payment from lenders. Hearth therefore has to justify buying a wider toolkit. Avoiding a dealer fee alone cannot settle the comparison.
02 / A LINK, THEN A LONGER LISTThe sale grew a back office
Hearth began in 2016. Its founders include Anthony Ghosn, Joe Lonsdale and technical co-founder Nikhil Pai. The early proposition was useful precisely because it was narrow: make consumer financing available to smaller home improvement businesses. These are roofers, HVAC installers, plumbers and remodelers, often selling expensive work from a truck rather than a showroom.
By May 2021, the company was announcing a $23 million Series B led by Human Capital. Investors included 8VC, SuRo Capital and The Chainsmokers, an unexpected musical accompaniment to digital invoicing. The announcement described expansion into payments, insurance and workflow tools. Financing had provided a reason to enter the contractor’s day; the surrounding chores provided reasons to stay.
“We know our customers want to spend less time managing their business and more time focused on their craft.”Anna Fabian · Hearth product leader · 2021
Today, quotes connect with financing, contracts collect electronic signatures, and invoices lead into payment collection. Customer records and scheduling sit alongside them. The expertise is in joining these steps for residential trades. A general software tool might store a contact perfectly well. Hearth wants that contact to become a quoted job, a funded customer and a collected payment.
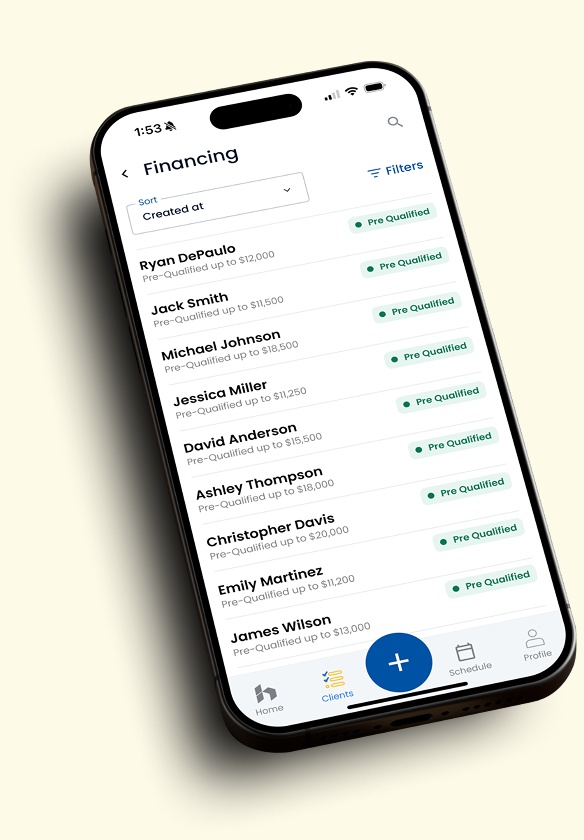
A tiny green label. A much larger conversation.
Prequalified ≠ fundedThe mechanics are straightforward. Send the customer a link from a quote, contract or invoice. The homeowner checks options with a soft credit pull, then applies with a chosen lender. Final approval remains the lender’s decision and may require a hard inquiry. For personal-loan options, money goes to the homeowner, who pays the contractor. Access to an offer is an intermediate step.
Share the link
Lender decides
Customer pays
03 / THE PHONE THAT KEEPS RINGINGApproval does not answer a missed call
Hearth’s next product bet concerns attention. Harper answers calls around the clock, captures job details, books appointments and follows up on financing applications. The current pricing page also describes follow-up texts and drafts the contractor approves. That is a sensible place for automation: chasing the next administrative step while a human is occupied with the physical one.
The first weak point is easy to recognize. A prospect calls while the owner is on a roof. Another starts borrowing and never finishes. An estimate waits for a reply. None requires a dramatic technological failure. Each requires an interruption. Harper’s proposition is that reliable attention can be sold as part of the same system that supplies the financing.
This does not establish that automated follow-up produces an extra job for every contractor. It explains the product’s direction. Hearth is moving upstream toward the first inquiry and downstream toward the completed application. Its competitors now include financing platforms and the existing office routines an owner may be reluctant to replace.
04 / TAKE THE PENCIL OUTThe number that deserves an asterisk
One useful qualification appears in Hearth’s July 2026 ROI guide. Its analysis of 249,000 quotes found larger won jobs when financing was offered, but calls the result descriptive. Contractors selectively attached financing to bigger, harder deals. The company says that pattern cannot establish a causal improvement in close rate. The finding changed what it was willing to claim.
A reader can copy that restraint. Count financed jobs, subscription spending, retained margin and completed applications. Compare like-sized bids rather than declaring victory because financed projects are expensive. The useful question is whether the process earns its place in this particular business.
The conditions matter. Sparse financing volume can make a subscription hard to justify. A borrower may dislike the rate or fail approval. In a 2018 explanation, Hearth acknowledged that protecting contractor margin can leave customers facing higher rates than subsidized financing. Software cannot resolve those objections by tidying the invoice. Its promise is narrower, and more interesting: make the next decision easier to complete.