The logo was on the shirt. The payment app was on the phone. Guavapay had found a way to appear in two places people check obsessively: their football club and their money. In July 2024, Millwall announced MyGuava as its new front-of-shirt partner. The agreement promised club-designed payment cards as well as a name across the players’ chests. Everyday spending would become another little expression of football loyalty.
By December 2025, Millwall had terminated the partnership and announced legal proceedings. A month later, on 21 January 2026, Guavapay Limited entered compulsory liquidation. A company selling the convenience of moving money had reached a point at which the central question was how money might be returned.
That is where a profile of Guavapay has to begin today. Its historical product range remains worth examining: consumer accounts, business accounts, cards, checkout technology and international transfers, assembled into an unusually broad proposition. But descriptions of what MyGuava offered belong to the period before the UK restrictions. The legal entity in liquidation is Guavapay Limited; the status of every overseas business cannot be inferred from that UK event.
A wallet, a till and the plumbing between them
Incorporated in February 2017 and founded by Orkhan Nasibov, Guavapay built payment technology before making its consumer brand more visible. In an April 2025 interview with FinTech Magazine, then CEO Guy Noble described the company’s early allocation of effort: “The first five years were really focused on building the technology. That was a significant investment.”
The resulting business operated at several levels. MyGuava put transfers, currency accounts and cards into a consumer app. MyGuava Business brought accounts and payment acceptance to companies. Beneath both sat the less photogenic business of processing payments, issuing cards and connecting services. Guavapay marketed that infrastructure to financial institutions and commercial partners as well as using it for its own products.
The audiences had different jobs to do. Someone sending money to relatives wanted a workable international route. An online seller wanted a customer’s card payment to go through. A business managing several currencies wanted fewer separate tools. Guavapay’s bet was that one technology business could serve these related needs, even when the people using it saw quite different screens.
Former acting CEO Laura McCracken later described the ambition as combining Revolut and Square. It is a useful description of the company’s intended place in the market: the wallet’s daily familiarity beside the merchant’s payment relationship. It also explains the workload. An attractive consumer interface was only one part of the proposed business.
The small fixes that made the pitch work
The more persuasive parts of Guavapay’s product story are small enough to picture. In August 2023, its Yapily partnership addressed topping up GBP and EUR accounts from supported banks. Open-banking integration allowed a customer to initiate the transfer from a connected bank instead of laboriously entering account details. The intended benefit was fewer steps between having money and using the app.
Snowdrop Solutions tackled another mundane irritation in May 2024: the mysterious transaction description. Its MRS API enriched purchases with recognisable merchant names and logos. A customer could more easily connect an entry in the app with something actually bought. Guavapay and Snowdrop argued that clearer descriptions would also reduce the need to ask support about unfamiliar purchases.
International reach required different partners. A July 2024 agreement connected MyGuava to LianLian Global Payout Service for transfers to China. At the time, the announcement described accounts in 20 currencies, alongside virtual and physical debit cards, bill splitting and eligible cashback. The China route was a specific addition to that bundle, built through a partner’s payout network.
In Canada, a June 2025 Paysafe partnership approached the problem from the opposite direction: getting physical cash into a digital wallet. A user generated a PaysafeCash barcode in the app, then took it to a participating retailer to pay cash. It was a practical concession to how people already handled money. A phone could organise the transaction without requiring every customer to start with a card.
These integrations reveal Guavapay’s expertise more clearly than a list of fintech keywords. It combined interfaces, payment connections and transaction information. The company built its own technology while buying access to useful capabilities elsewhere. For the customer, the hoped-for result was simply less work.
The price on the checkout
For merchants, price made the proposition concrete. A historical MyGuava e-commerce page advertised 0.7% for UK debit cards and 0.9% for credit-card transactions. It also offered a hosted payment page, API access and integrations with shopping platforms. Those were acquisition arguments a small retailer could understand: fit the existing shop, accept familiar cards and keep the payment charge legible.
On £100, those percentages equal 70p and 90p respectively. Illustrative arithmetic before any other applicable charges; historical advertised rates, not a current offer.
The business model extended beyond that headline percentage. Legacy account terms described agreed business fee tables, monthly account fees and transaction charges. Adobe’s marketplace listing for the MyGuava extension likewise said acquiring fees applied. A payment integration could therefore bring in a merchant whose continuing transactions generated fee income. Consumer convenience and business monetisation belonged in the same commercial picture.
The limits matter. A published rate is not a complete account of what it cost to serve a customer, maintain the technology or run the company. Nor does a free transfer claim settle the price of every currency conversion or payment route. Guavapay’s own terms put bespoke business charges into the onboarding agreement. The attractive number was the start of a purchasing decision.
From football shirts to a stopped business
Guavapay’s ambitions were visible inside the organisation too. Its January 2025 business update reported 71% revenue growth during 2024. Enterprise Times described more than 500 employees globally, a new Baku IT Lab and a London office that had tripled in size. Those were contemporary expansion claims, not a measure of the business that remains today.
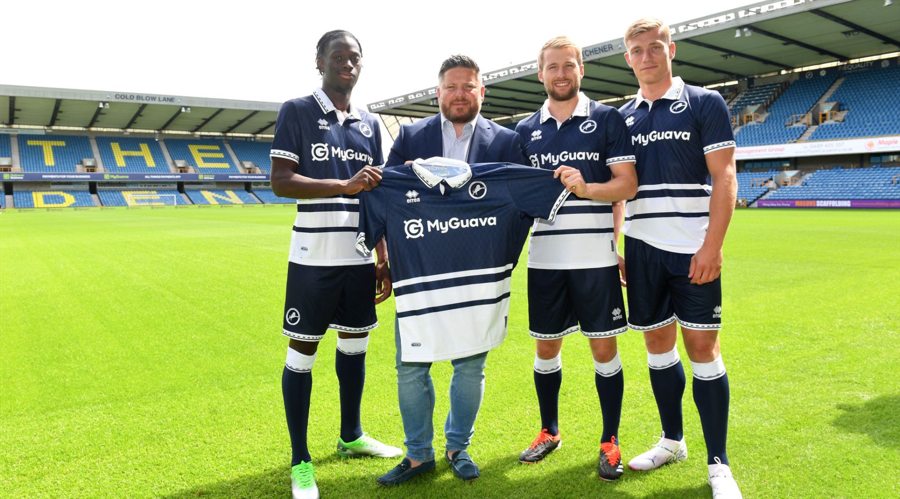
The Millwall deal was more than a billboard purchase. The original announcement paired shirt visibility with planned payment cards and spending rewards. It offered an existing community a reason to try a financial product. That was a distribution idea as much as a sponsorship idea: meet people through a relationship they already cared about.
The public story changed in September 2025. Guavapay agreed to restrictions with the FCA on 17 September. Its announcements told customers that new funds and additional cards were no longer available. At that point the company said existing balances could still be transferred or withdrawn. Those assurances describe the announcement at the time, not a present-day withdrawal promise.
By December, Millwall said the commercial relationship was over. City AM also reported a Mastercard winding-up petition over unpaid sums. Companies House now records the winding up, while the FCA identifies Interpath’s Kristina Kicks and Michael Leeds as the appointed liquidators. The relationship with a payment network had become part of an insolvency story.
The problem arrived before the pause
Guavapay’s September explanation reached back to the early launch of its e-wallet in 2024. The company said its accounts had received a high volume of fraudulent funds. It said additional safeguards had reduced that activity. Separately, it acknowledged that growth had taken the business beyond regulatory thresholds. These are the company’s stated explanations, reported by FinTech Futures, rather than a finding that every customer or transaction was suspect.
McCracken’s later public retrospective adds a view from inside the response. She described introducing rapid-transaction checks and freezing suspicious funds. She said she took the acting CEO role believing the problems could be fixed, then discovered that a regulatory payment threshold had been exceeded. Her account makes the sequence more specific: fraud concerns, an attempted response, then another constraint on the business.
It also changes the lesson readers might take from the marketing. The company could add a useful integration while still struggling with the conditions of operating the wider service. Improving one fraud measure would not, by itself, resolve a separate regulatory limit. A product team’s progress and a firm’s ability to continue trading are different things to measure.
A payment app has to work twice: on the customer’s screen, and inside the company running it.
The operational lesson
The everyday legal distinction had been there in the account terms. Guavapay was not a bank, and its e-money accounts did not earn interest or carry bank-deposit protection. The current FCA liquidation notice says payment services are outside FSCS coverage. Liquidators assess safeguarded money and possible returns, with costs potentially deducted. For affected customers, the official liquidation contact route now matters more than the old sign-up page.
What survives as a useful idea
There are still product decisions worth studying. Use a partner to remove a specific obstacle: a bank top-up, an unfamiliar merchant name, a missing payout route. Build around a task a customer can recognise. Make an integration fit the software a merchant already uses. Those ideas are small, observable and easier to evaluate than a promise to transform finance.
The commercial conditions are equally concrete. These features need operating payment relationships, effective controls and permission for the business being conducted. They also need a cost structure that survives beyond the launch campaign. Put several financial functions in one service and the customer gains convenience, but becomes more dependent on that service continuing to work.
Guavapay’s UK history leaves both sides visible. There was an intelligible product proposition, with real integrations and a route onto the football pitch. There was also a company that acknowledged fraud and threshold problems before entering liquidation. The task for anyone copying its useful ideas is to make the less visible work as specific as the product pitch.
Follow the paper trail
Company channels and historical product material
Watch and listen