Consider the small indignity of being good enough to win an overseas customer and still struggling to collect the invoice. The work travels by internet. The money takes a more bureaucratic route. Somewhere between a client’s accounts department and a supplier’s next bill, international commerce becomes a pile of local problems.
Payoneer has spent two decades working on that pile. Founded in 2005 by Yuval Tal and Ben Yaniv Chechik, it helps businesses receive overseas earnings and turn them into usable funds. Its proposition is wonderfully unromantic: fewer financial errands between doing the work and getting on with the next job.
- The job: collect international earnings, manage currencies and pay business expenses.
- The customer: sellers, service firms and professionals whose business crosses borders.
- The catch: features and total fees depend on the payment’s actual route.
A local door into a global market
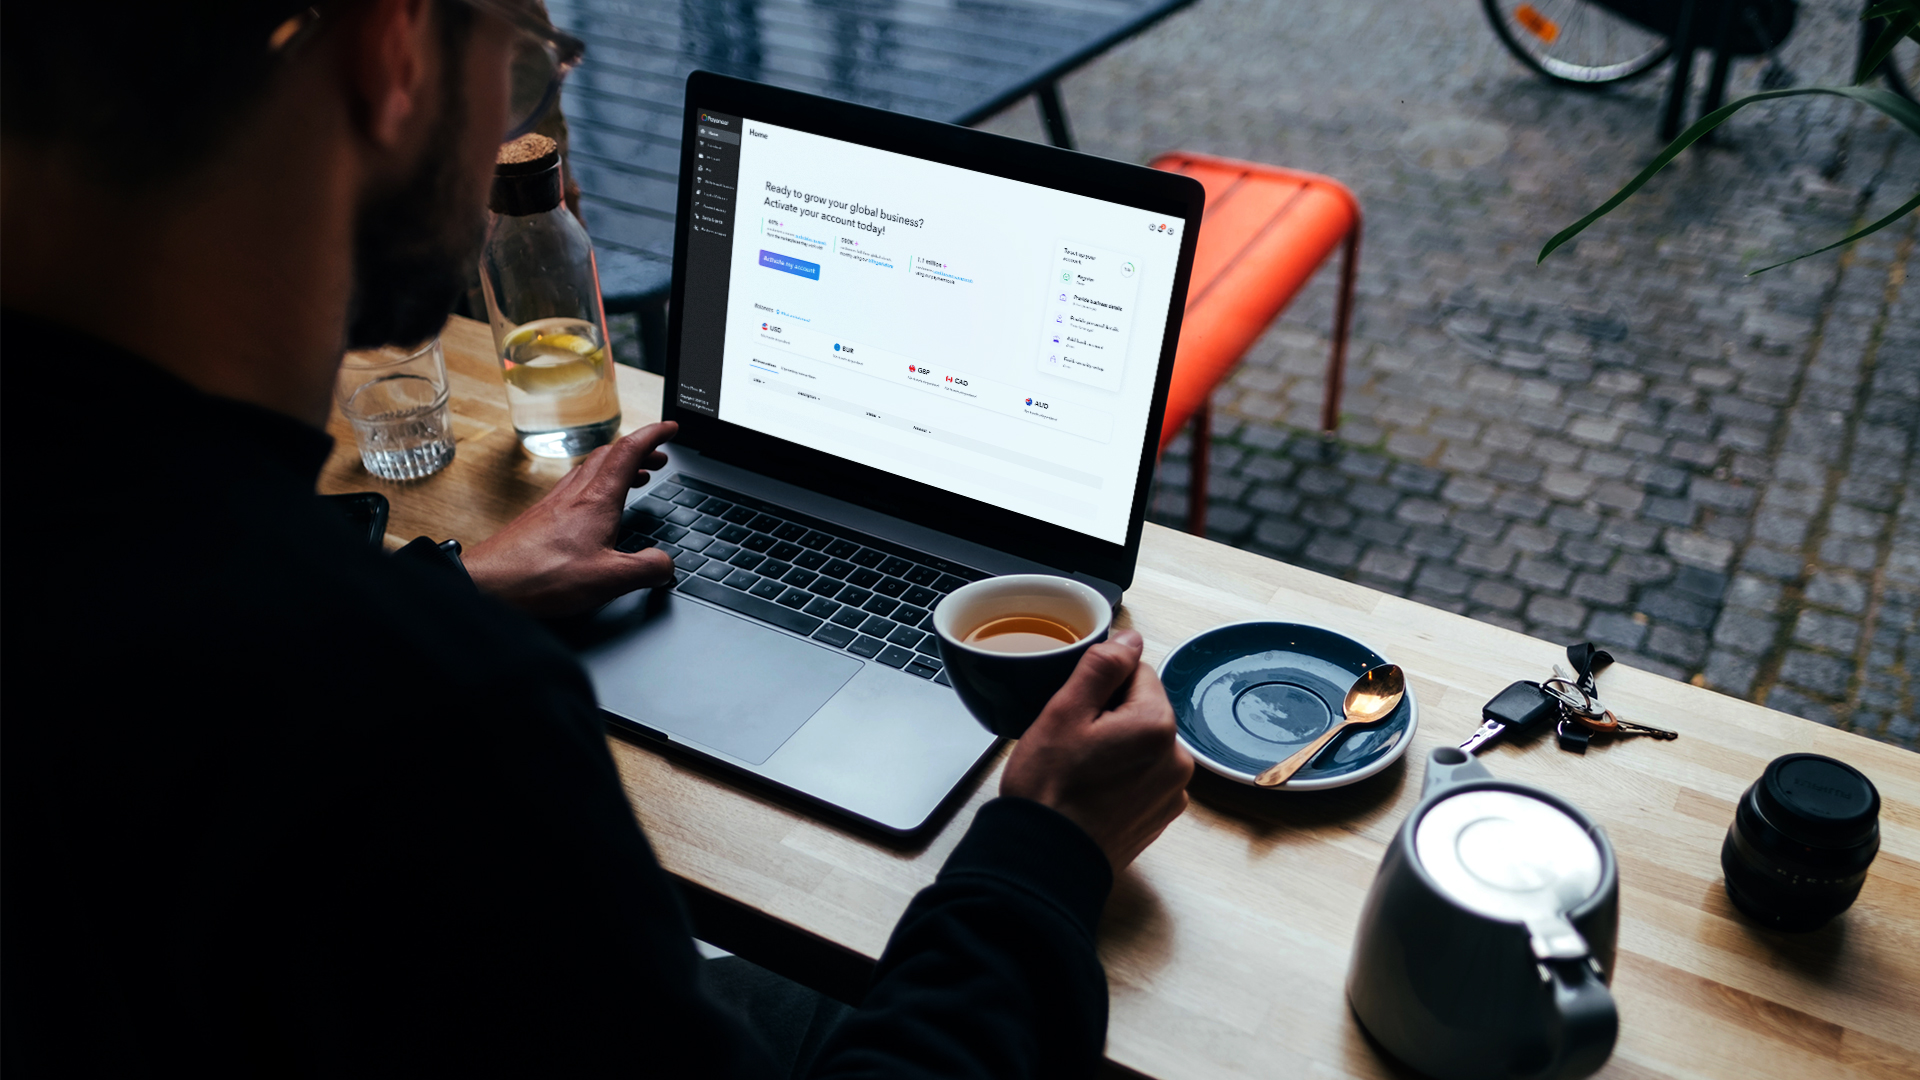
Take a hypothetical exporter selling to an American business. Asking that customer to arrange an international transfer adds another task to the purchase. Where eligible, Payoneer supplies receiving account details that let the customer pay through a familiar local route. The exporter can then use supported balances, conversion and withdrawal options.
The same problem appears inside marketplaces, multiplied by thousands of sellers. A platform needs to distribute earnings across countries with different banking arrangements and regulatory requirements. Payoneer’s integrations put its infrastructure into that existing relationship. The seller already has a reason to show up: there is money waiting.
Etsy makes the point concrete. In September 2026, the companies renewed their relationship through 2029, covering 16 markets. Their partnership began in 2023 and has supported tens of thousands of sellers. Payoneer also extended its 15-year relationship with Upwork in 2026. These connections are distribution channels as well as payment pipes.
That is its distinctive position among overlapping competitors. Wise Business and Airwallex offer alternatives for international accounts and currency movement. PayPal competes for payment collection; Stripe and Adyen are prominent in merchant acceptance. Payoneer’s particular appeal combines marketplace earnings with the financial chores that follow. The best fit depends on which chores a business actually has.
The fee has a route attached
Convenience has a price, and “What does Payoneer cost?” needs a second question: doing what? Its public schedule lists different charges for receiving a client payment, moving between currency balances, withdrawing money and using a card. Geography and account terms matter, too.
For a $1,000 client payment, a listed 1% US ACH fee means $10. A card-funded payment at the published maximum of 3.99% plus $0.49 means $40.39. Those are collection illustrations, before any separate conversion or withdrawal charges. Comparing only the first fee is rather like pricing a flight without checking which airport it lands at.
The company earns transaction and service fees, plus interest on customer funds. In 2025, $821.2 million of revenue excluded interest; interest contributed another $231.6 million. That distinction matters when assessing a payments business: revenue can change because customers transact differently, or because interest rates move.
When the card stopped working
The less cheerful lesson arrived in June 2020. After trouble at Wirecard, British regulatory restrictions on Wirecard Card Solutions interrupted affected Payoneer cardholders’ access to funds. The customer-facing brand was Payoneer. A critical dependency sat elsewhere. To someone trying to withdraw their earnings, that organizational distinction offered little comfort.
Payoneer subsequently moved affected card issuance to Payoneer Europe, with the transfer scheduled for September 2, 2020. The episode exposed a basic property of financial infrastructure: access depends on the institutions underneath the interface. A clean dashboard cannot remove that dependence.
The customer buys access to money. The machinery underneath still matters.
Editorial observation
For a business choosing any provider, the practical question is therefore broader than speed. Which entity serves the account? Which routes are supported? What happens when a partner is unavailable? Keep another workable payment route available where possible. A dependency deserves attention before an interruption makes it visible.
The customer has more than one chore
Once a company gets paid internationally, it may also need to pay internationally. Suppliers want settlement. Contractors want their earnings. Inventory needs funding before the next marketplace payout. Payoneer offers business payments, eligible cards and Capital Advance, which collects repayment from a portion of future marketplace receipts.
In August 2024, Payoneer acquired workforce and payroll company Skuad for $61 million in cash initially, with up to $20 million in additional contingent cash and equity payments. The move brought hiring and workforce administration closer to the payment account. It expanded the list of recurring problems Payoneer could handle.
Its operating footprint is expanding too: a Gurugram innovation hub opened in July 2026, bringing together engineering and business teams. In October, Payoneer announced its Canadian payment-service-provider registration. Local execution remains part of a business sold on global reach.
The next owner wants the whole journey
In June 2026, Nuvei agreed to acquire Payoneer for $7.40 a share in cash, approximately $2.75 billion in equity value. August’s update described an expected mid-2027 closing, subject to approvals and other conditions. Treat it as a proposed transaction. Its commercial logic joins merchant payment acceptance with Payoneer’s cross-border accounts and payouts.
The scale is substantial: Payoneer reported $87.5 billion in payment volume for 2025 and nearly two million active customers. But a small business should judge the platform at its own scale. Map one real payment from customer to usable cash. Check eligibility, deductions and timing. The useful lesson is simple: build around the next obstacle your customer repeatedly encounters. For Payoneer, that obstacle starts just after someone says yes.
Follow the money
Website · Pricing · Blog & guides · Company news
LinkedIn · X · Instagram · Facebook
Watch: Get paid with Payoneer
Watch: John Caplan’s Nasdaq interview