In 2003, putting a whole song on a mobile phone could take ten minutes. The sound was pinched, the network temperamental and the previous song might need to be deleted to make room. Greg Wilfahrt still saw a business. A former MP3.com executive and co-founder of the mobile company SMS.ac, he offered a compact rule: “If you give consumers a viable alternative, they'll pay for it.” Give them a good product, he added, and they would pay for that too.
The device in question was barely ready. The instinct was. Wilfahrt's career has unfolded in the long interval between the phone as novelty and the phone as financial instrument. Along the way, he has sold the possibilities of downloaded music, watched strangers organize themselves into text-message clubs, helped operate a mobile community that approached 60 million users, and moved into the less photogenic machinery of business payments. The connecting tissue is not the handset. It is confidence.
Today he is Chief Marketing Officer at AP Technology, the Carlsbad company that builds payment software for banks, government offices and businesses. Earlier public materials give him the grander title of Chief Mobility and Marketing Officer. Both are accurate descriptions of the territory he has occupied: the narrow, busy border where a technology stops being impressive and has to become useful.
The journalist enters the machine
Wilfahrt studied journalism at San Diego State University from 1980 to 1983. That fact has more explanatory power than a tidy corporate biography usually allows. His public career is full of the journalist's favorite device: turn a complicated system into a question that ordinary people can answer. Will listeners pay for music on a phone? Does permanent connectivity have a downside? Which payment method fits this transaction? What does a customer deserve before tapping “buy”?
At MP3.com, he worked inside the first unruly commercial era of digital music. By 2003 he was helping lead SMS.ac, a San Diego mobile community built when “mobile social network” still required explanation. It connected text and multimedia messaging across carriers and countries. The community grew with the strange vitality of the early consumer internet: quickly, globally and in directions its builders could not have scripted.
One example was the Alibi and Excuse Club. Members used group texts to invent cover stories for one another. Some were harmless jokes; others had the moral elegance of a banana peel. Wilfahrt told reporters he found the improvisation “ridiculously funny,” while acknowledging the integrity problem. The anecdote feels prehistoric now only because today's group chats produce equivalent foolishness before breakfast.
“Is there ever a drawback to having anytime, anyplace connectivity? That's probably up for debate.”Greg Wilfahrt, during the early text-messaging boom
The laugh line carried a serious question. SMS.ac also drew criticism over invitations, recurring charges and whether customers understood what they had joined. Wilfahrt defended the service publicly and pointed to refunds for unhappy users. In 2005, the company published a Global Mobile Consumers Bill of Rights. Its promises were strikingly plain: clear pricing, meaningful opt-in and opt-out, privacy, prompt support, refunds and no hidden surprises.
That document did not settle every argument around SMS.ac. It did establish the vocabulary Wilfahrt would keep using: clarity, accountability, satisfaction and confidence. Technology might change faster than public expectations, but trust always sends an invoice.
One career, three versions of the phone
A sequel, with money attached
By 2008, Wilfahrt was chief strategy officer at StreamVerse, another wireless communications company. In 2014 he joined AP Technology. The move from social messaging to payment issuance sounds like a hard turn until one remembers that SMS.ac had already tied digital services to carrier billing in more than 180 countries. A message could be a product; a phone bill could be a checkout. Mobility and money had been neighbors all along.
At AP Technology, those abstractions became operational. The company's systems handle checks, ACH, cards, positive pay, digital signatures and remote payment workflows. Its customers include institutions for whom a failed transaction is not a momentary inconvenience but an audit issue, a delayed closing or an invitation to fraud. The cheerful language of frictionless commerce meets the fussy dignity of reconciliation.
The shift also changed the unit of persuasion. A consumer app can win a trial with delight. A bank system has to survive procurement, integration, compliance and years of ordinary use. Wilfahrt's subject became the whole workflow: who approves a payment, where a check can be printed, how an accounting platform connects, and what evidence remains afterward. The small details are the product once money leaves the slide deck.
In 2015, Wilfahrt and AP Technology founder Richard Love co-authored a Mobile Payments Bill of Rights. Like its 2005 predecessor, it treated adoption as a bargain with the customer. Speed mattered. So did security, ease of use and ubiquity. “Consumer confidence and consistent, positive user experiences,” Wilfahrt said at its unveiling, would accelerate mobile payment adoption. In 2016, he took the document to members of Congress on Capitol Hill as a proposed set of best practices.
Bills of rights can sound inflated when attached to software. This one exposed something modest and true. People do not experience a payment rail as architecture. They experience whether the amount is right, whether the recipient got it, whether their information is safe and whether someone answers when it goes sideways.
The serious business of putting on a show
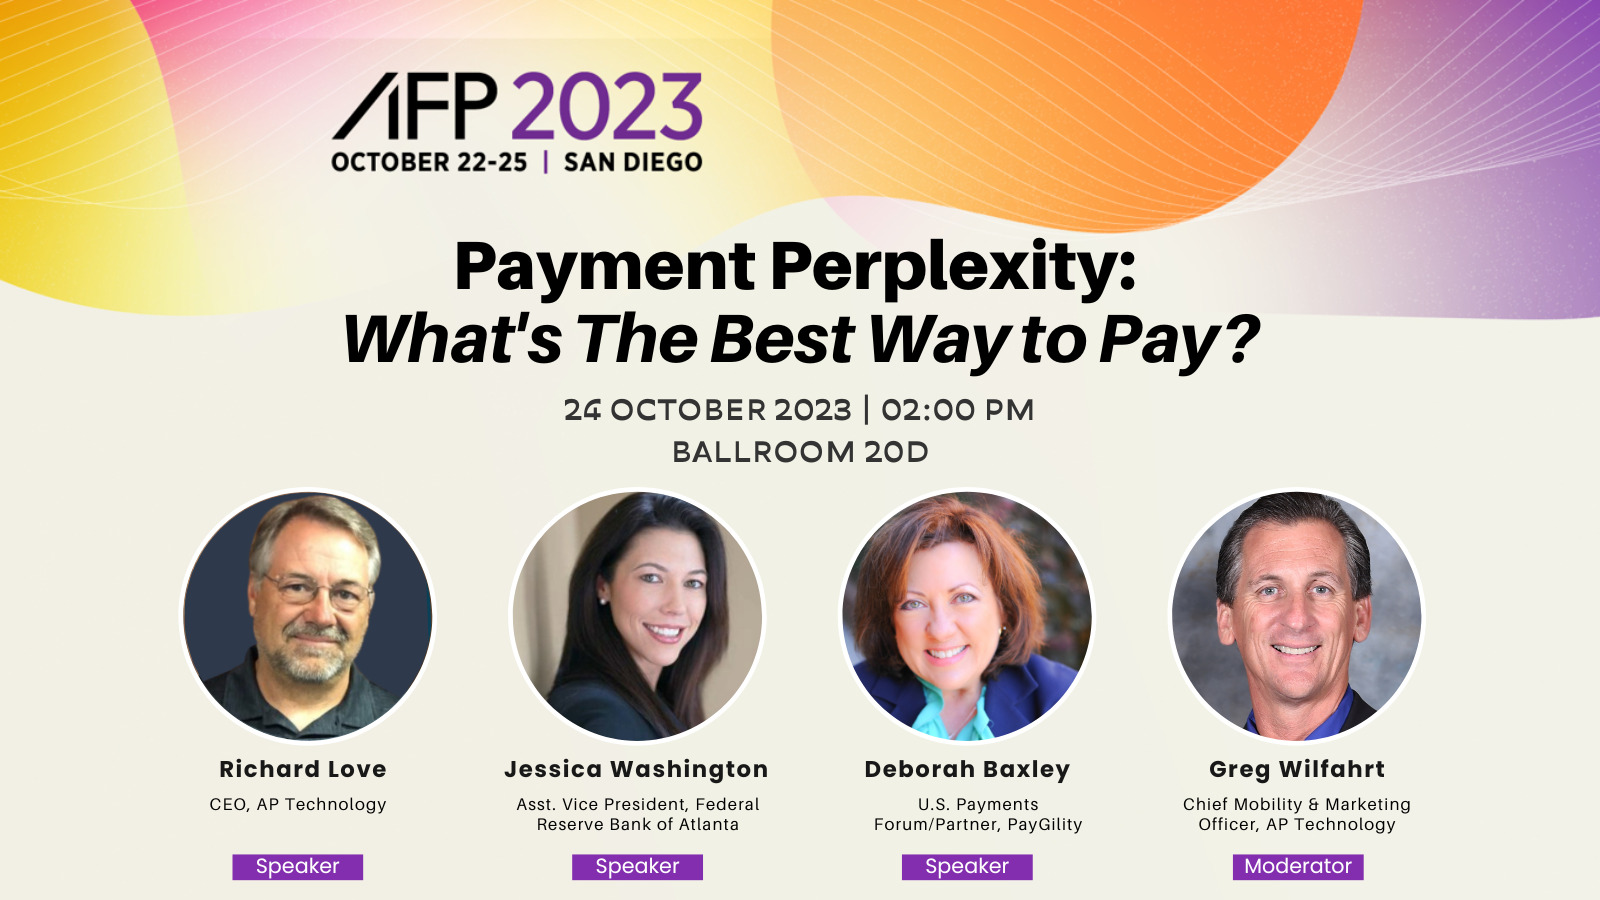
Wilfahrt's preferred conference format has rarely been a gray procession of slides. He has moderated panels dressed as retail fairy tales, Wild West expeditions and, at the 2023 AFP conference in San Diego, a game of “Payment Perplexity” modeled on Jeopardy. His guests have included a country singer, an actor-producer, analysts, payments executives and Jessica Washington of the Federal Reserve.
It is an entertainer's solution to an infrastructure problem. Payment methods are hard to discuss because their differences are conditional. Faster can also mean harder to reverse. Familiar can also mean manual. A card, an ACH transfer, an instant payment and an official check each solve a different bundle of anxieties. Put the questions on a game board and the tradeoffs become visible.
This is why Wilfahrt can write about modern payments while defending the continued place of paper checks. The contradiction disappears at the level of the job. Businesses are not auditioning technologies for a futurist's approval. They are paying vendors, closing property transactions, issuing settlements and protecting multiple accounts. A rail survives when it remains good at something that matters.
AP Technology says its customers now process more than $140 billion in payments annually. The figure belongs to the company rather than Wilfahrt, but it gives scale to his communications task. Marketing here is not decoration around the product. It is translation between engineers, banks, finance teams and people who mostly want the money to arrive without becoming a meeting.
Progress without the bonfire
Wilfahrt's recent writing has focused on replacing obsolete payment systems with minimal disruption, extending official-check printing beyond bank branches, automating issuance and balancing faster payments with security. The position is evolutionary. Modernization should improve a workflow without demanding that an organization set fire to every process that already works.
That may be the natural conclusion of a career long enough to watch several inevitable futures arrive late, partially, or in company with the technologies they were meant to bury. Full songs did reach phones, though streaming won the habit. Mobile communities became ordinary, though not in the precise shape of SMS.ac. Phones became wallets, while checks kept turning up for work.
“Mobile payments remains a story that is still being written.”Greg Wilfahrt, 2015
The line is a decade old and has aged rather well. Payment stories resist endings because trust has to be renegotiated with every new method. The journalist in Wilfahrt keeps asking who benefits, what the customer understands and where the surprise is hiding. The operator knows the answer must function across systems, borders and an ordinary Tuesday afternoon.
There is a temptation in technology to confuse motion with progress. Wilfahrt's public record offers the more demanding test. A payment can be fast and still frightening. It can be old and still useful. It can be clever and still fail if nobody explains it. The best rail is the one that fits the journey - and behaves all the way there.
Continue the conversation