Ask a startup founder what stands between him and building the largest company in the world, and there is usually a speech waiting. Market size. Capital. Hiring. A slide with an arrow heading pleasantly upwards. When Ethan Dobson faced that question in 2017, he declined the premise. “It’s never been my motivation to have the largest company in the world,” he said. The answer had the useful effect of making the question sound rather expensive.
Dobson was running ipaymy, a Singapore payments business that had just secured a US$1 million seed round. There were perfectly conventional reasons to talk about scale. Instead, he talked about the people involved in building a company and the difference it might make to their lives. A century was the interviewer’s proposed horizon for his legacy. Dobson brought the discussion back to individual people.
That exchange offers a good place to begin his story. The business he helped build deals in an unglamorous but consequential commodity: the time between a bill arriving and the money becoming available to pay it. Rent has a due date. So does payroll. A customer’s promise to settle an invoice is considerably less useful at the bank. Anyone who has chased a payment will recognise the imbalance.
 ▶ Watch the conversation
The customer had a second use in mind
The first version of ipaymy went live in April 2016 with a consumer proposition. People were spending substantial sums on expenses such as rent and tuition, yet those payments often could not go on a credit card. The company offered a way to make them through its platform and earn card rewards. A large, dull expense could acquire a small consolation prize.
Then customers made a suggestion. They liked the service for their personal payments; could they use it for their businesses too? Dobson described that feedback as the route into serving small and medium-sized enterprises. The same obstacle existed in a different setting: a business had a card, but the person or organisation it needed to pay wanted a bank transfer.
The distinction mattered. For a consumer, the attraction might be points. For a business owner, the attraction could be keeping cash available while an expense was paid. Rewards remained part of the proposition, but the purpose grew more practical. The customer had effectively supplied a second job description for the product. Dobson and the team followed it.
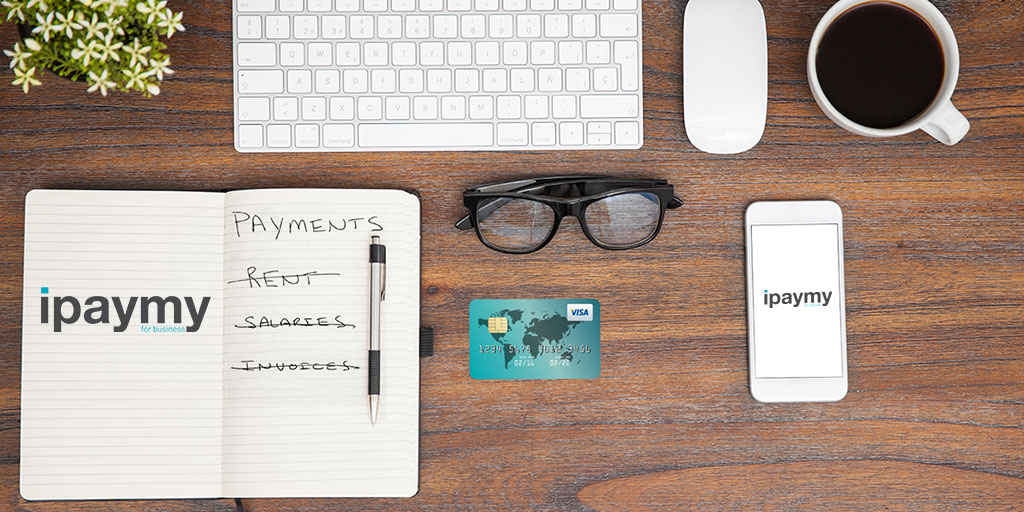
A credit card on one side, a bank account on the other
The mechanism is easier to grasp than the financial vocabulary around it. A customer funds an eligible payment with a credit card through ipaymy. The recipient receives money in a bank account. The recipient does not have to start accepting cards merely because the payer would prefer to use one. Two parties can keep different payment preferences and still complete the transaction.
That helps explain why the company’s early business pitch focused on rent, salaries, invoices and corporate taxes. These are substantial obligations with recurring deadlines. In January 2018, Dobson emphasised that ipaymy was a technology payments platform rather than a lender taking the credit risk itself. Existing card relationships supplied the credit; the platform made that payment method usable in more places.
There is a commercial bargain here, and it deserves plain language. A platform fee is part of using the service. Any benefit from holding cash longer depends on the card’s terms and the customer’s repayment behaviour. Moving a payment onto a card changes its route and timing; the underlying bill remains real. The practical question is whether that change is useful enough for a particular expense.
Seen that way, ipaymy’s business is about connecting two familiar pieces of financial infrastructure. The card and the bank account already exist. Dobson’s opportunity lay in the awkward space between them. A landlord need not share a tenant’s enthusiasm for rewards programmes to appreciate money arriving in the usual place.
credit card
bank account
The quiet work behind a simple payment
Dobson’s early description of building the platform was refreshingly undramatic. The first working version took roughly six months. Reliability and security were central considerations because the software handled financial transactions. A payment product can be elegant on a screen and still fail its customer if the money does not arrive when expected. The interesting work often happens where the customer never looks.
By 2018 he was also discussing an obstacle that software alone could not remove: understanding. As Singapore considered a national electronic invoicing framework, he argued that business owners needed help fitting new processes into the way they already paid and collected money. Explaining the benefit was only part of the job. People also needed to know how to use it.
This is a more demanding sales problem than announcing that something is digital. A business has routines, records and people responsible for reconciling them. A new tool must find a place among those habits. Dobson’s emphasis on education gave the issue a practical shape: adoption requires a workable next step for the person at the desk.
It also places his career in context. Before ipaymy, he had worked on the executive team at SinglePlatform, within Constant Contact. His work had already involved technology serving smaller businesses. At ipaymy, that constituency came with a particularly concrete test. The operator’s question was whether the system would help with the next payment, and then the one after that.
“Education is a key factor in success.”Ethan Dobson, on e-invoicing adoption, 2018
The route got longer; the idea stayed familiar
In March 2021, ipaymy’s partnership with Wallex extended the approach to international payments for Singapore users. The announcement described card-funded transfers to more than 30 countries. Overseas rent, supplier invoices and payments to remote workers could move through the service. Exchange rates, fees and payout information were presented before confirmation, bringing cross-border details into the payment decision.
Those are historical launch details rather than a promise that every route remains available today. The continuing idea is straightforward: the payer chooses a funding method, while the recipient gets a bank payment. Crossing a border adds currency conversion and delivery arrangements, but leaves the original question intact. Can the customer use an existing payment resource for an expense that previously required cash?
A partnership with TripleA added another version of that question in 2023. Singapore customers could fund expenses with cryptocurrencies while recipients received ordinary currency in their bank accounts. The announcement named Bitcoin, Ethereum and Tether. The supplier did not have to acquire a wallet or become interested in digital assets. The payment service handled the conversion between the two sides.
The surrounding team also became part of the story. Catherine Szulyk, speaking as chief operating officer in Worldpay’s account of its work with ipaymy, described the need for a partner able to support both payment processing and wider commercial opportunities. She reported settlement times shortened by 50% in Australia and 40% in Malaysia. Those figures concerned settlement time, rather than company growth or revenue.
Eventually, someone has to pay you
Helping a business send money addresses only one side of its calendar. The other side contains the invoices it has issued and the customers it is waiting on. In January 2024, ipaymy announced Fetch, an automated invoicing platform for small businesses across Singapore, Hong Kong, Malaysia and Australia. Dobson was still speaking as CEO at that launch.
Fetch offered invoice creation and tracking, automated reminders, and tools including early-payment discounts and instalments. Customers could be offered card and cryptocurrency payment options without the business building the additional infrastructure itself. The stated aim was to improve collection and cash flow while making customer relationships easier to manage. A reminder can be automated; the relationship behind it still matters.
There is a pleasing symmetry in that progression. The early product helped a business choose how to pay another business. Fetch helped that business give its own customers more ways to pay. Both address the same calendar from different directions. More time before cash goes out and less time before cash comes in can be valuable for different reasons.
Introducing the product also required explaining it. For Fetch’s Singapore and Hong Kong launch campaign, ipaymy worked with Verra Asia on positioning, a brand refresh and targeted communications. The work included a staged media rollout and outreach to prospective business customers. Product design and the explanation of a product met in the same place: somebody had to understand what problem this service would solve.
goes out
Pay eligible expenses with a card.
comes in
Give customers more ways to pay.
A founder, an airline seat, and the next chapter
There are personal details around the payment diagrams. Dobson speaks basic Mandarin and has described a particular enthusiasm for flying: being a passenger, with an interest in the aircraft’s seats and service. It is a useful reminder that a business built partly around credit card rewards has a founder who takes an interest in the journey itself.
His current LinkedIn profile places him in Irvine, California. The company he founded operates across Singapore, Hong Kong, Malaysia and Australia. Today ipaymy lists Dobson as executive chairman and Olivia Leong as CEO. Her background includes Visa and American Express. The leadership titles have changed since the early interviews, while the company continues to work on paying and collecting money.
The ambition question is worth remembering alongside that change. A founder can describe a company through its eventual size, or through the work it helps other people get done. Dobson chose to talk about the people. The customers supplied their own version of that answer when they asked to use a consumer rewards service for business expenses. They had a payment coming up. They wanted another way to handle it.
Keep following the story
- Company & current leadership
- Ethan on LinkedIn
- Ethan on X
- Watch: The Startup Buddy interview
- Five questions with Ethan Dobson
- The early product, in his own words
- His comments on e-invoicing
- Fetch’s January 2024 announcement
- The Worldpay partnership
- The Wallex announcement
- The TripleA announcement
- Fetch’s launch campaign
- The 2017 seed round and business focus