Elias Sabo was ahead by 0.065 seconds. At Sonoma Raceway in April 2024, his Aston Martin had edged Jason Daskalos's Mercedes to the top of the SRO3 timing sheet. His lap took 1 minute, 34.868 seconds. The gap was small enough to disappear inside an ordinary blink. It was also quite sufficient for the job.
At work, Sabo had spent years arguing for a more forgiving relationship with time. As a founding partner of the organization behind Compass Diversified, he helped build an investment business that could own companies without a fund's scheduled expiration forcing a sale. On a racetrack, fractions of a second mattered. In a portfolio, room to wait could matter just as much.
The contrast makes a useful entrance into his life, provided we resist the temptation to turn an Aston Martin into a management textbook. Driving quickly proves that someone can drive quickly. Sabo's business record has its own evidence, including acquisitions, sales, years of board service and a difficult accounting crisis. The two pursuits share a person. Their results require separate scoreboards.
A California address, a Connecticut company
Sabo's professional biography begins with Rensselaer Polytechnic Institute. He graduated from the university and played linebacker there, in Division III football. He moved to California in 1992. Before Compass, his employers included Colony Capital, CIBC Oppenheimer and Boundary Partners. Those names place his early career among transactions and investment firms, well before his name appeared beside the chief executive title.
In 1998, he helped establish Compass. Its early form was a unit of a nonprofit seeking to diversify its investments into private equity. The public company followed in 2006, starting with four businesses. That distinction matters: the founding date and the stock-market debut describe different stages of the enterprise. An organization can have a substantial childhood before investors meet it on an exchange.
His work also took him into Fox Factory, the suspension-products business that became a former Compass holding. He served on its board during the 2007-2017 period. Fox's own records add a more operational detail: he was president from January 2008 until June 2013. He later led the board as chairman, stepping down in July 2017.
When Larry Enterline, then Fox's chief executive, marked that departure, he singled out Sabo's business judgment and affection for the brand. Board service can look like a dry line in a biography. Here it involved a recognizable manufacturer, a presidency and a relationship that would return to the story years later. The name on the organizational chart had done more than attend meetings.
Sabo became Compass Diversified's chief executive and a director in May 2018. His remit includes investment evaluation, financing and the company's strategic direction. Compass has its headquarters in Westport, Connecticut; Sabo's professional base is Costa Mesa, California. A corporate address and the place where its leader works need not coincide. The business has offices in both places.
The luxury of an unscheduled exit
To understand Sabo's central business idea, start with the clock attached to the money. A conventional investment fund has a lifespan. Its owners eventually expect capital back. That creates practical pressure around the moment when a business must be sold, even if the business itself would benefit from more time under the same owner.
Compass's permanent capital structure gives it another option. It buys controlling interests in middle-market businesses, with a focus on branded consumer and industrial companies. It can retain those businesses without the same fund deadline. Meanwhile, investors can trade Compass shares in the public market. The operating company and the shareholder therefore have different ways of moving on.
That arrangement is the interesting piece of engineering. An owner can stay while an investor leaves. It gives the management team of a subsidiary a chance to work through investments whose payoff takes time: equipment, systems, people or a complementary acquisition. The stock market still supplies a verdict every trading day. Patient ownership does not remove impatient opinions.
“We're looking for companies that can preserve their place in the marketplace.”
Elias Sabo, 2021
Compass describes itself as providing both debt and equity financing for transactions. In its sustainability discussion, Sabo explained the preference for raising financing at the holding-company level rather than loading each subsidiary with debt. His stated reasoning is practical: obligations can restrict what managers are able to do. Capital structure reaches all the way down to operating decisions.
The model also brings responsibilities upward. A holding company that finances and oversees a collection of businesses must understand what happens inside them. Autonomy can help managers work; oversight must still test the numbers they produce. This is where the attractive language of long-term partnership meets the less photogenic business of controls. A filing cabinet seldom gets the glamour shot.
Conceptual diagram. Permanent capital permits longer ownership; it does not promise a holding period or an investment return.
A baseball business comes back to Fox
Permanent capital leaves the sale date open. It also leaves selling available. Marucci Sports offers a concrete illustration of how that worked during Sabo's tenure. Compass bought the baseball-equipment business in 2020 for $200 million. It subsequently spent approximately $70 million on add-on acquisitions. In November 2023, it completed a sale at an enterprise value of $572 million.
The buyer was Fox Factory. Sabo's earlier boardroom world had become the destination for a later Compass investment. The connection gives the transaction a pleasing circularity, although a familiar name should never substitute for the economics. The original purchase price, additional acquisitions and eventual enterprise value are distinct figures. Simply subtracting the first number from the last would leave out too much.
Marucci's chief executive, Kurt Ainsworth, has described Compass's support in terms of strategic focus and help pursuing a longer-term vision. His account supplies the operating manager's side of an investment that otherwise fits neatly into three numbers. Growing a company involves choices made between the purchase announcement and the sale announcement. Those middle years rarely fit on a celebratory slide.
For Sabo, the example demonstrates flexibility rather than a pledge to own everything forever. An investment business can make room for a long holding period and still accept a transaction that serves its shareholders. The discipline lies in deciding when the business, the available price and the use of the proceeds justify that decision. Patience is an option with value; it is also an option that can be exercised selectively.
The other place he learned the circuit
Sabo's racing career has a chronology of its own. He entered what was then the Pirelli World Challenge in 2018. By 2020, he was racing Audi machinery with Andy Lee. The pair joined Flying Lizard Motorsports in 2022, moving into Aston Martin Vantage GT4 cars. These were organized race programs, with classes, teammates and season commitments.
That background puts the Sonoma timing result in proportion. By April 2024, he had moved into GT3 machinery. His fastest SRO3 lap in the second practice session put him just ahead of Daskalos. It was a specific achievement on a specific morning, earned against a field of other drivers. There is no need to inflate it into a championship to make the detail interesting.
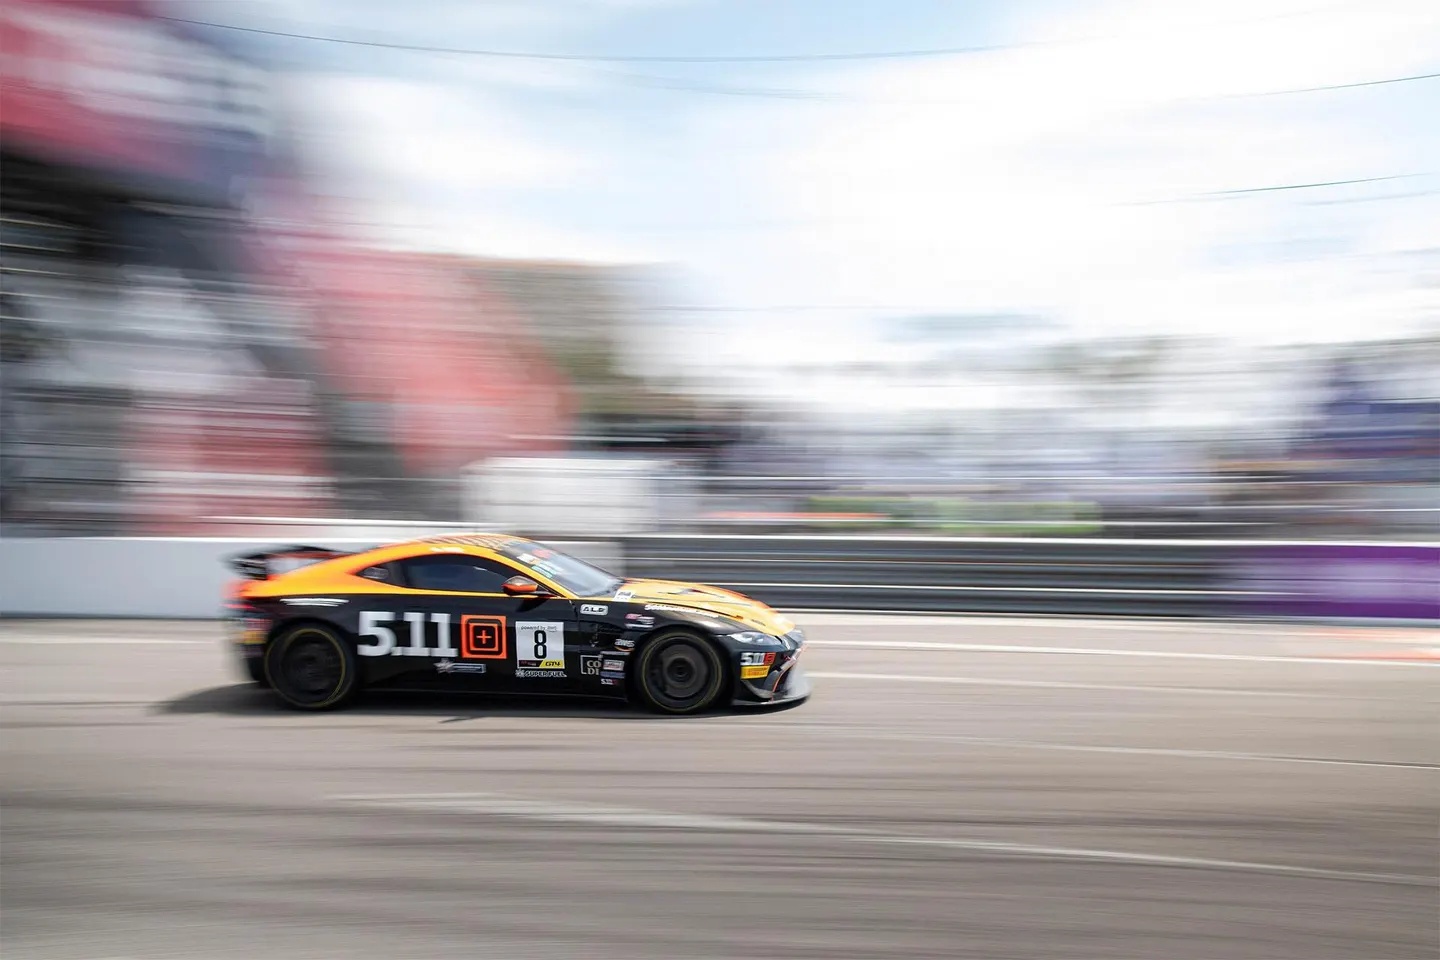
Later that month, Long Beach offered another kind of milestone. Flying Lizard entered Sabo and Lee in the No. 28 Aston Martin Vantage GT3 Evo for the team's return to the IMSA WeatherTech SportsCar Championship. The race marked their championship debuts. For Sabo, the local event was a bucket-list ambition, close enough to home to bring his business world into the occasion.
Program manager Darren Law described the preparation: simulator work to learn the circuit, Lee's coaching and a plan to complete the race and gain experience. That account is more revealing than a generic claim about fearlessness. Here was an established chief executive arriving in a new competition with homework to do and people to learn from. A job title offers little assistance with a braking point.
When the long view met a hard year
A complete account of Sabo's tenure must include Lugano. Compass acquired the jewelry business in 2021. In 2025, an investigation into its financing, accounting and inventory practices led Compass to restate financial statements for 2022, 2023 and 2024. The company's investigation concluded that Lugano's former chief executive had engaged in fraudulent activity, including fictitious sales and misrepresented inventory.
Those are the company's stated findings about the subsidiary's former leader. They are also a serious failure within the portfolio Sabo led. Lugano entered bankruptcy in November 2025 and was removed from Compass's consolidated financial statements. The episode complicated a business built around the promise of responsible ownership. Time to grow a company provides no exemption from the obligation to verify what it reports.
The response continued into 2026. By its August results announcement, Compass reported a settlement intended to facilitate the orderly liquidation of Lugano's assets. It had also sold Sterno's food-service business and applied more than $280 million of proceeds to debt reduction. Changes to the management-services agreement were intended to reduce expected fees and tie more compensation to operating performance and shareholder returns.
These were tangible changes in assets, debt and incentives. They belong in the same portrait as the earlier acquisitions. A chief executive's career is made from the decisions taken when the model works and the repair work demanded when something goes wrong. Leaving out either side would make the person easier to describe and the description less useful.
On June 11, 2026, Compass announced that Sabo would retire as chief executive and a director on December 31. Zach Sawtelle was named his successor, with the next chief executive's tenure scheduled to begin on January 1, 2027. As of October 2026, Sabo remains in the role, working toward that handoff.
“Leading CODI has been the honor of my career.”
Elias Sabo, June 2026
The final stretch has a deadline after all. Nearly three decades after helping establish Compass, Sabo has a date for passing responsibility to someone else. His investment argument gave businesses more room to choose their moment. His own next task is narrower and concrete: complete the transition. The patient owner and the racing driver both arrive, eventually, at a line someone must cross.
Follow the next lap
Company news, Sabo’s public profile, an interview and racing coverage.